A raise, not a beat.
Thesis
Bull case
The biopharma recovery is real and TMO is its cleanest expression: bioprocessing orders (Danaher mid-teens) and Sartorius's confirmed guidance point to accelerating 2H demand, TMO's Q2 showed the beat-and-raise pattern with 90bp margin expansion, and estimates are drifting up with virtually no downward revisions (4 up/0 down for FY26, 5 up/1 down for FY27). At 26.3x forward — below its historical band — a Q3 beat plus a raise above $25.33 with evidence of order conversion and stable academic/China commentary could push FY27 consensus above $27.58 and justify the $730–$760 fresh targets and beyond.
Bear case
The rally has pre-paid the recovery. Consensus sits at management's own guided bar, and the effective bar is likely above it after +31% in 3 months — an inference from the rally and tight consensus range, not from any whisper or options data gathered here. Even bull targets imply only 6–10% upside while the average target sits below the price. The sector recovery is confirmed in direction only — Danaher cut FY guidance on conversion timing, academic/NIH funding remains weak (Revvity said so explicitly), and China demand is unverified. An in-line print with unchanged guidance is a sell-the-news candidate at 52-week highs; a print below ~$6.33 or any guidance trim breaks the beat-and-raise pattern on a stock with ~100% idiosyncratic exposure and no beta cushion.
What would change our mind
- FY26 EPS guidance raised above ~$25.33 or organic growth guide above ~4% — converts NO_CLEAR_EDGE into an upgradeable setup and validates the rally
- Q3 EPS below ~$6.33 or any FY guidance trim — confirms the bearish break of the beat-and-raise pattern
- Management shifts academic/government language from 'stabilizing' to 'declining' — breaks the soft-landing leg of the thesis
- Forward P/E re-rating above ~31x without estimate upgrades — would flip the valuation cushion argument bearish
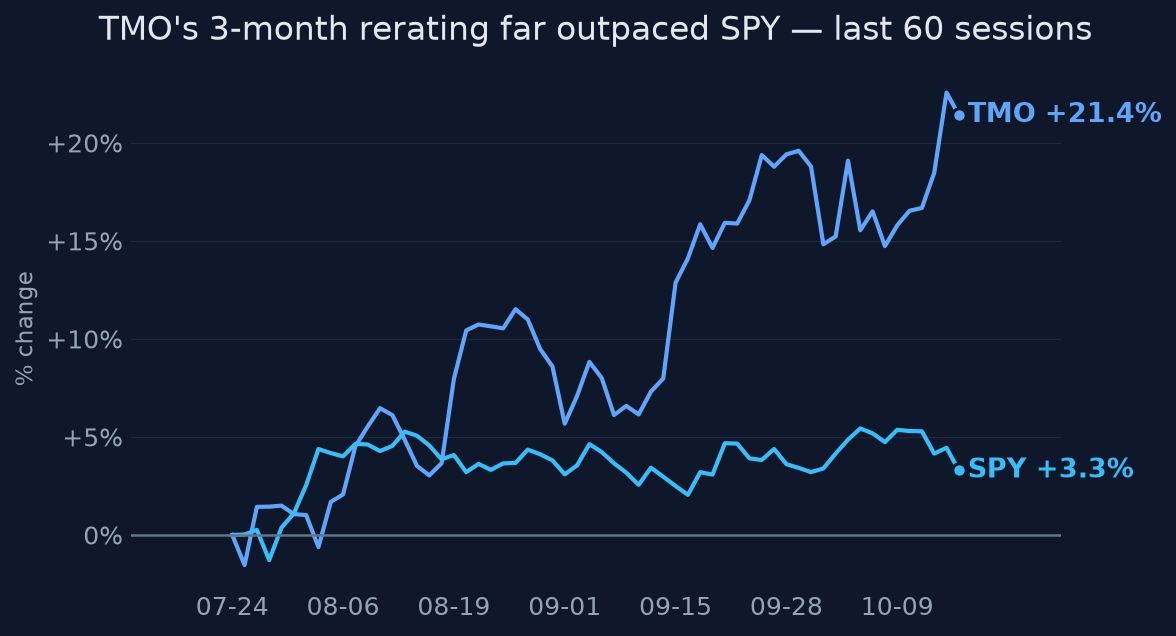
Since publication vs SPY · closed horizons are frozen
The full research everything the view rests on
Direct answer to the question asked
Where the edge would come from
What the price assumes
Q3 2026 adj. EPS ~$6.40 (range ~$6.33–$6.47), revenue ~$11.93–11.95B (~7.5% y/y growth); FY26 consensus $47.89B / $25.15, ~$0.02 above the guidance midpoint of $24.93–$25.33; organic growth ~4% in 2H, roughly even between Q3 and Q4. Estimates revised up ~1.2% over 3 months (4 up/0 down for FY26, 5 up/1 down for FY27). The track record the market is extrapolating: Q2 beat by ~$0.31 EPS and ~$280M revenue with 90bp margin expansion and a guidance raise.
Why the market may be wrong
Two ways. Bullish: peer evidence (Danaher's mid-teens bioprocessing order growth, Sartorius's confirmed 5–9% cc growth guidance, Revvity's raise) suggests the biopharma recovery is real in direction, and if TMO shows order-to-revenue conversion where Danaher stumbled, FY27 consensus (~$27.58) could prove conservative at a below-historical-average multiple. Bearish: the recovery is 'confirmed in direction, not breadth' — Danaher cut FY core growth guidance, Revvity raised while noting academic funding remains weak, and TMO's own 'academic/government stabilizing' language is from July and may be stale if NIH/federal funding deteriorated since. A stock with ~100% idiosyncratic share (60d beta ~0.1, correlation ~0.04) has no market-beta cushion if the story disappoints.
The one thing to watch
The variable to watch is not Q3 EPS versus the $6.40 consensus — it's the FY26 guidance range relative to its own top end. Management set the Q3 bar in July ($6.38–$6.43 implied), consensus dutifully converged to it, and the rally consumed the sell-side's re-rating headroom; so the print is almost pre-discounted and only a raise above ~$25.33 (or a trim below ~$24.93) actually re-prices the stock. Secondarily: TMO's recent move is ~100% idiosyncratic (60d correlation to SPY ~0.04), so earnings land on a stock with zero beta shelter in either direction.
Key evidence (8)
- Earnings date confirmed: Q3 2026 release Oct 21, 2026 before market open, call 7:00 a.m. ET [T1 Thermo Fisher IR]
- Q2 2026 actuals: adj. EPS $6.03 vs ~$5.71–5.72 est, revenue $11.99B vs ~$11.71B est, adj. op margin 22.8% (+90bp y/y), organic growth 5% [T4 Yahoo/transcript summary]
- Q2 guidance raised: FY26 revenue $47.4–48.1B, adj. EPS $24.93–25.33, organic ~4% in 2H; Q3 EPS guided $0.35–0.40 above Q2 [T4 transcript summary]
- Consensus: Q3 ~$6.40 EPS / ~$11.95B rev; FY26 $47.89B / $25.15; FY27 $50.36B / $27.58; revisions +1.2% over 3 months, 4 up/0 down (FY26) and 5 up/1 down (FY27) [T3 MarketWatch / T4 Macroaxis]
- Price setup: ~$690, -0.9% below 52w high, +31% over 3m/6m vs SPY +2.9%/+7.5%; max drawdown -31.4% within the year; 60d beta to SPY ~0.1, correlation ~0.04 [market data]
- Forward P/E ~26.3x, at/below bottom of cited 26.7x–31.5x historical band [T4 StockAnalysis/valueinvesting.io]
- Recent PT raises: Morgan Stanley $650→$730 Overweight, BofA $745, Barclays $750, TD Cowen $675→$760; stale consensus target ~$642 [T4]
- Peer read-through: Danaher Q2 2026 — strongest Life Sciences quarter in years, bioprocessing orders mid-teens, but FY core growth cut to 3–4% (from 3–6%) on order-to-revenue timing [T4 Danaher IR]; Revvity raised FY outlook with academic funding noted weak [T2 Reuters]; Sartorius confirmed 2026 cc growth ~5–9%, expecting stronger 2H [T4]
Catalysts and risks
Catalysts
- Q3 2026 earnings release and call, Oct 21, 2026 before market open [T1]
- FY26 guidance update on that call — the decisive variable (raise above $25.33 vs trim below $24.93)
- Management commentary on academic/government/NIH funding vs July's 'stabilizing' language
- China demand, export-control, and stimulus commentary (no primary-source data pre-release)
- Agilent's next report (unverified in this research) as an instruments cross-check
- Q4 2026 report Jan 27, 2027 (est. $7.34 EPS / $13.0B revenue)
Risks
- Sell-the-news on an in-line print: consensus already at the guidance-implied bar after a 31% run
- Academic/NIH funding deterioration since July contradicting the 'stabilizing' narrative — exposure unquantified
- China weakness (export controls, local competition) hitting instruments — no primary-source Q3 data available
- Order-to-revenue conversion risk: Danaher showed bioprocessing orders not translating smoothly to shipments
- No market-beta support: 60d correlation to SPY ~0.04 means a company-specific miss is unbuffered
- The 'effective bar above consensus' framing is an inference from price action; no whisper or options-implied-move data was gathered to confirm it
- Key factual inputs (some PT data, China/NIH exposure) rest on T4 sources only
What to watch
- FY26 guidance midpoint and top end vs $25.13/$25.33 on the Oct 21 call
- Organic growth split: bioproduction/biopharma vs academic/government vs China
- Evidence of bioproduction order-to-revenue conversion (the Danaher failure point)
- Any quantification of NIH/academic exposure — direct revenue vs second-order university customers
- Post-print estimate revisions: whether FY27 consensus ($27.58) moves and in which direction
- Stock reaction vs the 52-week high: failure to hold gains on a beat would confirm sell-the-news positioning
Market snapshot when the call was made 2026-10-16
Price
| Return 1w | +4.9% |
| Return 1m | +4.8% |
| Return 3m | +31.1% |
| Return 6m | +31.2% |
| Return 1y | +31.1% |
| From 52-week high | -0.9% |
| Realized vol, 20d | 27.3% |
| SPY 3m / 1y | +2.9% / +14.8% |
| QQQ 3m / 1y | +2.0% / +17.9% |
Technicals
TMO technicals as of 2026-10-16: last close $690.00; 20d SMA 668.35 (bullish); 50d SMA 636.69; 12d EMA 671.18; 26d EMA 658.20; RSI 14 54.1 (balanced); 20d vol 27.1%; volume x1.0 vs 20d avg
Next earnings: 2027-01-27 AMC
Verifier notes REVISE · opinion revised once
Unsupported claims
- Bull case: 'estimates are drifting up with zero downward revisions' — the evidence shows 4 up/0 down for FY2026 but 5 up/1 down for FY2027 (Macroaxis via fundamentals search), so 'zero' is an overstatement. The opinion's own market_expectation field correctly says '~0 down', making the bull-case wording internally inconsistent as well.
Weakly sourced
- Answer and bear case state 'the effective whisper is above it' / 'the whisper is above it' as fact. The evidence bundle contains no whisper or options-implied-move data, and the planner digest explicitly lists 'whether Q3 buy-side whisper is meaningfully above the $6.40 consensus' as unknown. The risks section partially discloses this ('whisper framing... rest on T4 sources only'), but the direct_answer asserts it flatly, and it underpins the core 'a routine beat won't move the stock' conclusion.
Corrections applied
- Soften the whisper assertion to an explicit inference, e.g. 'after a 31% run, the effective bar is likely above consensus (no whisper/options data was gathered to confirm this)', and apply the same hedging in the bear case.
- Change the bull case to 'estimates are drifting up with virtually no downward revisions (4–5 up vs ~1 down across FY26/FY27)' to match the revision-breadth data and the opinion's own market_expectation field.
Sources (16 · T1 = primary filings)
- T4https://finance.yahoo.com/quote/TMO/
- T4https://finance.yahoo.com/markets/stocks/articles/thermo-fisher-scientifics-q3-2026-131823695.html?fr=sycsrp_c…
- T4https://news.alphastreet.com/thermo-fisher-scientific-tmo-q3-2026-preview-eps-est-6-40-reports-october-21/
- T4https://uk.finance.yahoo.com/quote/TMO/analysis/
- T4https://www.perplexity.ai/finance/TMO?comparing=TMO,LH,EHC,HSIC,CI,DVA
- T3https://www.marketwatch.com/investing/stock/tmo/analystestimates
- T4https://www.marketbeat.com/instant-alerts/upcoming-thermo-fisher-scientific-tmo-projected-to-post-quarterly-ea…
- T4https://www.perplexity.ai/finance/TMO?comparing=TMO,SNY,NVO,DHR,JNJ,MRK
- T2https://www.reuters.com/company/revvity-inc/
- T4https://investors.danaher.com/2026-07-21-Danaher-Reports-Second-Quarter-2026-Results
- T4https://www.sartorius.com/download/1817684/q1-2026-download-earnings-report-sag-en-data.pdf
- T4https://www.matterfact.com/newsletter/2026-08-23-life-science-tools-funding-china
- T4https://finance.yahoo.com/markets/stocks/articles/danaher-stock-pricing-recovery-earnings-161809530.html
- T4https://investors.danaher.com/2026-04-21-Danaher-Reports-First-Quarter-2026-Results
- T4https://vectorshift.ai/research/companies/danaher-de/earnings/2026-q2-summary
- T4https://simplywall.st/stocks/us/pharmaceuticals-biotech/nyse-dhr/danaher
Want a fresh look at TMO, or another name?
Queue a new deep-research run. Published to the feed when done.
Automated research opinion, published as-is on Oct 19, 2026. Not personalised advice. Figures use end-of-day closes.