No clear edge here.
Thesis
Bull case
War disruption persists into 2027, keeping Brent >$100 while OXY uses the windfall to hit the $10B debt target quarters early. Interest savings compound ($1.7B of the $4B plan), the market begins dating buyback resumption, and OXY rerates from a leveraged E&P multiple toward peer cash-return multiples — UBS $73 / BMO $68 targets get run over. The structural plan means even normalized ~$84 oil supports a higher earnings floor than current consensus implies.
Bear case
Hormuz normalizes in 2027 (EIA $84 base; some analysts $60 late-2027), and OXY gives back the war premium exactly as the OxyChem earnings hole and suspended buybacks become visible. The preferred blocks distributions until 2029, the >$4/share trigger taxes any early return attempt, and a stock at RSI 78 with a 27.6% max drawdown history retraces a large part of its war-driven run — the stock sits ~60% above its 52-week low (~$39), which was ~38% below today's price, illustrating how far a full unwind could reach. A specific downside target is a scenario estimate, not an evidence-derived anchor.
What would change our mind
- If OXY hits $10B debt and explicitly schedules buyback resumption before mid-2027 while oil holds >$85, the 'no edge' view is wrong — that is a rerate trigger worth sizing
- If FY2027 consensus EPS holds above ~$7 while Brent normalizes to $84, the structural-plan floor is real and the stock is cheap at 11x
- If Brent breaks below $75 with the debt target still unreached, the deleveraging-slows bear case activates and downside asymmetry dominates
Since publication vs SPY · closed horizons are frozen
The full research everything the view rests on
Direct answer to the question asked
Where the edge would come from
What the price assumes
The market prices OXY as an oil proxy with credit improvement: FY2026 consensus EPS ~$9.04 (revised up from $8.06) but a forward P/E of only ~11.2x [both T4 aggregator data, weakly sourced], which — if the forward P/E is off a lower 2027 estimate — implies the war premium is treated as temporary. Consensus Hold with a ~$66.71 mean target (~7% upside) says the street sees the deleveraging story as largely recognized.
Why the market may be wrong
Two-sided: bulls would say the market under-credits the $4B/2030 structural cash-flow plan (~85% achievable at low oil prices, $1.7B from interest savings alone), which raises the normalized earnings floor above what a simple multiple on 2027 consensus captures. Bears would say the market under-prices the OxyChem earnings hole and the risk that oil mean-reverts to $60-70 while buybacks remain suspended and the Berkshire preferred still blocks capital return — leaving OXY the only major E&P not returning the windfall.
The one thing to watch
The variable to watch is not oil — it is the pace of the last $2-3B of debt paydown to the $10B target, because that is the gate on the entire capital-return story: buybacks are suspended, the Berkshire preferred is locked until Aug 2029, and any >$4/share distribution forces preferred redemption at a 10% premium. OXY's equity rerates when the market can date the resumption of buybacks, not when WTI ticks up — and the war windfall ironically accelerates that date, making OXY a call option on deleveraging speed disguised as an oil stock.
Key evidence (8)
- Debt cut from ~$28.9B (CrownRock close Aug 2024) to ~$11.8-13.3B by mid-2026; $10B principal target nearly reached (S&P via [T3]; company Q2 slides [T4])
- OxyChem sold to Berkshire for ~$9.7B cash, closed Jan 2026, proceeds to debt ([T3])
- Q2 2026 (Aug 5, 2026): adj. EPS $2.40 vs $1.92 est; production 1,433 Mboe/d above guidance; FCF ~$3B, highest since Q3 2022 ([T1] 8-K earnings release)
- Plan for >$4B annual sustainable cash-flow improvement by 2030, ~85% achievable at materially lower oil prices; >$1.2B delivered in 2026 pre-price (Q2 call [T1/T4])
- Buybacks suspended since 2024; Berkshire preferred not voluntarily redeemable before Aug 2029; redemptions planned from 2029 (Reuters [T2], S&P [T3])
- Brent ~$105.92 / WTI ~$97.75 on Oct 16, 2026 amid US-Israel/Iran war; Gulf OPEC+ exports at 60-80% of normal; EIA 2027 base case ~$84 Brent (Reuters [T2], EIA via [T3])
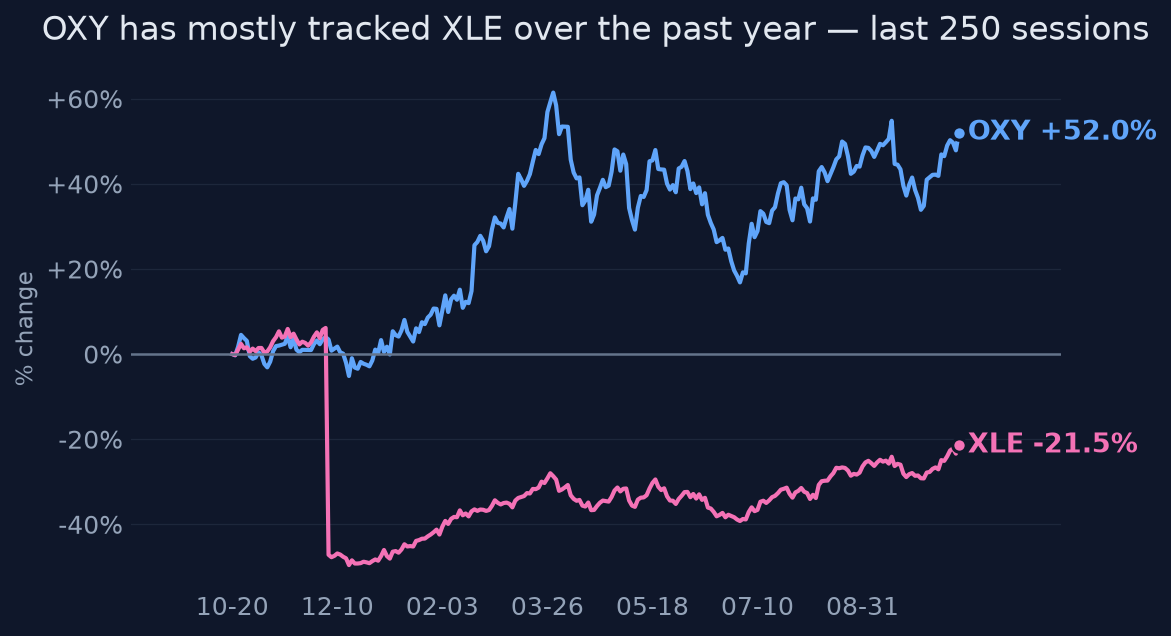
- Stock +49% 1y, RSI 78, 5.8% below 52w high and ~60% above its 52w low (~$39); 60d correlation with XLE 0.88 (quant analysis)
- FY2026 consensus ~$27.2B rev / ~$9.04 EPS revised up; forward P/E ~11.2x; consensus Hold, mean target ~$66.71 ([T4] aggregators — weak sourcing; the implied normalized EPS rests entirely on these figures and should be treated as indicative)
Catalysts and risks
Catalysts
- Q3 2026 earnings (expected early November 2026) — debt balance print vs $10B target is the key number
- Any announcement of reaching the $10B principal debt target and updated capital-return sequencing
- Iran war resolution/ceasefire or Hormuz normalization — resets the oil deck either way
- OPEC+ 2027 quota review (delayed) and December 2026 policy decisions
- EIA/IEA 2027 supply-demand updates confirming or breaking the ~$84 normalization case
Risks
- Oil price mean reversion: $60-70 Brent scenario cuts normalized EPS well below current 2027 expectations
- OxyChem divestiture earnings hole not yet quantified in consensus (unverified in evidence)
- Berkshire preferred: its dividend and redemption economics (10% redemption premium, Aug-2029 lock, >$4/share trigger) claim cash before common holders through 2029 — the evidence does not specify the preferred's coupon
- RSI 78, 0.88 XLE correlation — positioning is crowded long oil via OXY
- Key data gaps: Q3 earnings date unconfirmed, $1/WTI cash-flow sensitivity undisclosed, analyst targets and forward P/E rest on [T4] aggregators
What to watch
- Q3 2026 principal debt figure vs the $10B target (the single most important print)
- Management language on capital-return sequencing — any pull-forward of buybacks or preferred plans
- Brent Dec-2027 futures vs the EIA $84 base case — the market's real normalization bet
- Whether the 0.88 XLE correlation breaks down post-earnings (idiosyncratic re-rating signal)
- Verified FY2027 consensus EPS — the unverified input that determines whether 11.2x is cheap or fair
Market snapshot when the call was made 2026-10-16
Price
| Return 1w | +3.8% |
| Return 1m | +5.2% |
| Return 3m | +13.0% |
| Return 6m | +16.0% |
| Return 1y | +49.0% |
| From 52-week high | -5.8% |
| Realized vol, 20d | 30.4% |
| SPY 3m / 1y | +2.9% / +14.8% |
| QQQ 3m / 1y | +2.0% / +17.9% |
Technicals
OXY technicals as of 2026-10-16: last close $62.38; 20d SMA 58.53 (bearish); 50d SMA 59.32; 12d EMA 60.19; 26d EMA 59.41; RSI 14 78.2 (overbought); 20d vol 28.5%; volume x1.3 vs 20d avg
Verifier notes REVISE · opinion revised once
Unsupported claims
- 'Berkshire preferred: 8% cost' (risks) — the evidence describes the preferred's Aug-2029 redemption lock, 10% redemption premium, and >$4/share trigger, but never states an 8% dividend/coupon cost. This specific figure appears nowhere in the bundle.
- 'round-trips toward the mid-$40s' (bear_case) — no evidence figure supports mid-$40s as a downside anchor; the implied 52-week low is ~$38.90 (price is 60.28% above the low). The bear target should be tied to evidence or framed as unanchored speculation.
Weakly sourced
- Embedded normalized EPS of ~$5.50 rests entirely on [T4] aggregator data (forward P/E 11.2x, FY2026 consensus $9.04) — the opinion does flag this as weak sourcing in key_evidence and what_to_watch, which is adequate, but the thesis leans heavily on it; acceptable but borderline.
Internal inconsistencies
- Bear case states 'the 2026 lows were ~60% below current price' — arithmetic error. The evidence says the stock is 60.28% ABOVE its 52-week low, which implies the low (~$38.90) was ~37.6% below the current price, not 60%. Percent-above and percent-below are not symmetric.
Corrections applied
- Fix the bear-case arithmetic: replace 'the 2026 lows were ~60% below current price' with 'the stock sits ~60% above its 52-week low (~$39), which was ~38% below today's price'.
- Either remove the '8% cost' on the Berkshire preferred or restate it qualitatively ('the preferred's dividend and redemption economics claim cash before common holders through 2029') since the 8% figure is not in the evidence.
- Re-anchor or soften the bear downside target: replace 'mid-$40s' with a reference to the ~$39 52-week low, or explicitly label the target as a scenario estimate not derived from the evidence.
Sources (32 · T1 = primary filings)
- T3https://www.spglobal.com/ratings/en/regulatory/article/-/view/sourceId/101684108
- T3https://www.spglobal.com/ratings/en/regulatory/article/-/view/type/HTML/id/3560139
- T2https://www.reuters.com/company/occidental-petroleum-corp/
- T3https://www.spglobal.com/ratings/en/regulatory/article/-/view/type/HTML/id/3560140
- T4https://www.ainvest.com/news/occidental-petroleum-hidden-cost-preferred-equity-keeping-stock-suppressed-2609/
- T4https://flash.stocksentinel.ai/research/OXY
- T2https://www.reuters.com/business/energy/occidental-sees-flat-spending-output-2027-keeps-focus-debt-reduction-2…
- T4https://www.financialcontent.com/quote/NY:OXY/pressReleases
- T2https://www.reuters.com/business/energy/opec-agrees-principle-keep-november-oil-output-targets-steady-sources-…
- T2https://www.reuters.com/business/energy/oil-prices-slip-traders-weigh-strong-mideast-exports-against-gulf-tens…
- T2https://www.reuters.com/business/energy/opec-set-keep-oil-output-policy-unchanged-sunday-sources-say-2026-09-0…
- T2http://rmb.reuters.com/rmd/rss/item/tag:reuters.com,2026:newsml_KBN3VO037?channel=FBi345
- T2http://rmb.reuters.com/rmd/rss/item/tag:reuters.com,2026:newsml_KBN3VN023?channel=frL012
- T4https://www.thedailystar.net/business/news/oil-rises-middle-east-supply-concerns-persist-amid-shipping-attacks…
- T4https://finance.yahoo.com/news/oil-prices-slip-traders-weigh-003904233.html
- T4https://tribune.com.pk/story/2634964/oil-prices-retreat-as-investors-weigh-supply-outlook-middle-east-tensions
- T4https://www.investing.com/news/company-news/occidental-q2-2026-slides-17b-debt-cut-4b-cash-flow-target-by-2030…
- T4https://finance.yahoo.com/quote/1OXY.MI/earnings/1OXY.MI-Q2-2026-earnings_call-661577.html/
- T4https://www.theglobeandmail.com/investing/markets/stocks/OXY/pressreleases/3721445/oxy-q2-earnings-call-maps-4…
- T4https://www.alphaspread.com/security/nyse/oxy/investor-relations/earnings-call/q2-2026
- T4https://www.investing.com/news/transcripts/earnings-call-transcript-occidental-beats-q2-2026-estimates-as-cash…
- T4https://finance.yahoo.com/quote/OXY/earnings/OXY-Q2-2026-earnings_call-661577.html/
- T4https://finance.yahoo.com/quote/0KAK.L/earnings/0KAK.L-Q2-2026-earnings_call-661577.html/
- T1https://www.sec.gov/Archives/edgar/data/797468/000162828026053377/oxyex9916-30x26earningsrel.htm
- T2https://www.reuters.com/business/energy/us-eia-hikes-oil-price-forecasts-again-iran-war-drains-global-stockpil…
- T4https://www.conocophillips.com/investor-relations/
- T4https://www.iea.org/reports/oil-market-report-october-2026
- T4https://www.thedailystar.net/business/global-economy/news/oils-long-view-darkens-iran-war-refuses-end-4299736
- T4https://www.thenationalnews.com/business/economy/2026/10/15/imf-official-says-buffers-against-iran-war-price-s…
- T4https://blog.metalpilot.com/sector-analyses/us-large-cap-oil-producers/
- T4https://www.scribd.com/document/922867542/Preet-1-1
- T4https://247wallst.com/investing/2026/09/25/cop-vs-eog-which-energy-dividend-actually-survives-the-next-oil-cra…
Want a fresh look at OXY, or another name?
Queue a new deep-research run. Published to the feed when done.
Automated research opinion, published as-is on Oct 17, 2026. Not personalised advice. Figures use end-of-day closes.