Priced ahead of the proof.
Thesis
Bull case
Nine consecutive EPS beats and a genuinely strong iPhone 17 cycle (FQ3 iPhone +22%, China +22%) show execution; Siri AI is finally shipped and tangible, creating real upgrade-cycle optionality into FY27 with the foldable; Services ex-App-Store is growing double digits with 1.5B subs; buybacks and FCF are intact; and the FQ4 guide of +9-11% with supply constraints suggests demand exceeding supply. If Oct 29 delivers a strong December-quarter guide, the premium multiple holds and the Nikkei report gets dismissed as noise.
Bear case
The stock is priced above the entire sell-side's average target while revisions turn negative; headline earnings quality is inflated by one-off tariff refunds; iPhone 18 demand is softer (order cuts, short lead times, China weakness) just as Pro prices rose $100; App Store — the highest-margin Services component — is growing ~2-3% with US revenue declining; and Google TAC economics are less secure post-remedies. A merely in-line FQ4 with a cautious Dec guide could trigger 10-15% multiple compression back toward the ~$296-328 target range.
What would change our mind
- FQ4 revenue/EPS beat with December-quarter iPhone guidance implying mid-teens or better growth and stable ex-refund gross margin ≥48%
- Company or supplier confirmation that iPhone 18 order cuts were reversed or launch-stagger-related
- App Store growth re-accelerating above ~8% for two consecutive months
- FY27 consensus EPS rising above ~$9.75 on upward revisions — converting the rally from multiple expansion to estimate-driven
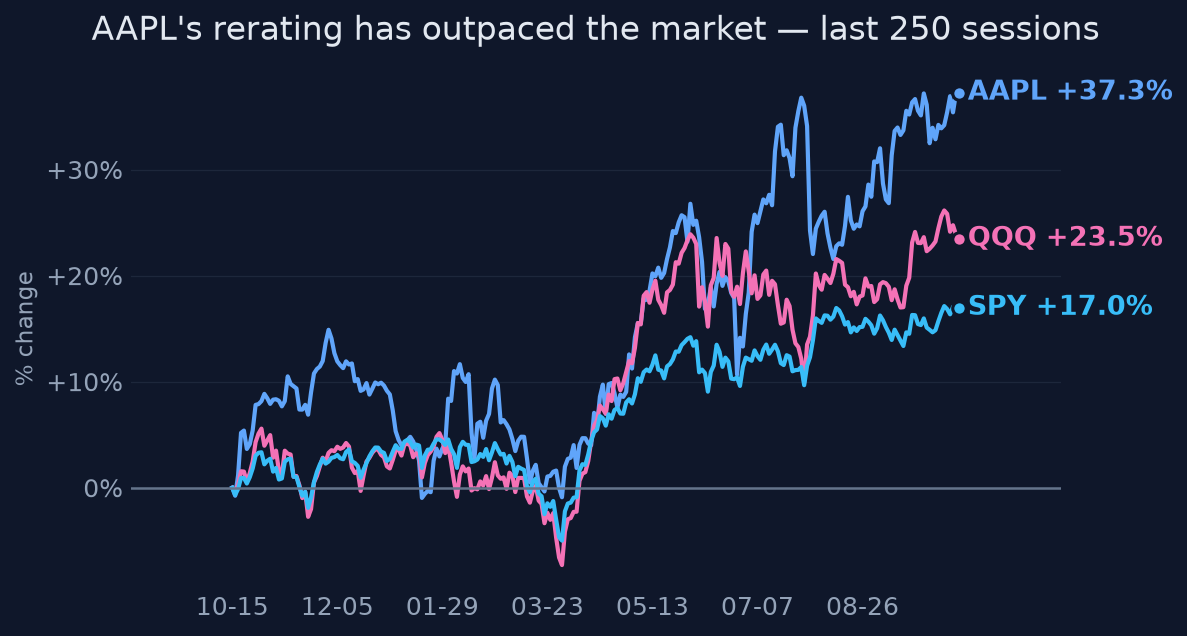
Since publication vs SPY · closed horizons are frozen
The full research everything the view rests on
Direct answer to the question asked
Where the edge would come from
What the price assumes
The price assumes the iPhone 17 strength extends into iPhone 18, that Siri AI/Apple Intelligence catalyzes a multi-year upgrade cycle, that Services sustains low-to-mid-teens growth, and that record margins persist — roughly a 35-37x multiple on ~$9.50 FY27 EPS, a premium even to MSFT/GOOGL and to Apple's own 5-year average ~30.6x.
Why the market may be wrong
The re-rating happened without estimate upgrades — FY26/FY27 EPS consensus barely moved while the P/E expanded ~20%, so the rally is a bet on narrative (AI optionality) rather than revised numbers. Meanwhile the underlying demand signal is deteriorating (order cuts, shorter lead times, China weakness, +$100 Pro pricing), App Store growth has slowed to low single digits with US revenue negative, and headline margins/EPS were flattered by tariff refunds that shrink from ~2pts to ~1pt of benefit in FQ4 and presumably fade thereafter.
The one thing to watch
The single variable to watch is not the FQ4 print itself but underlying (ex-tariff-refund) gross margin and the December-quarter iPhone guide: refunds moved ~200bps of gross margin and ~$0.11 of EPS in FQ3, so headline beats have been subsidized by a one-time item — if ex-refund margin lands ~46-47% while the stock holds 36x, the 'beat streak' is partly an accounting artifact and the re-rating rests on Siri AI converting to unit demand, which lead times so far do not confirm.
Key evidence (10)
- SEC XBRL: FY25 revenue $416.2B (+6.4%), diluted EPS $7.46 (+23%), gross margin 46.9% (record) [T1]
- Forward P/E ~35.4-37.0x (Oct 14, 2026) vs 30.4x on Jun 30 and 5-yr avg ~30.6x; consensus PT ~$328 below price; UBS Neutral $296 PT, JPMorgan $360 [T4 aggregator data, flagged]
- FQ4 EPS revisions negative: 14 lowers vs 7 raises in 30 days to ~Oct 12, 2026 [T4 MarketWatch/247wallst data]
- FQ3 (Jul 30, 2026): revenue $109.4B +16%, EPS $2.02 vs $1.89 est; but tariff refunds added ~2pts GM (50.1%) and ~$0.11 EPS; FQ4 guide GM 47-48% incl ~1pt refund benefit, ~5pt FX drag, supply constraints rising [T1/T4 transcripts]
- Nikkei (Oct 9-10, 2026): Apple cut Oct iPhone 18 Pro/Pro Max component orders 15-20% vs original requests on softer demand — anonymous-source, not company-confirmed [T4 relay of Nikkei]
- JPMorgan tracking: iPhone 18 lead times shorter than iPhone 17 (China 13/21 days vs 30/30); Pro pricing +$100 on memory costs [T3/T4]
- Siri AI shipped in beta with iOS 27 (Sept 14, 2026), cross-app actions across 300k+ apps [T2 Reuters/Apple]
- Services +12% to ~$30.7B/qtr, but App Store growth ~2-3% (US ~-6% June qtr per UBS); Google TAC survived Sept 2025 remedies order but lost exclusivity, now 1-yr contracts [T3/T4]
- CEO transition: Tim Cook to John Ternus effective Sept 1, 2026 — Oct 29 is first earnings call under new CEO [T1 IR/SEC filings]
- Price +39.5% 1y vs SPY +19%, QQQ +26%; at 52-week high; 20d vol at 19th percentile
Catalysts and risks
Catalysts
- FQ4 2026 earnings and December-quarter (FQ1 27) guidance — October 29, 2026; first call under CEO Ternus
- FQ1 2027 report ~Jan 27, 2027 (consensus EPS ~$2.95, revenue ~$156B)
- iPhone 18 sell-through data and any confirmation/denial of further component-order cuts (Nov onward)
- Siri AI expansion beyond English (Oct 2026) and any monetization signals
- Foldable iPhone launch timing (FY27 optionality)
- Potential narrowing of smartphone tariff exemption or further refund normalization
Risks
- Multiple compression from 35-37x toward ~30x historical average on an in-line print
- Tariff-refund benefits ending, exposing ~46-47% underlying gross margin
- iPhone 18 demand weaker than launch optics suggest (Nikkei cuts extend past October)
- App Store deceleration spreading to broader Services
- Google TAC payment reduction at next 1-year contract renewal
- CEO transition execution risk
- Smartphone tariff exemption narrowing (tail risk)
What to watch
- Underlying gross margin ex-tariff-refunds in FQ4 and management's refund commentary
- December-quarter iPhone revenue guide vs the 'mid-teens' FQ4 bar
- iPhone 18 Pro Max lead times and China sell-through through November
- FY27 EPS revision direction after Oct 29 (does the Street finally raise numbers?)
- App Store monthly growth (Sensor Tower/UBS) and any TAC contract news
- Ternus's first-call tone: capex/AI strategy signals
Market snapshot when the call was made 2026-10-14
Price
| Return 1w | +2.3% |
| Return 1m | +2.5% |
| Return 3m | +4.2% |
| Return 6m | +32.0% |
| Return 1y | +39.5% |
| From 52-week high | +0.0% |
| Realized vol, 20d | 16.8% |
| SPY 3m / 1y | +3.1% / +19.1% |
| QQQ 3m / 1y | +3.6% / +26.1% |
Technicals
AAPL technicals as of 2026-10-14: last close $342.96; 20d SMA 336.81 (bullish); 50d SMA 324.46; 12d EMA 337.79; 26d EMA 333.74; RSI 14 57.8 (balanced); 20d vol 16.2%; volume x1.3 vs 20d avg
Next earnings: 2027-01-27
Sources (40 · T1 = primary filings)
- T4https://www.apple.com/hk/en/newsroom/2026/07/apple-reports-third-quarter-results/
- T4https://www.apple.com/gq/newsroom/2026/07/apple-reports-third-quarter-results/
- T4https://www.stocktitan.net/sec-filings/AAPL/8-k-apple-inc-reports-material-event-858294fd8f7d.html
- T4https://economictimes.indiatimes.com/tech/technology/us-tariffs-force-indian-electronics-makers-to-seek-new-ma…
- T4https://finance.yahoo.com/quote/AAPLCL.SN/earnings/AAPLCL.SN-Q3-2026-earnings_call-658553.html/
- T4https://finance.yahoo.com/markets/stocks/articles/apple-q3-earnings-beat-estimates-151300909.html
- T3https://www.cnbc.com/2026/07/30/apple-earnings-live-updates.html
- T4https://finance.yahoo.com/quote/AAPL/earnings/AAPL-Q3-2026-earnings_call-658553.html/
- T4https://247wallst.com/investing/2026/10/12/just-how-sustainable-is-apples-340-price-ahead-of-oct-29-earnings/?…
- T4https://247wallst.com/investing/2026/10/12/apple-stock-price-prediction-wall-streets-next-big-surprise-could-b…
- T4https://www.theglobeandmail.com/investing/markets/stocks/AAPL/pressreleases/20738/apple-stock-forecast-trendin…
- T4https://finance.yahoo.com/markets/stocks/articles/apple-stock-outlook-target-leaves-163030246.html
- T4https://www.investing.com/news/analyst-ratings/bernstein-socgen-reiterates-apple-stock-rating-on-market-share-…
- T2https://www.reuters.com/business/retail-consumer/apple-slides-supply-snags-cloud-outlook-putting-iphone-demand…
- T3https://www.marketwatch.com/investing/stock/AAPL/analystestimates?subview=snapshot&pg=analyst
- T4https://247wallst.com/investing/2026/10/14/apple-just-passed-5-trillion-heres-what-comes-next/?tpid=1680092&tv…
- T4https://www.apple.com/newsroom/2026/09/apple-debuts-iphone-18-pro-and-iphone-18-pro-max/
- T4https://www.apple.com/newsroom/2026/09/major-updates-for-apples-software-platforms-are-now-available/
- T2https://www.reuters.com/technology/foldable-iphone-pricier-18-pro-unveiled-apples-first-event-under-ternus-202…
- T4https://www.investing.com/news/stock-market-news/apple-jpm-says-delivery-lead-times-for-iphone-18-line-down-fr…
- T4https://www.cnbctv18.com/technology/apple-event-2026-iphone-18-pro-airpods-watch-series-12-siri-john-ternus-19…
- T4https://www.apple.com/newsroom/2026/09/siri-ai-a-profoundly-more-capable-and-personal-assistant-is-here/
- T4https://www.apple.com/newsroom/archive/apple-intelligence/
- T4https://economictimes.indiatimes.com/magazines/panache/apple-surprise-and-shine-event-2026-live-updates-iphone…
- T4https://www.roic.ai/news/ubs-flags-apple-app-store-growth-stumble-as-us-revenue-slides-7-10-06-2026
- T4https://finimize.com/content/apples-app-store-rebound-has-ubs-watching-services-growth
- T4https://finance.yahoo.com/markets/stocks/articles/apples-app-store-rebounds-ubs-193942589.html
- T4https://www.streetinsider.com/AI/UBS+holds+Neutral+rating+on+Apple+with+$296+price+target/26737664.html
- T4https://www.mactech.com/2026/08/18/apples-u-s-commission-revenue-has-fallen-18-since-the-start-of-2026/
- T4https://markets.businessinsider.com/news/stocks/apple-app-store-growth-rebounds-to-5-in-september-so-why-is-ub…
- T4https://pluang.com/en/news-feed/apple-tahan-di-rating-netral-ubs-tumbuh-app-store-melambat
- T4https://seekingalpha.com/news/4650640-app-store-reverses-slowdown-in-september-ubs-says?feed_item_type=news
- T4https://www.apple.com/hk/en/newsroom/2026/04/tim-cook-to-become-apple-executive-chairman-john-ternus-to-become…
- T4https://www.apple.com/newsroom/2026/04/tim-cook-to-become-apple-executive-chairman-john-ternus-to-become-apple…
- T1https://investor.apple.com/sec-filings/default.aspx
- T1https://investor.apple.com/investor-relations/sec-filings/
- T4https://fortune.com/2026/10/10/apple-iphone-18-pro-orders-cut-price-hike-memory-chip-shortage/
- T2https://apnews.com/article/apple-ceo-ternus-tim-cook-2fac80118828b4ada9d160d012c7be32
- T4https://www.latimes.com/business/story/2026-09-01/apple-taps-hardware-chief-john-ternus-as-ceo-ending-tim-cook…
- T3https://www.cnbc.com/2026/04/20/apple-names-john-ternus-ceo-replacing-tim-cook-who-becomes-chairman.html
Want a fresh look at AAPL, or another name?
Queue a new deep-research run. Published to the feed when done.
Automated research opinion, published as-is on Oct 15, 2026. Not personalised advice. Figures use end-of-day closes.