De-rating done, but growth hinges on a legal fight.
Thesis
Bull case
The de-rating is complete and the business is demonstrably diversified: record revenue and EBITDA with crypto down 55% proves the model. Options (+31%), equities (+41%), Gold (5.2M subs, 40% new-customer attach), and event contracts (~$692M annualized) collectively more than offset crypto and net-interest declines. October activity stabilizing, opex guidance trimmed, 57% EBITDA margins, and double-digit share gains across every category mean any crypto-volume recovery drops nearly pure profit to the bottom line. At ~27x 2027 EPS with 34% expected growth, the PEG is below 1 — the stock hasn't been this cheap relative to its growth since the re-rating began.
Bear case
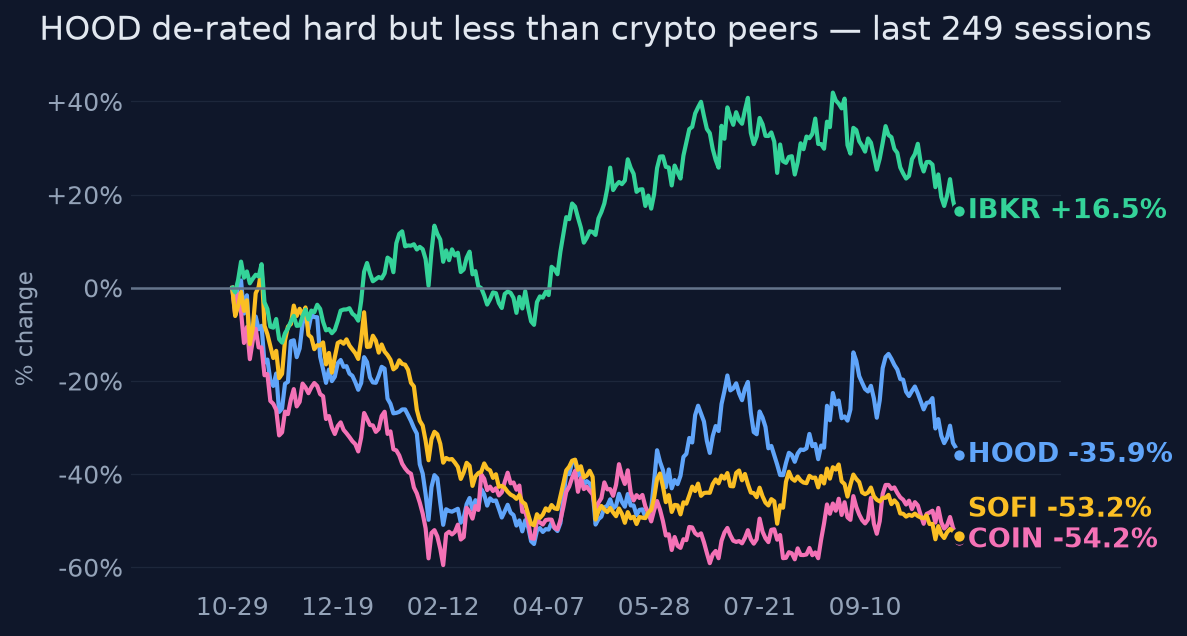
Growth has decelerated from 51% to 12% while GAAP net income is already shrinking (-14%), and the consensus +34% 2027 EPS growth leans on the one revenue line with existential legal risk: the Ninth Circuit has already denied preemption, ~10 states are in active litigation with the CFTC, and a single state injunction against Kalshi-partnered event contracts would cut the fastest-growing stream while crypto (-55%) and net interest (-9%) both decline. At 35x forward for 12% growth, any removal of the prediction-market growth assumption compresses the multiple toward mature-broker levels (IBKR trades far lower), and a 3.9-beta stock in a quiet-vol regime can gap violently on either a court ruling or a crypto leg down.
What would change our mind
- A state or federal court injunction materially restricts Robinhood's event-contract offering before Q4 earnings — thesis's growth leg is removed
- Q4 2026 revenue growth falls below ~+5% YoY with options/equities also decelerating, showing the diversification offset is exhausted
- Crypto revenue declines another >40% YoY in Q4 with no volume stabilization, confirming structural rather than cyclical erosion
- 2027 consensus EPS revisions break materially below ~$3.00, putting the stock back above 30x forward on decelerating growth
Since publication vs SPY · closed horizons are frozen
The full research everything the view rests on
Direct answer to the question asked
Where the edge would come from
What the price assumes
At $94.56 and ~35x forward earnings, the market is pricing continued ~12-15% revenue growth with crypto revenue impaired, net interest declining with rates, and partial credit for prediction-market durability. The ~$2.54 (2026) / $3.42 (2027) EPS path implies the street still expects 34% EPS growth next year — meaning the market is paying up for the event-contract ramp even while applying a discount for its legal risk.
Why the market may be wrong
Two-sided. Upside: the market may be over-extrapolating the crypto decline as structural when COIN (-50%) and HOOD's own October activity (within ±5% of Q3 across equities, options, and crypto) suggest cyclical stabilization; a crypto-volume rebound would be pure operating leverage at a 57% EBITDA margin. Downside: the market may be under-pricing that the single line carrying the growth narrative — event contracts at >6x growth — faces the Ninth Circuit having already ruled against federal preemption (Aug 2026), with the CFTC now suing ~10 states (Utah added the same day as earnings); one adverse state injunction against Robinhood's Kalshi-partnered product would hit the fastest-growing revenue stream directly.
The one thing to watch
The variable to watch is not crypto price — it's the take-rate-adjusted mix: HOOD's Q3 proves the equity/options/Gold engine can produce record revenue with crypto at -55%, so the stock's true sensitivity has quietly rotated from bitcoin beta to prediction-market litigation outcomes; watch state injunction filings and CFTC docket, not the BTC chart.
Key evidence (7)
- Q3 2026 (reported 10/27/26, company IR/8-K): record revenue $1.42B +12% YoY (~$10M below consensus), adj. EPS $0.60 vs $0.55 consensus, GAAP net income $476M -14% YoY, adj. EBITDA record $808M at 57% margin [T1 content, retrieved via IR site tagged T4]
- Q3 2026 revenue mix: options $399M +31%, event contracts $173M >6x, net interest $415M -9%, crypto $120M -55%, equities $121M +41%, other +61% [IR release]
- Gold subscribers record 5.2M, +34% YoY, ~40% attach on new customers; FY26 opex+SBC guide trimmed $25M at top end to $2.675-2.75B [IR release/call]
- Price context (10/27/26): -37% below 52w high, max drawdown -55.7%, -31% 1y vs COIN -50%, SOFI -49%, IBKR +20% — selloff concentrated in crypto/retail-momentum complex [computed from price history]
- Prediction-market legal status: Ninth Circuit ruled against Kalshi preemption Aug 2026; CFTC suing ~10 states to preserve federal jurisdiction, Utah complaint filed 10/27/26; Robinhood is a CFTC-registered FCM partnering with DCMs [T1 CFTC materials / T4 trackers — the tracker citations are lower-tier]
- Valuation: ~35-36x forward P/E, ~41x trailing; 2026/2027 consensus EPS ~$2.54/$3.42 but reportedly only 7 analysts contributing — thin, low-confidence consensus [T4, unverified against T2/T3]
- Management on Q3 call: October equities, options, and crypto activity each within ~±5% of Q3 levels — early stabilization signal [earnings transcript]
Catalysts and risks
Catalysts
- Q4 2026 earnings ~Feb 8, 2027 (consensus EPS ~$0.63, revenue ~$1.56B) — first clean read on whether October stabilization held
- State-court rulings or injunctions on Kalshi/event contracts; any decision in the CFTC's suits against the ~10 states (including Utah, filed 10/27/26)
- Crypto market direction and retail volume data into year-end (COIN earnings as a cross-check)
- Post-earnings analyst estimate revisions for 2026/2027 — currently a verified gap in the evidence
- Monthly operating metrics (fundamental customers, net deposits — $16B in Q3) and Gold subscriber trajectory
Risks
- Prediction-market legal loss: state injunction or adverse appellate ruling impairs the ~$692M annualized event-contract line
- Crypto downturn proves structural (institutional/ETF share shift) rather than cyclical, keeping the -55% trajectory
- Rate declines further compress net interest income (-9% already) and Gold/securities-lending economics
- Thin consensus (reportedly 7 analysts) means the $3.42 2027 EPS anchor is fragile and revisions could gap either way
- 3.9 beta and 71% 1y realized vol: macro risk-off hits HOOD disproportionately; current 8th-percentile vol may precede a sharp move in either direction
What to watch
- Court dockets: Kalshi/Robinhood state cases and CFTC vs. states — injunction filings matter more than headlines
- Monthly Robinhood operating metrics and any intra-quarter crypto volume disclosures
- 2027 EPS revision direction once post-earnings analyst updates publish (currently unverified — the key open data gap)
- Bitcoin price/volatility and COIN's retail transaction revenue as the cyclicality cross-check
- Net interest income sensitivity to the rate path and securities-lending demand
Market snapshot when the call was made 2026-10-27
Price
| Return 1w | -3.8% |
| Return 1m | -22.2% |
| Return 3m | +0.1% |
| Return 6m | +10.6% |
| Return 1y | -30.9% |
| From 52-week high | -36.9% |
| Realized vol, 20d | 49.1% |
| SPY 3m / 1y | +3.3% / +13.9% |
| QQQ 3m / 1y | +5.4% / +16.6% |
Technicals
HOOD technicals as of 2026-10-27: last close $94.56; 20d SMA 104.37 (bearish); 50d SMA 108.78; 12d EMA 99.52; 26d EMA 104.13; RSI 14 32.2 (balanced); 20d vol 48.4%; volume x1.2 vs 20d avg
Next earnings: 2027-02-08 AMC
Sources (26 · T1 = primary filings)
- T4https://investors.robinhood.com/static-files/c2119020-41a1-4008-b9ae-db1b9fd6fb5e
- T4https://investors.robinhood.com/static-files/fd90f575-5b4c-4cde-a16d-d114c920fb6a
- T4https://investors.robinhood.com/financials/sec-filings
- T4https://investors.robinhood.com/static-files/f44ea493-9c52-4744-9671-7720e1ac7b2f
- T4https://www.stocktitan.net/articles/robinhood-q3-2026-earnings-prediction-markets-crypto
- T4https://investors.robinhood.com/static-files/f5aa8c24-cd37-4a94-9169-cd04759e02a1
- T4https://robinhood.com/us/en/stocks/HOOD/
- T4https://finance.yahoo.com/quote/HOOD/earnings/HOOD-Q3-2026-earnings_call-718711.html
- T4https://investors.robinhood.com/news-releases/news-release-details/robinhood-reports-third-quarter-2026-result…
- T4https://investors.robinhood.com/node/16911/pdf
- T4https://investors.robinhood.com/static-files/097e3ef5-f1a9-4981-b224-c58d9da67159
- T4https://investors.robinhood.com/static-files/5e9071d7-d4c2-46ac-b57f-224a14e418ee
- T4https://finance.yahoo.com/markets/stocks/articles/robinhood-q3-highlights-trump-accounts-202908506.html
- T3https://www.cnbc.com/2026/10/27/robinhood-hood-q3-2026-earnings.html
- T4https://finance.yahoo.com/markets/stocks/articles/hood-stock-drops-5-hours-224232429.html
- T1https://www.cftc.gov/PressRoom/PressReleases/9220-26
- T1https://www.cftc.gov/media/14271/OGC_KentuckyComplaint062326/download
- T4https://www.dlapiper.com/en/insights/publications/2026/09/legal-status-at-odds-tracking-developments-in-predic…
- T1https://www.cftc.gov/PressRoom/PressReleases/9251-26
- T4https://www.politico.com/news/2026/10/27/cftc-expands-prediction-market-clash-to-gop-led-utah-01136779
- T1https://www.cftc.gov/media/14061/OGC_RhodeIslandComplaint052826/download
- T1https://www.cftc.gov/PressRoom/PressReleases/9230-26
- T4https://www.covers.com/industry/cftc-sues-utah-after-state-moves-to-block-kalshi-oct-27-2026
- T4https://investors.robinhood.com/press-releases
- T4https://investors.robinhood.com/events/event-details/robinhood-q3-2026-earnings
- T4https://investors.robinhood.com/
Want a fresh look at HOOD, or another name?
Queue a new deep-research run. Published to the feed when done.
Automated research opinion, published as-is on Oct 28, 2026. Not personalised advice. Figures use end-of-day closes.