Real story, mostly priced in.
Thesis
Bull case
The structural case is real and broader than AI: global grid investment, electrification, and dispatchable power scarcity give GEV a sold-out order book into 2030 with pricing power, a production ramp that could roughly double gas output by 2030, and FCF already at a $12B run-rate. If slot reservations convert cleanly and the January print shows margins holding in the 12-14% band while backlog grows, the stock re-rates back toward the highs and the 19% drawdown looks like a gift. Only ~20% AI exposure means the franchise survives an AI capex pause.
Bear case
At 45x forward earnings with EPS estimates drifting down and 2027 consensus below 2026, the market is paying for perfection after the easy margin-inflection gains are done (operating margin already went 1.3%→3.6%). Q2 proved order growth can be margin-dilutive; Wind remains a live value-destroyer (Vineyard dispute); tariffs and supply chain bite; and the entire complex trades on AI-capex sentiment that can reverse on a single hyperscaler guidance cut. GLJ's $470 target is aggressive but illustrates the downside if the multiple normalizes to industrial peers — even a moderate derating to 30x on 2027 consensus EPS of ~$24.84 implies ~$745, roughly 23% downside (caveat: that 2027 EPS figure is T4-sourced and internally inconsistent with quarterly run-rates, so treat the arithmetic as illustrative rather than precise). On 2026 consensus EPS of ~$30.80, the same 30x derating implies only ~$925, ~3-4% downside — the asymmetry depends heavily on which earnings base the market ultimately prices.
What would change our mind
- Bearish thesis invalidated if: Q4 print shows EBITDA margin at/above 14% with slot-to-firm conversion accelerating and 2027 guidance above $52.7B revenue consensus — that combination justifies the multiple
- Bullish thesis invalidated if: 2027 guidance implies flat-to-down EPS, slot reservations stall below ~120 GW total under contract, or a major hyperscaler cuts 2027 capex — that breaks the conversion/pricing assumption the multiple rests on
- Falsifiable marker: if FY27 EPS estimates hold near $25 while the stock trades materially lower (e.g., below ~$820, an arbitrary ~15% drawdown marker rather than a documented technical level), that is multiple compression, not fundamental deterioration — a potential entry; if estimates are cut alongside, the drawdown is fundamental
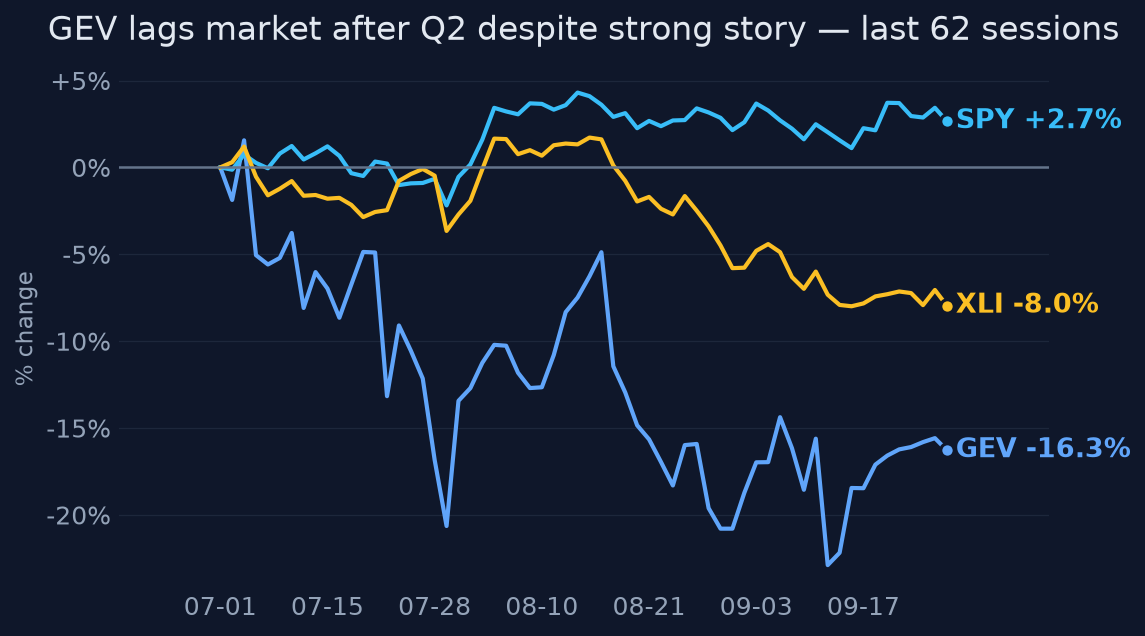
Since publication vs SPY · closed horizons are frozen
The full research everything the view rests on
Direct answer to the question asked
Where the edge would come from
What the price assumes
At ~45x forward earnings, the price assumes: (1) slot reservations convert to firm orders at healthy margins, (2) the production ramp to 24 GW by 2028 executes without major supply-chain or tariff damage, (3) AI/data-center capex remains robust through 2027, and (4) Wind stops destroying value. Notably, consensus EPS of ~$30.80 for 2026 falling to ~$24.84 for 2027 (T4 sources, internally inconsistent — likely GAAP/adjusted mixing) suggests the market already expects some earnings normalization even as revenue grows to ~$52.7B.
Why the market may be wrong
Upside surprise: only ~20% of contracted gas load is data centers — even if AI capex stumbles, 80% of demand is utility-driven and structural, so an AI-sentiment selloff could prove to be a buying opportunity on a business that doesn't actually depend on AI. Downside surprise: 63 GW of the 116 GW 'under contract' is slot reservations, not firm backlog — if conversion rates or pricing disappoint, or if the Q2 margin dynamic (order surge pressuring near-term EPS) repeats, a 45x multiple has far to fall (GLJ's $470 target is the extreme expression of this).
The one thing to watch
The variable to watch is not data-center demand headlines — it's the conversion of the 63 GW of slot reservations into firm backlog (currently 53 GW) and the margin at which they convert. GEV is only ~20% an AI story; the Q2 EPS miss while raising guidance showed that rapid order growth itself is margin-dilutive near-term. If slot-to-firm conversion accelerates with stable pricing, the bear case collapses; if reservations stall or reprice, the 45x multiple is indefensible regardless of how good the demand headlines look.
Key evidence (8)
- Q2 2026 (reported 7/22/26, SEC 8-K [T1]): orders $24.2B (+88% YoY), record $176B backlog, FCF $5.1B quarter / $10B YTD, revenue $11.1B beat, adjusted EPS $2.47 missed ~$3.04-3.17 consensus
- Gas equipment under contract: 116 GW at Q2-end (53 GW firm backlog + 63 GW slot reservations), targeting 125+ GW by YE2026; production ramp 20 GW/yr (2026) → 24 GW (2028) → 30 GW (2030) [T1/T4 company releases]
- Data centers ~20% of contracted gas load; ~80% utility/IPP/industrial; Electrification data-center orders >$5B YTD, >2x all of 2025 [T4 company commentary]
- Siemens Energy corroboration: ~70 GW gas backlog, 3+ year lead times, capacity expanding [T4, industry press]; Reuters (Mar 2026): US data centers up to 17% of US power by 2030 [T2]
- 2026 guidance raised: revenue $45.5-46.5B, FCF $11.5-12.5B, EBITDA margin held 12-14% [T1 press release]
- Valuation: ~$256B market cap, ~45x forward P/E on $30.80 consensus 2026 EPS [T4 — weakly sourced, treat as approximate]; 2025 GAAP EPS $17.69 on $38.1B revenue [T1 SEC XBRL]
- Price action: +57% 1yr but -19% from 52w high, -14% over 3 months, bearish short-term trend, 45% realized vol [market data]
- Bear markers: GLJ Research sell rating with $470 target; analyst targets range $470-$1,450; Reuters-covered Vineyard Wind dispute (GEV sought to exit $4.5B project over $300M+ claimed costs) [T2/T4]
Catalysts and risks
Catalysts
- Q4 2026 earnings, ~Jan 26, 2027 (EPS consensus ~$6.49, revenue ~$14.0B) — first clean read on H2 margins and 2027 guidance
- Year-end 2026 disclosure of total GW under contract vs the 125 GW target
- Hyperscaler 2027 capex guidance (Q4 earnings season, Jan-Feb 2027)
- Wind segment developments: Vineyard Wind resolution, any further contract exits or charges
- Slot reservation → firm order conversion announcements
- Any capacity expansion acceleration beyond the 24 GW 2028 plan
Risks
- Valuation derating: 45x forward leaves no room for an EPS miss; consensus EPS data itself is unreliable (GAAP/adjusted mixing in T4 sources)
- AI-capex sentiment reversal hitting the whole electrification complex regardless of GEV's actual 20% AI exposure
- Wind segment losses and contract disputes (Vineyard Wind precedent)
- Tariff and supply-chain cost pressure on margins
- Slot reservations (63 GW) failing to convert to firm orders at expected pricing
- Execution risk on an aggressive production ramp (20→30 GW)
- High volatility (45-52% annualized) means 3-6 month outcomes are noisy even if the long-term thesis is right
What to watch
- Slot reservation vs firm backlog split in the Q4 release (the single most informative number)
- Adjusted EBITDA margin trajectory vs the 12-14% band — watch whether new-order dilution persists
- 2027 guidance vs ~$52.7B revenue / ~$24.84 EPS consensus
- Hyperscaler capex commentary in January earnings season
- Wind segment charges and the Vineyard Wind outcome
- Siemens Energy and Mitsubishi commentary as a read-through on industry pricing and lead times
- Whether the stock holds the ~$820-850 zone on further weakness — a round-number/psychological area we are watching, not an evidence-backed technical support level (the evidence bundle contains no support/resistance analysis; documented levels are only the 20d SMA ~$936 and 50d SMA ~$968)
Market snapshot when the call was made 2026-09-29
Price
| Return 1w | +0.4% |
| Return 1m | -0.4% |
| Return 3m | -13.8% |
| Return 6m | +11.4% |
| Return 1y | +56.7% |
| From 52-week high | -19.2% |
| Realized vol, 20d | 45.4% |
| SPY 3m / 1y | +3.3% / +16.4% |
| QQQ 3m / 1y | +0.2% / +23.8% |
Technicals
GEV technicals as of 2026-09-29: last close $962.49; 20d SMA 936.45 (bearish); 50d SMA 968.41; 12d EMA 946.49; 26d EMA 949.46; RSI 14 52.3 (balanced); 20d vol 44.3%; volume x0.7 vs 20d avg
Next earnings: 2027-01-26 BMO
Verifier notes REVISE · opinion revised once
Unsupported claims
- what_to_watch cites 'the ~$820-850 zone (prior consolidation)' as a technical support level — the evidence bundle contains no support/resistance or consolidation-zone analysis (only 20d SMA $936, 50d SMA $968, RSI, volatility). The 'prior consolidation' characterization is fabricated technical detail. The same $820 level is reused in invalidation_conditions, where it is acceptable as an arbitrary falsifiable marker but should not be presented as a documented technical level.
Internal inconsistencies
- bear_case states 'even a derating to 30x on $31 EPS is ~23% downside' — the arithmetic is wrong: 30 × $31 = $930, which is only ~3% below the $962 price, not 23%. The ~23% figure only works on 2027 consensus EPS of ~$24.84 (30 × $24.84 ≈ $745, ≈ -22.5% from $962). As written, the quantified bear-case downside is materially misstated.
Corrections applied
- Fix the bear-case derating math: either write 'a derating to 30x on 2027 consensus EPS of ~$24.84 implies ~$745, roughly 23% downside' or, if keeping $31 EPS, state the correct ~3% downside. Note the opinion elsewhere flags the $24.84 2027 figure as T4/internally inconsistent, so the correction should carry that caveat.
- Remove '(prior consolidation)' from the $820-850 watch level, or reframe it as a round-number/psychological zone the analyst is watching rather than an evidence-backed technical level — no consolidation data exists in the bundle.
Sources (24 · T1 = primary filings)
- T4https://www.utilitydive.com/news/siemens-gas-turbine-backlog-nears-70-gw-as-company-expands-manufacturing/8273…
- T4https://assets.siemens-energy.com/dam/1e0dc454-06b5-46d5-92d8-b41000da6797/2026-03-16---Oxcap-Power-Day_presen…
- T4https://finance.yahoo.com/quote/ENR.F/earnings/ENR.F-Q3-2026-earnings_call-553306.html
- T4https://www.investing.com/news/transcripts/earnings-call-transcript-siemens-energy-posts-record-q3-2026-result…
- T4https://www.investing.com/news/company-news/siemens-energy-q3-fy26-slides-record-quarter-gamesa-turns-profit-9…
- T4https://pgjonline.com/news/2026/september/dash-for-small-gas-turbines-set-to-impact-data-center-costs
- T4https://www.gevernova.com/gas-power
- T4https://energynewsbeat.co/electrical-generation/siemens-gas-turbine-backlog-nears-70-gw-as-company-expands-man…
- T1https://www.sec.gov/Archives/edgar/data/1996810/000199681026000147/gevpressrelease2q26.htm
- T4https://www.gevernova.com/news/press-releases/ge-vernova-reports-first-quarter-2026-financial
- T4https://www.gevernova.com/sites/default/files/gev_webcast_pressrelease_04222026.pdf
- T4https://www.turbomachinerymag.com/view/ge-vernova-gas-turbine-backlog-hits-116-gw-as-power-orders-more-than-do…
- T4https://finance.yahoo.com/energy/articles/176-billion-backlog-ge-vernova-020300714.html
- T4https://www.gevernova.com/sites/default/files/gev_webcast_pressrelease_07222026.pdf
- T4https://www.power-eng.com/gas/turbines/data-centers-drive-record-surge-in-ge-vernova-power-equipment-orders-as…
- T4https://www.gevernova.com/news/taxonomy/term/9606?page=1
- T2https://www.reuters.com/markets/companies/GEV.N/
- T2https://www.reuters.com/company/ge-vernova-inc/
- T4https://www.ad-hoc-news.de/boerse/news/nebenwerte/ge-vernova-stock-ends-the-day-0-61-percent-lower-at-usd-944-…
- T4https://www.marketbeat.com/stocks/NYSE/GEV/news/
- T4https://www.investing.com/news/stock-market-news/ge-vernova-stock-outlook-beyond-the-data-center-trade-93CH-49…
- T4https://finance.yahoo.com/markets/stocks/articles/ge-vernova-stock-down-20-160500650.html
- T4https://finance.yahoo.com/markets/stocks/articles/wall-street-cant-agree-ge-150501997.html
- T4https://www.ad-hoc-news.de/boerse/news/corporate-news/ge-vernova-stock-heads-into-the-open-after-a-20-3-percen…
Want a fresh look at GEV, or another name?
Queue a new deep-research run. Published to the feed when done.
Automated research opinion, published as-is on Sep 29, 2026. Not personalised advice. Figures use end-of-day closes.