Yes — priced for decline it hasn't shown.
Thesis
Bull case
The market is pricing terminal decline on a business growing revenue 13% with 36%+ operating margins, a ~10% FCF yield, and a buyback retiring high-single-digit percentages of shares annually. AI-first ARR is scaling 3x y/y, there is zero hard evidence of seat losses, and the new CEO's first FY27 guide is more likely to be conservative-and-beatable than disastrous. Any FY27 framework showing ≥8-9% ARR growth re-rates the stock toward 12-13x ($290-340) on already-raised estimates; buyback provides a floor near current levels.
Bear case
The freemium pivot, absence of price increases, and simultaneous CEO/CFO exits read as defensive moves by insiders who see the competitive wall coming. Wells Fargo's math — Q4 requiring new ARR to roughly double q/q, FY27 new-ARR growth going negative — if validated means total ARR growth falls toward 7% and below, AI compute costs compress margins without pricing offsets, and Canva plus free AI tools keep eroding the entry tier that feeds the professional funnel. In that case 10x earnings is not cheap — estimates get cut and the multiple stays compressed (Goldman's $200 target). A new CEO's first guide is the classic moment to reset the bar lower.
What would change our mind
- FY27 initial guidance implies total ARR growth below ~7-8% or explicitly negative new-ARR growth — confirms the Wells Fargo thesis and the value-trap read
- Disclosure of Creative Cloud seat declines, elevated churn, or subscription revenue deceleration below ~8% y/y
- AI-first ARR growth stalling below ~50% y/y, removing the 'AI as supplement' evidence
- Buyback pace materially slowing, removing the EPS-compounding floor
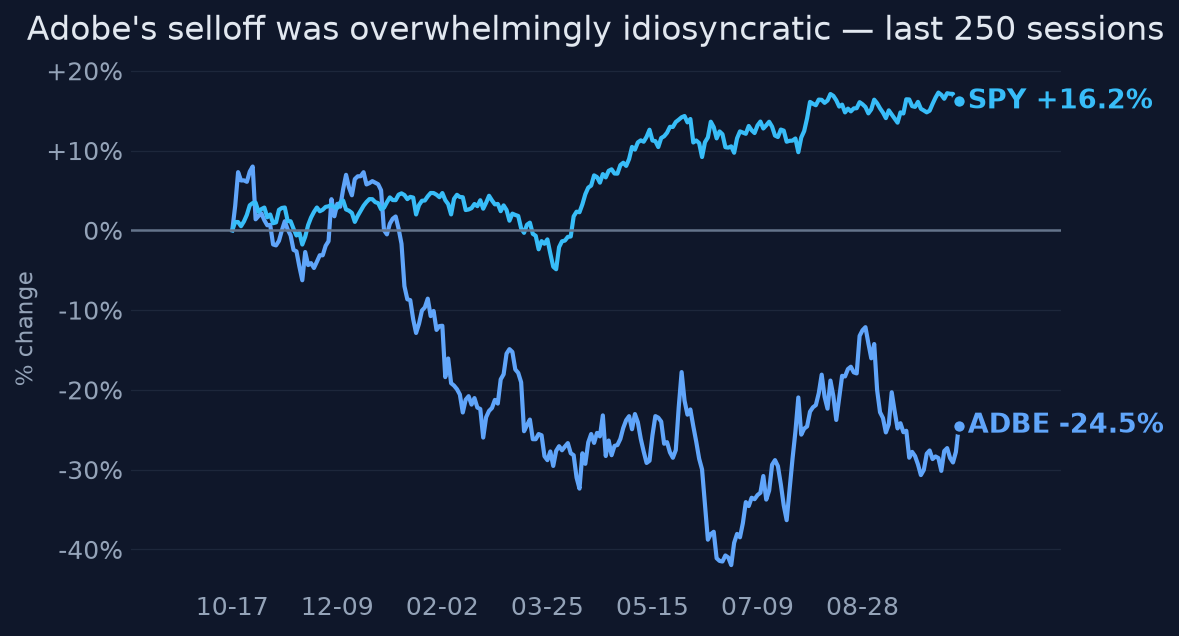
Since publication vs SPY · closed horizons are frozen
The full research everything the view rests on
Direct answer to the question asked
Where the edge would come from
What the price assumes
Consensus FY27 already embeds deceleration (~$29B revenue, +9%; ~$27.7 EPS, +13%), and the ~9.4-10x forward P/E (vs 15-23x historically) implies the market prices roughly zero terminal growth — i.e., that AI-native competition eventually compresses the creative franchise. Wells Fargo models negative new-ARR growth in FY27 and ~7% total ARR growth.
Why the market may be wrong
The bear case is a forecast, not an observation: there is no public evidence of Creative Cloud seat losses, churn spikes, or revenue deterioration from Canva/OpenAI/Google — Creative and Document Cloud growth actually accelerated to 13-14%. The two most-cited negative catalysts are weak: the HSBC downgrade leaned partly on an 'ArtCraft open-source alternatives' report sourced only to T4 material, and Wells Fargo's 'negative FY27 new ARR' is a model, not data. Meanwhile AI monetization disclosures (AI-first ARR tripling, Firefly ~$300M, AI-influenced ARR >$5B) show AI adding revenue rather than displacing it, and the market is ignoring that a ~$25B buyback at a ~$96B market cap mechanically compounds EPS even in a low-growth scenario.
The one thing to watch
The debate everyone is having — 'is AI good or bad for Adobe?' — is the wrong variable at this price. At ~10x forward earnings with a buyback retiring ~7-9% of shares per year, Adobe doesn't need to win the AI war to generate double-digit per-share returns; it only needs FY27 new-ARR growth to be non-negative. The variable to watch is not AI sentiment or Canva headlines but the single FY27 new-ARR ramp number in the Dec 9 guidance — that one data point decides whether this is value or value trap.
Key evidence (9)
- Q3 FY26 (reported Sept 10, 2026, T1 SEC): revenue $6.76B +13%, non-GAAP EPS $6.13 beat, FY26 guidance raised to $26.58-26.63B / $24.45-24.50 EPS; total ARR $27.5B +11.2%
- Forward P/E ~9.4-10.2x vs 15.2x (2025), 19.5x (2024), 20-23x (2021-22); market cap ~$96B
- AI monetization disclosures (T1/T4): AI-first ARR >$650M exiting Q3 FY26 (+150% y/y); Firefly ARR ~$300M Q2 FY26; Acrobat AI Assistant ~3x y/y; AI-influenced ARR >$5B exiting Q3 FY25
- Buyback: April 2026 authorization ~$25B ($24.55B remaining after Q3); ~26.1M shares repurchased through Q3 FY26; diluted share guide ~395M
- Estimate revisions net positive: 26 up vs 3 down FY26 EPS revisions over 30 days; FY26/FY27 consensus up 0.2%/0.5% over 90 days
- Wells Fargo double-downgrade to Underweight Oct 12, 2026, target $225 (from $270): models negative FY27 new-ARR growth, ~7% total ARR growth, cites no price increase; HSBC to Hold ($267), Goldman Sell ($200)
- CEO transition confirmed via SEC 8-K: Narayen steps down, Anil Chakravarthy becomes CEO Dec 1, 2026; CFO Durn resigned June 15, 2026, interim CFO Steven Day
- Price action: -25% 1y vs SPY +16.5%, max drawdown -46.3%, 60d correlation to SPY 0.08 — 99% idiosyncratic
- No public evidence found of pro seat losses, churn spikes, or Creative Cloud revenue decline from AI-native competitors; Canva ~$4B ARR growing 43% but displacement not demonstrated
Catalysts and risks
Catalysts
- Dec 9, 2026: Q4 FY26 earnings + initial FY27 guidance (revenue, EPS, and critically total/new ARR growth) — the decisive event
- Dec 1, 2026: Anil Chakravarthy takes over as CEO — strategy and guidance-posture signals
- Quarterly AI-first ARR and Firefly ARR disclosures — continuation of >100% growth would undermine the disruption narrative
- Buyback pace disclosures (~9-10M shares/quarter currently)
- Any evidence (or absence) of Creative Cloud seat/pricing pressure from Canva, OpenAI, Google
Risks
- FY27 guidance reset by incoming CEO/interim CFO — 'kitchen sink' first guide is a common playbook
- Wells Fargo's negative-FY27-new-ARR thesis proves correct, confirming deceleration below consensus >8% ARR growth
- AI compute costs without price increases compress margins
- Canva's enterprise segment (+100% y/y) migrates upmarket faster than expected
- Freemium strategy cannibalizes paid entry tiers without sufficient conversion
- Multiple stays compressed even on decent results — value traps can persist for years
What to watch
- FY27 total ARR growth target and implied new-ARR ramp in the Dec 9 guide — the single decisive number
- Whether the new CEO signals pricing action (any price increase would directly counter the bear case)
- AI-first ARR trajectory vs the $650M Q3 base and Firefly sequential growth
- Share count: diluted count trajectory vs the ~395M guide (buyback execution)
- Canva enterprise traction data and any independent creative-software share estimates
- Analyst estimate revisions in the 30 days post-guidance — whether FY27 EPS ~$27.7 holds
Market snapshot when the call was made 2026-10-15
Price
| Return 1w | +4.4% |
| Return 1m | +0.5% |
| Return 3m | +6.1% |
| Return 6m | +1.4% |
| Return 1y | -25.1% |
| From 52-week high | -30.1% |
| Realized vol, 20d | 34.1% |
| SPY 3m / 1y | +3.8% / +16.5% |
| QQQ 3m / 1y | +4.7% / +21.7% |
Technicals
ADBE technicals as of 2026-10-15: last close $251.67; 20d SMA 239.73 (bearish); 50d SMA 256.84; 12d EMA 241.44; 26d EMA 244.71; RSI 14 64.4 (balanced); 20d vol 33.7%; volume x1.4 vs 20d avg
Sources (36 · T1 = primary filings)
- T4https://www.adobe.com/cc-shared/assets/investor-relations/pdfs/adbe-q3fy25-transcript.pdf
- T4https://www.zacks.com/stock/news/2988442/adobe-q3-earnings-call-centers-on-agentic-ai-and-freemium
- T4https://www.adobe.com/cc-shared/assets/investor-relations/pdfs/adbe-q4fy25-transcript.pdf
- T4https://www.adobe.com/cc-shared/assets/investor-relations/pdfs/21306202/c545hjdryueyw34.pdf
- T4https://www.zacks.com/stock/news/2988550/adbe-q3-earnings-beat-estimates-revenues-rise-on-subscription-growth
- T4https://www.adobe.com/cc-shared/assets/investor-relations/pdfs/11606202/a5543arefgt.pdf
- T4https://www.adobe.com/cc-shared/assets/investor-relations/pdfs/21306202/ay45th643t5y46.pdf
- T4https://www.adobe.com/cc-shared/assets/investor-relations/pdfs/01215202/c54trgt53r4aw.pdf
- T4https://finance.yahoo.com/markets/stocks/articles/adobe-free-user-bet-shows-161700092.html
- T4https://finance.yahoo.com/markets/stocks/articles/adobe-being-punished-creative-cannibalization-124546089.html
- T4https://finance.yahoo.com/markets/stocks/articles/adobe-keeps-cratering-one-wall-111505335.html
- T1https://www.sec.gov/Archives/edgar/data/796343/000079634326000109/adbeex991q226.htm
- T4https://vcpscanner.com/stock/adbe/price-target
- T1https://www.sec.gov/Archives/edgar/data/796343/000079634326000147/adbeex991q326.htm
- T4https://finance.yahoo.com/markets/stocks/articles/analyst-just-downgraded-adobe-stock-211145246.html
- T4https://alcapitaladvisory.com/research/equities/adbe.html
- T4https://www.adobe.com/cc-shared/assets/investor-relations/pdfs/01906202/au56y4ter.pdf
- T4https://www.adobe.com/cc-shared/assets/investor-relations/pdfs/01906202/c6yetrerew.pdf
- T1https://www.sec.gov/Archives/edgar/data/796343/000079634326000048/adbeex991q126.htm
- T4https://www.stocktitan.net/sec-filings/ADBE/8-k.html
- T4https://www.stocktitan.net/sec-filings/ADBE/8-k-adobe-inc-reports-material-event-5a6954dc3846.html
- T1https://www.sec.gov/Archives/edgar/data/796343/000079634326000144/adbeex9918-k9826.htm
- T1https://www.sec.gov/Archives/edgar/data/796343/000079634326000048/adbeex992q126.htm
- T4https://sacra.com/c/canva/
- T4https://techcrunch.com/2026/02/18/canva-gets-to-4b-in-revenue-as-llm-referral-traffic-rises/
- T4https://builtin.com/company/canva-1/faq/stability-growth
- T4https://sacra.com/research/canva-at-4b-arr-growing-43-yoy/
- T4https://valueforstartups.in/canva
- T4https://www.beyond-print.net/canva-is-the-new-gatekeeper-in-online-printing-who-is-actually-still-making-money…
- T4https://finance.yahoo.com/markets/stocks/articles/oracle-adobe-earnings-report-reveal-120515420.html
- T4https://www.adobe.com/investor-relations.html
- T4https://www.cmelitegroup.com/trends-and-insights/adobe-earnings-date-estimates-and-how-precisely-the-company-i…
- T4https://markets.businessinsider.com/stocks/adbe-stock
- T4https://longtermpick.com/p/adobe-analysis-2026
- T4https://finance.yahoo.com/markets/stocks/articles/analysts-punting-calls-next-quarter-182000400.html
- T4https://intickers.com/reports/adbe/
Want a fresh look at ADBE, or another name?
Queue a new deep-research run. Published to the feed when done.
Automated research opinion, published as-is on Oct 16, 2026. Not personalised advice. Figures use end-of-day closes.