Still mostly beta.
Thesis
Bull case
If CCIP migrations are real (the T1 Wyoming deal plus claimed Q2 >$7B migration) and revenue follows adoption with a lag, fees could inflect upward over the next 3-6 months, converting narrative into fundamentals. In that case LINK at ~214x FDV/revenue has room to rerate multiple times higher if enterprise/RWA usage actually prices through, and the Reserve's accumulation plus a 45M-LINK staking pool progressively removes float.
Bear case
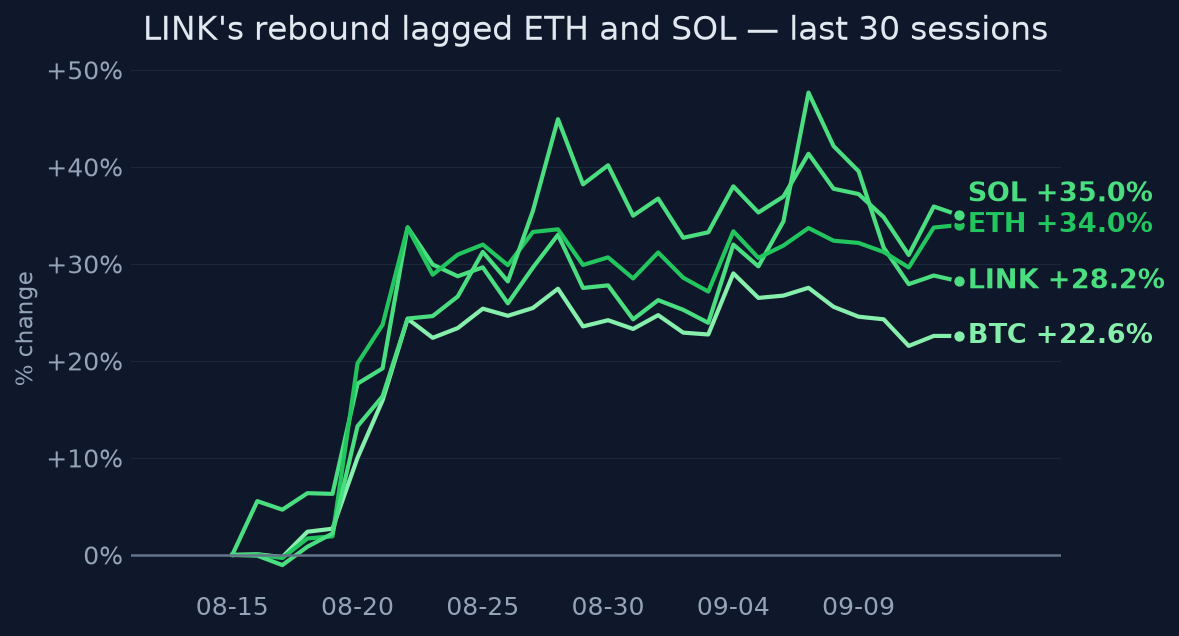
The rally happened while fees fell 21% and revenue fell 23%, so the price rose *against* the usage data — pure narrative plus beta. With no burn, no fee switch to holders, and reserve accumulation under 1% of market cap, token-level value capture is structural thinness at a valuation that already prices success. LINK also underperformed ETH and SOL during the tape, so even beta has leaked; a market reversal would hit LINK's 1.26 BTC-beta hard, and the unlock-schedule conflict (7%/year release vs claimed full vesting) is an unsized supply overhang.
What would change our mind
- Fees and revenue must stop falling: two consecutive months of rising protocol fees would begin to validate usage thesis
- The $15B migration claim must be confirmed at T2/T3; if it was a market-rumor artifact, the idiosyncratic catalyst shrinks to Wyoming-scale
- LINK must start outperforming its ETH/SOL peer set rather than merely catching BTC beta — continued underperformance confirms beta-only
- Reserve quarterly additions must scale meaningfully above the current ~1.4M LINK/quarter pace to represent actual float absorption
- Unlock-schedule disclosure must be resolved; an uncontrolled release schedule of 7%/year would be a persistent supply drag
Since publication vs BTC · closed horizons are frozen
The full research everything the view rests on
Direct answer to the question asked
Where the edge would come from
What the price assumes
The current price (~214x FDV-to-annualized-revenue, 0.67% annualized fees-to-market-cap) embeds a strong expectation that CCIP and RWA/tokenization integrations convert into material revenue and reserve accumulation over the next several years, not just beta participation.
Why the market may be wrong
If the CCIP adoption wins are as real as the T1 Wyoming source and Q2 review claim, then per-usage revenue should eventually inflect; ordering flow from announcements to actual fees could validate the rerating. But right now the observable data contradicts the narrative — fees fell during the rally, so the burden of proof sits on future fee conversion, not current usage.
The one thing to watch
The one variable to watch is not CCIP migration headlines but monetized usage: until DefiLlama's Chainlink fee series stops falling, every adoption announcement is a marketing event, and the rebound in price was bought, not earned.
Key evidence (12)
- Fees $4.7M/30d, down 20.9% vs prior 30d; revenue $4.4M/30d, down 23.1% (DefiLlama via get_crypto_fundamentals, 2026-09-13)
- TVL $1.75B, -2.4% over 30d but +47% over 90d (DefiLlama, 2026-09-13) — medium-term growth stalled during the rally window
- 1-month returns: LINK +29.5%, BTC +21.7%, ETH +33.7%, SOL +33.5%; LINK underperformed ETH/SOL and beat BTC by only ~7.7pts (quant tool, CoinGecko, 2026-09-13)
- LINK still -54% below 52w high and -78% below ATH; 1m gain is a 1.8-sigma move vs its own history (quant tool, 2026-09-13)
- 60d beta to BTC 1.26, correlation 0.73, idiosyncratic share ~47% (quant tool, 2026-09-13)
- Wyoming Stable Token Commission adopted CCIP as exclusive cross-chain infra for FRNT, multi-year [T1, PRNewswire]
- Q2 2026 company review claims >$7B in cross-chain value migrated to CCIP in the quarter [T4, company blog]
- BitGo migration of WBTC and future assets to CCIP; ~$15B LayerZero→CCIP migration claim [T4, weakly sourced]
- Bottomline partnership linking CCIP and CRE to SWIFT-adjacent payments, September 2026 [T4]
- FDV/annualized revenue ~214x; annualized fees 0.67% of market cap (DefiLlama ratios, 2026-09-13)
- Chainlink Reserve held ~5.67M LINK by Aug 2026 (~$65M, <0.8% of market cap) [T4 citing reserve.chain.link]
- ETF complex ~$148M cumulative net flow, ~$169M AUM, ~$1.5M in latest week [T4 market data dashboard]
Catalysts and risks
Catalysts
- A sustained monthly reversal in the DefiLlama fee/revenue series (needs >20% month-over-month improvement to contradict the deterioration)
- Completion and confirmation of the BitGo/WBTC and other LayerZero→CCIP migrations with at least T2/T3 sourcing
- Chainlink Reserve accumulation updates (reserve.chain.link) showing material quarter-over-quarter growth
- Further government/institutional CCIP adoptions (state stablecoins, DTCC collateral, SWIFT-adjacent partnerships) that come with usage commitments
- ETF flow scale-up beyond the current ~$148M cumulative figure
- Clarification of the forward discretionary release schedule (7%/year vs 'fully vested' contradiction)
Risks
- Crypto market reversal: 1.26 beta to BTC amplifies drawdowns; LINK was still -54% off its 52w high during the 'rebound'
- No value-accrual mechanism: no burn, no fee switch, staking ~4.3% with limited capacity — token holders capture narrative, not protocol cash flow
- Unresolved supply overhang: sources conflict between fully vested (2024-11) and a 7%/year release schedule, with a recent ~18-19M LINK quarterly unlock (2026-04-04)
- Valuation fragility: ~214x FDV/annualized revenue leaves no cushion if CCIP monetization lags or announcements prove headline-type
- Weak relative strength: LINK trailed ETH and SOL even while rallying — a bad sign for an alt looking for idiosyncratic leadership
- Single weakly-sourced key claim: the '$15B LayerZero→CCIP migration' is T4-only and may materially overstate adoption
What to watch
- DefiLlama monthly fee/revenue direction for Chainlink (the primary falsifiable signal)
- Published Chainlink Reserve balance and quarter-over-quarter LINK additions
- Any verifiable (T2/T3) confirmation or denial of the BitGo/LayerZero migration magnitude
- Chainlink's official circulating-supply page for release schedule clarity
- LINK/ETH and LINK/SOL ratio trends to test for an idiosyncratic edge, not just beta
- Forward pipeline of CCIP institutional integrations (DTCC, SWIFT/Bottomline follow-through)
Market snapshot when the call was made 2026-09-13
Price
| Return 1w | -4.6% |
| Return 1m | +29.4% |
| Return 3m | +44.0% |
| Return 6m | +11.8% |
| Return 1y | -54.3% |
| From 52-week high | -54.3% |
| Realized vol, 20d | 70.4% |
| BTC 3m / 1y | +19.9% / -33.5% |
| ETH 3m / 1y | +50.0% / -46.5% |
| QQQ 3m / 1y | -0.3% / +23.1% |
Technicals
Verifier notes PASS
Unsupported claims
- why_this_matters states holding LINK implies '43-47% idiosyncratic risk' — the evidence gives only one figure: idiosyncratic_share_pct of 47.0% (1 - 0.73²) for LINK vs BTC. The 43% lower bound appears nowhere in the bundle (42% is ETH's idiosyncratic share, not LINK's). Minor, but it is a fabricated number.
Corrections applied
- Change '43-47% idiosyncratic risk' to '~47% idiosyncratic risk' to match the quant tool's idiosyncratic_share_pct of 47.0% for LINK.
Sources (8 · T1 = primary filings)
- T3https://coinmarketcap.com/top-stories/6a87b237d927ed2cfe79a3ac/
- T1https://www.prnewswire.com/news-releases/wyoming-stable-token-commission-migrates-to-chainlink-ccip-for-enhanc…
- T4https://chainlinktoday.com/august-2026-recap-nazarov-visits-white-house-chainlink-powers-coinbase-tokenized-st…
- T3https://coinmarketcap.com/top-stories/6a8806d4d927ed2cfe79f3cb/
- T4https://genfinity.io/2026/08/11/chainlink-johann-eid-dtcc-collateral-appchain-ccip-tokenization/
- T4https://www.binance.com/en/square/post/352206768759090
- T4https://crypto.news/layerzero-chainlink-exodus-15-billion-bridge-migration/
- T4https://en.cryptonomist.ch/2026/08/19/wyoming-chainlink-ccip-adoption/
Want a fresh look at LINK, or another name?
Queue a new deep-research run. Published to the feed when done.
Automated research opinion, published as-is on Sep 13, 2026. Not personalised advice. Figures use end-of-day closes.