Supported, but expectation-rich.
Thesis
Bull case
Real cyclical inflection verified by two independent peers; DHR's relative lag means the catch-up trade has room if Q3 confirms mid-teens bioprocessing orders converting to shipments and FY guidance is raised. Core ex-respiratory growth accelerating, Masimo accretion in 2027, and operating leverage on modest revenue growth could drive estimate revisions upward — the fuel the current rally lacks.
Bear case
Classic trap fingerprint: price +11% in a month while Q3 EPS estimates were cut 7%. Management itself narrowed revenue guidance and cited shipment delays. GAAP margins have compressed three straight years, and 26x forward for 3-4% core growth is not cheap. If Oct 21 is in-line with cautious guidance, the recent premium unwinds — and the 0.83 TMO correlation means any sector-level disappointment compounds the move.
What would change our mind
- Q3 revenue below ~$6.4B or bioprocessing orders decelerate materially from mid-teens
- FY26 core growth guidance cut below 3%
- Adjusted operating margin below ~26% vs the ~26.5% Q3 guide
- Post-earnings estimate revisions continue downward — confirming price/estimate divergence was deterioration, not timing
Since publication vs SPY · closed horizons are frozen
No price data after the entry date yet.
The full research everything the view rests on
Direct answer to the question asked
Where the edge would come from
What the price assumes
At ~26-27x forward EPS and +11% in a month, the market is pricing in a durable bioprocessing recovery and a beat-and-raise on Oct 21. Post-rally analyst targets of $240-255 imply the Street sees the re-rate as mostly complete.
Why the market may be wrong
Two ways. Bullish: the market still anchors on DHR's 2023-25 earnings decline and GAAP margin compression, underestimating operational leverage as core growth ex-respiratory accelerates (4.5% in Q2, +150bp). Bearish: the 'cheap vs 5y average P/E' framing ignores that the average is COVID-inflated; for HSD EPS growth, 26x forward already discounts much of the recovery, and the Q3 estimate cut suggests fundamentals haven't yet matched price.
The one thing to watch
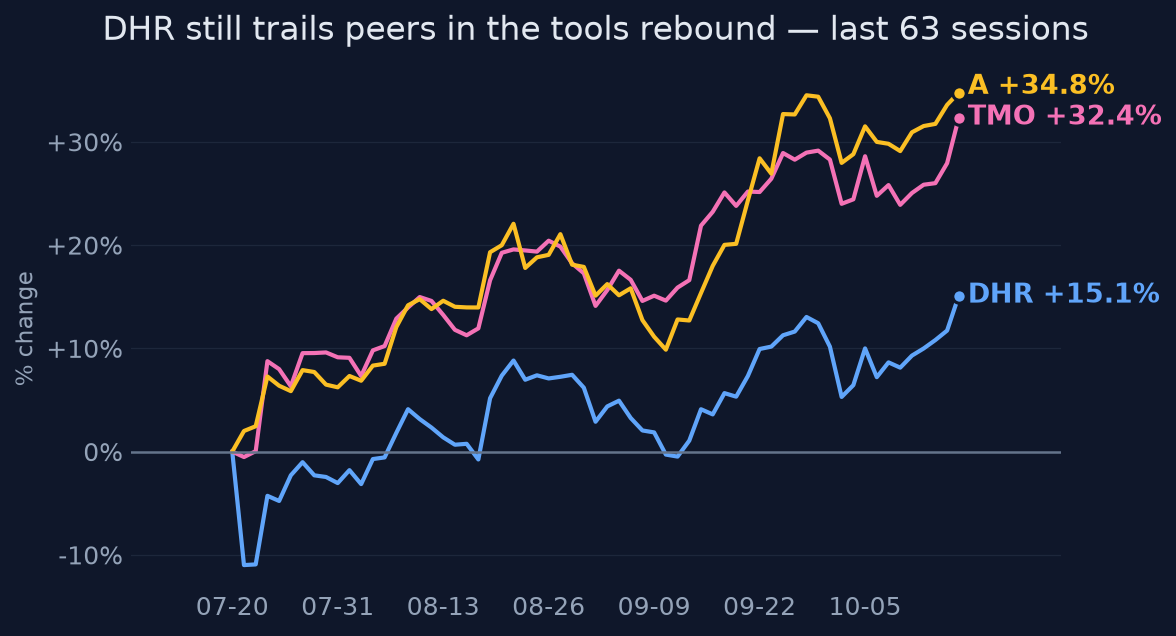
DHR isn't leading this move — it's the laggard in a sector re-rating (0.83 correlation with TMO, trailing TMO by ~17 pts over 3m), so the correct variable to watch isn't DHR's own momentum but whether bioprocessing orders convert to shipped revenue on Oct 21; if they do, DHR's catch-up has room, if not, it unwinds with the sector it mimics.
Key evidence (8)
- Q2'26 (Jul 21): revenue $6.26B +5.5% vs ~$6.12B est; adj EPS $1.94 vs $1.85 est [T1/T2 Reuters]
- Core revenue ex-respiratory +4.5% in Q2, a 150bp acceleration; FY26 adj EPS guidance raised to $8.45-8.60 [T1/T2]
- FY26 core revenue guidance narrowed to 3-4% from 3-6%; management flagged bioprocessing shipment delays [T2 Reuters]
- Q3'26 consensus EPS cut ~7.3% over 90 days ($2.07 → $1.92) — divergence from +11% 1m price [T4, unresolved decomposition]
- Sector corroboration: TMO raised FY organic growth to ~4% with strong bioproduction; Agilent raised FY revenue/margin/EPS [T1]; TMO +30.8%, A +33.5% 3m vs DHR +13.6%
- Masimo: $9.9B EV, ~18x 2027 EBITDA (~15x w/synergies), +$0.15-0.20 EPS accretion year one, ~$0.70 by year five [T1]
- Valuation: forward P/E ~26x vs trailing ~41x; GAAP operating margin compressed 25.3% → 19.1% (2021-25) [SEC XBRL]
- Analyst targets post-rally: $240-255 (MS, TD Cowen, Barclays/BofA, RBC) [T4]
Catalysts and risks
Catalysts
- Q3 2026 earnings, October 21, 2026 — revenue ~$6.55B, adj EPS ~$1.92 consensus
- FY26 guidance direction and any 2027 framing including Masimo contribution
- Bioprocessing order/book-to-bill disclosure
- TMO and Agilent earnings as sector read-throughs
Risks
- Binary earnings event 5 days after the data as-of date, entered after a 20% six-month run
- Estimate cuts continue if Masimo financing costs or respiratory headwinds persist
- Bioprocessing orders prove to be inventory rebuild rather than end-demand
- Sector-level reversal — DHR trades as a TMO proxy and would fall with it
- Early-stage biotech spending remains selective, capping the recovery slope
What to watch
- Bioprocessing book-to-bill and order growth vs the reported mid-teens rate
- Diagnostics revenue vs ~$2.83B consensus, including Masimo integration commentary
- FY26 guidance: raised (validates breakout) vs held/cut (unwinds premium)
- DHR/TMO relative strength — whether DHR closes or widens the 3m gap
- China demand commentary across segments
Market snapshot when the call was made 2026-10-15
Price
| Return 1w | +6.5% |
| Return 1m | +11.1% |
| Return 3m | +13.6% |
| Return 6m | +19.5% |
| Return 1y | +12.3% |
| From 52-week high | -4.4% |
| Realized vol, 20d | 29.5% |
| SPY 3m / 1y | +3.8% / +16.5% |
| QQQ 3m / 1y | +4.7% / +21.7% |
Technicals
DHR technicals as of 2026-10-15: last close $231.50; 20d SMA 220.61 (bullish); 50d SMA 213.32; 12d EMA 221.85; 26d EMA 218.23; RSI 14 56.8 (balanced); 20d vol 29.2%; volume x1.1 vs 20d avg
Next earnings: 2027-01-26 AMC
Verifier notes PASS
Weakly sourced
- Bioprocessing orders growing 'mid-teens' rests on [T4] sources, but the opinion appropriately hedges it ('reportedly') and builds the entire thesis around verifying it on Oct 21, so this is acknowledged rather than overstated — noted for completeness, not a material finding.
Sources (24 · T1 = primary filings)
- T1https://www.sec.gov/Archives/edgar/data/313616/000119312526053124/d110495dex991.htm
- T4https://investors.danaher.com/2026-06-10-Danaher-Completes-Acquisition-of-Masimo-Corporation
- T1https://www.sec.gov/Archives/edgar/data/937556/000110465926015904/tm266533d1_ex99-1.htm
- T1https://www.sec.gov/Archives/edgar/data/937556/000119312526055065/d17484ddfan14a.htm
- T4https://www.danaher.com/press-releases
- T1https://www.sec.gov/Archives/edgar/data/937556/000110465926054512/tm2612557d3_ex99-1.htm
- T4https://www.stocktitan.net/sec-filings/MASI/page-2.html
- T4https://www.stocktitan.net/sec-filings/DHR/8-k-danaher-corp-de-reports-material-event-1fa9d0692865.html
- T1https://www.investor.agilent.com/news-and-events/news/news-details/2026/Agilent-Reports-Second-Quarter-Fiscal-…
- T1https://ir.thermofisher.com/investors/news-events/news/news-details/2026/Thermo-Fisher-Scientific-Reports-Seco…
- T4https://www.agilent.com/about/newsroom/presrel/2026/26aug-gp26016.html
- T1https://ir.thermofisher.com/investors/news-events/news/news-details/2026/Thermo-Fisher-Scientific-Reports-Firs…
- T1https://www.investor.agilent.com/news-and-events/news/news-details/2026/Agilent-Reports-First-Quarter-Fiscal-Y…
- T4https://www.thestockobserver.com/2026/10/16/agilent-technologies-nysea-sets-new-1-year-high-heres-what-happene…
- T4https://finance.yahoo.com/quote/TN80.DU/earnings/TN80.DU-Q2-2026-earnings_call-653574.html
- T4https://finance.yahoo.com/quote/TN8.F/earnings/TN8.F-Q2-2026-earnings_call-653574.html
- T4https://finance.yahoo.com/markets/stocks/articles/danaher-gears-post-q3-earnings-124100275.html
- T4https://www.perplexity.ai/finance/DHR
- T4https://finance.yahoo.com/markets/stocks/articles/seeking-clues-danaher-dhr-q3-121521025.html
- T4https://www.marketbeat.com/instant-alerts/upcoming-danaher-dhr-projected-to-release-quarterly-earnings-on-wedn…
- T4https://www.perplexity.ai/finance/DHR?comparing=DHR,WAT,BRKR,TMO,BIO,A
- T4https://www.perplexity.ai/finance/DHR?comparing=DHR,JNJ,ABT,HSIC,BSX,GEHC
- T4https://tellvest.com/company/DHR
- T4https://www.perplexity.ai/finance/DHR?comparing=DHR,CI,CAH,ELV,NTRA,TMO
Want a fresh look at DHR, or another name?
Queue a new deep-research run. Published to the feed when done.
Automated research opinion, published as-is on Oct 16, 2026. Not personalised advice. Figures use end-of-day closes.