Real activity, stale thesis.
Thesis
Bull case
Aave is the clear #1 lender ($17.6B TVL, $11.8B active loans, 69% utilization), the sector is recovering (+55% lending TVL since July), supply is 96.5% unlocked with no overhang, and V4 expansion (Base, Avalanche, new stablecoin markets) plus GHO/Horizon growth keep shipping. A governance-approved buyback restart at up to $1M/week against a $2.05B cap is a meaningful mechanical bid; combined with 0.12x mcap/TVL (cheap vs history), a restart could re-rate the token sharply from compressed-vol levels.
Bear case
The alpha leg is inert: buybacks reportedly paused since April, Aavenomics 3.0 unapproved, fees flat, TVL down 55% y/y and falling, Morpho structurally gaining share with an architecture institutions prefer, and the rsETH incident revealed balance-sheet exposure (25,000 ETH committed to DeFi United plus a 30,000 ETH Mantle credit line as backstop). The 6-month outperformance reverses toward beta (1.38x) in a weak crypto tape, and -74.7% max drawdown history shows how far unwinds can run.
What would change our mind
- Verified resumption of buybacks at ≥$500K/week sustained for a month — bearish lean is wrong; flip constructive
- Fees re-accelerate (>15% 30d-over-30d) with TVL stabilizing above $17B
- Aavenomics 3.0 passes with automatic revenue-funded buybacks/burn
- Conversely, TVL breaking below ~$15B with Morpho within $5B of Aave would confirm thesis decay
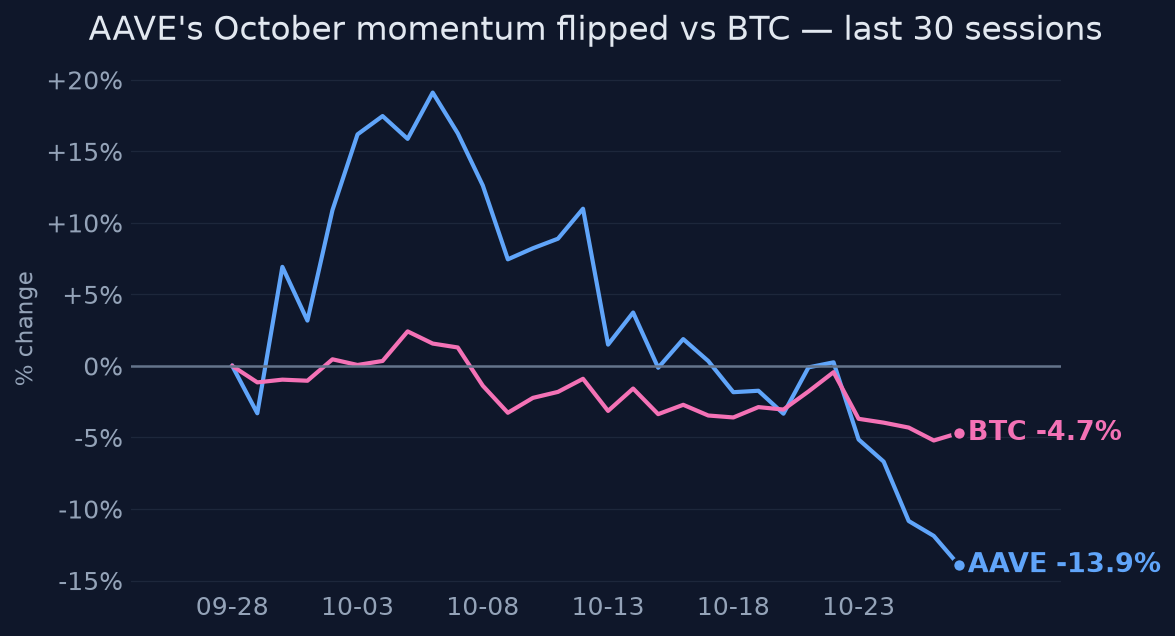
Since publication vs BTC · closed horizons are frozen
The full research everything the view rests on
Direct answer to the question asked
Where the edge would come from
What the price assumes
At 35x FDV/annualized revenue and 0.12x mcap/TVL the market still prices Aave as the dominant lender with a credible path to renewed buybacks and Aavenomics 3.0 value accrual. The price assumes the reported buyback pause is temporary and governance restarts purchases within the 3-6 month window.
Why the market may be wrong
If buybacks stay paused and Aavenomics remains unapproved governance, the token's value-capture story is inert: holders get governance rights and Safety Module staking, but no live fee switch or burn. Meanwhile the #1 competitive moat (scale/liquidity network effects) is eroding at the margin — Morpho added TVL in the same week Aave lost $1.5B.
The one thing to watch
The variable to watch is not TVL or V4 headlines — it is verified buyback execution (TokenLogic dashboard / governance vote on the $4M aEthUSDT restart tranche). The entire summer alpha was a value-accrual re-rating; with purchases reportedly paused since April 19, the token is currently a governance option on a fee switch that doesn't exist yet, and the October relative-strength flip (-10% vs BTC in a month after +31% over 6m) is the market repricing exactly that.
Key evidence (9)
- Price $133.02: -11% 1w, -14.5% 1m, but +36% 3m/6m; RSI 34, below 20d/50d SMA, +24% vs 200d (CoinGecko, 2026-10-27)
- 24h volume $237M = 11.6% of mcap — deep liquidity, not thin (CoinGecko, 2026-10-27)
- TVL $17.6B: +21.6% 90d but -8.4% 30d and -55% 1y; ~$1.5B lost in October ($19.1B → $17.6B) (DefiLlama, 2026-10-27)
- Fees $37.5M/30d (+2.4% vs prior 30d); revenue $5.0M/30d; FDV/revenue 35.3x; annualized fees ~22% of mcap (DefiLlama)
- 60d beta 1.38 to BTC, correlation 0.66, ~57% idiosyncratic; 6m relative strength +31% vs BTC but -10.4% over last month (quant decomposition)
- Buybacks reportedly paused April 19, 2026 after rsETH incident; DAO committed 25,000 ETH to DeFi United plus a 30,000 ETH Mantle credit line; restart ($4M aEthUSDT tranche, up to $1M/wk for 6 months) proposed, execution unverified [T4 sources — weakly sourced, conflicts with governance report claiming program live]
- Morpho ~$11.1-11.4B TVL and gaining (+$304M in a measured week) vs Aave ~$17-17.6B; Aave retains ~69% loan utilization, highest among peers [T3/T4, Oct 2026]
- 96.5% of 16M max supply circulating; ~563K AAVE vesting into 2027 — negligible unlock overhang; Safety Module emissions ~109.5K AAVE/yr
- 20d realized vol at 10th percentile of trailing year — compression precedes a larger move, direction unknown
Catalysts and risks
Catalysts
- Governance vote/execution on buyback restart ($4M aEthUSDT tranche) — the single decisive trigger
- Aavenomics 3.0 binding vote (buybacks + staking + burn)
- Aave V4 on Base deployment (ARFC posted Oct 8, 2026) and V3.8 progression
- Stablecoin onboarding votes: USAT, USDe on Avalanche, USDG on Arbitrum (Oct 2026)
- Final rsETH loss accounting and any buyback resumption tied to it
Risks
- Buyback pause extends or restart is smaller than proposed — thesis leg stays inert
- Morpho share gains accelerate, compressing Aave's take rate and pricing power
- Another security incident (rsETH precedent) hitting DAO treasury
- High beta (1.38x) to a fragile crypto market; compressed vol resolving downward
- Key buyback-status evidence rests on [T4] sources and is contradicted by another report — sizing on it is premature
What to watch
- TokenLogic buyback dashboard and governance votes on the restart tranche
- DefiLlama 30d fees direction and Aave vs Morpho weekly TVL delta
- Direction of the vol-compression break: reclaim of the 50d SMA (~$150) vs loss of $120
- Aavenomics 3.0 proposal progress to binding vote
- AAVE/BTC relative strength ratio — continuation of the -10% monthly flip
Market snapshot when the call was made 2026-10-27
Price
| Return 1w | -10.9% |
| Return 1m | -14.5% |
| Return 3m | +35.9% |
| Return 6m | +36.3% |
| Return 1y | -44.7% |
| From 52-week high | -44.7% |
| Realized vol, 20d | 58.2% |
| BTC 3m / 1y | +26.4% / -29.6% |
| ETH 3m / 1y | +24.1% / -43.6% |
| QQQ 3m / 1y | +5.4% / +16.6% |
Technicals
Verifier notes REVISE · opinion revised once
Unsupported claims
- Bear case: 'the rsETH incident revealed balance-sheet fragility (55,000 ETH of commitments)' — the evidence states the DAO committed 25,000 ETH to DeFi United and arranged a credit line of up to 30,000 ETH from Mantle. A credit line is an arranged backstop, not a commitment; adding the two as '55,000 ETH of commitments' overstates the deployed/contingent liability. The opinion's own key_evidence bullet states the split correctly, so this is an internal numeric error, not an arithmetic derivation from evidence figures.
Weakly sourced
- Thesis states 'buybacks have been paused since the April rsETH incident' as settled fact, but the only support is [T4]-tagged sources and the evidence bundle explicitly notes this conflicts with a governance report claiming the program was live. The opinion does hedge this properly in direct_answer ('appears paused'), key_evidence, and risks — but the thesis field, the most quotable summary, drops the hedge. Given the entire bearish lean rests on this claim, it should carry the 'reportedly/unverified' qualifier there too.
Internal inconsistencies
- Minor framing tension (acknowledged, not disqualifying): the opinion simultaneously asserts the July-Sept re-rating 'priced in... an active buyback' and that buybacks were paused since April 19 — i.e., the rally occurred entirely during the alleged pause. The evidence itself is contradictory on this (governance report says program live; other reporting says paused), and the opinion flags the conflict in key_evidence, so this is acceptable as long as the thesis hedge is added per above.
Corrections applied
- In bear_case, replace '55,000 ETH of commitments' with '25,000 ETH committed to DeFi United plus a 30,000 ETH Mantle credit line' (or 'up to 55,000 ETH of exposure/commitments and facilities') to match the evidence and the opinion's own key_evidence bullet.
- In thesis, change 'buybacks have been paused since the April rsETH incident' to 'buybacks have reportedly been paused since the April rsETH incident (execution status unverified and contested by a governance report claiming the program is live)', matching the hedge already used in direct_answer and key_evidence.
- Verify remaining spot-checked figures — all recomputed correctly against the bundle: 11.6% turnover ($237.25M/$2.05B), -14.54% 1m, +35.88% 3m/+36.3% 6m, +24.12% vs 200d SMA, RSI 34, TVL $17.62B (-8.4% 30d, +21.63% 90d, -55.05% 1y), fees $37.5M/30d (+2.42%), revenue $4.95M/30d, FDV/revenue 35.3x, mcap/TVL 0.12, annualized fees 22.27% of mcap, beta 1.38/corr 0.66/57% idiosyncratic, relative strength vs BTC +31.01% 6m / -10.37% 1m, vol 10th percentile, SMA50 ≈ $150 (133.02/(1-0.1111)), max drawdown -74.7%. Conviction 5 is band-consistent with LEAN_BEARISH; invalidation conditions are genuinely falsifiable.
Sources (24 · T1 = primary filings)
- T3https://coinmarketcap.com/cmc-ai/aave/latest-updates/
- T4https://www.tokenpost.com/news/investing/41197
- T4https://blockonomi.com/crypto-lending-statistics-2026-market-size-loans-and-interest-rates/
- T4https://gokhshtein.com/news/2026-10-23-defi-lending-tvl-hits-56b-as-aave-spark-expand-risk-reviews
- T4https://gokhshtein.com/news/2026-10-24-defi-lending-tvl-recovers-55-to-56b-aave-spark-tighten
- T4https://www.mediasnet.net/defi-market-analysis/
- T4https://www.tokenpost.com/tag/defi
- T4https://www.certik.com/blog/morpho-new-high-defi-lending-recovery
- T4https://econotimes.com/Aave-Falls-2-89-Over-24-Hours-to-131-45-in-Tuesday-Snapshot-1764293
- T3https://coinmarketcap.com/currencies/aave/historical-data/
- T4https://crypto.com/us/coins-ai/aave/price-analysis
- T3https://www.coingecko.com/en/coins/aave/historical_data
- T4https://governance.aave.com/t/al-development-update-may-2026/25013
- T4https://governance.aave.com/t/aci-full-transparency-report/24085
- T4https://coinpaper.com/37817/aave-price-drops-6-as-de-fi-token-breaks-key-support-despite-new-lending-markets
- T4https://governance.aave.com/t/al-development-update-july-2026/25482
- T4https://tokenomist.ai/research/weekly-unlock-digest-oct-26-nov-1-2026-ffs-20-7m-unlock-lands-in-fed-week
- T4https://app.aave.com/governance/
- T4https://finance.yahoo.com/markets/crypto/articles/citi-thinks-aave-could-become-170006828.html
- T4https://app.aave.com/governance/v3/proposal/?proposalId=286
- T4https://governance.aave.com/c/governance/4
- T4https://governance.aave.com/
- T4https://aave.com/docs/ecosystem/aave
- T4https://governance.aave.com/c/finance/30
Earlier and later calls on AAVE
- Oct 17, 2026Real activity, but fading.No clear edgeview changed
Want a fresh look at AAVE, or another name?
Queue a new deep-research run. Published to the feed when done.
Automated research opinion, published as-is on Oct 27, 2026. Not personalised advice. Figures use end-of-day closes.