Beat alone won't re-rate it.
Thesis
Bull case
Q2's 13% RoTCE is the new normal: Services/Banking/Wealth momentum plus NII ex-Markets at the top of the 5–6% guide drive FY27 EPS above the ~$12.9 consensus. A guide raise above 11% re-rates the stock toward a higher tangible-book multiple — higher-returning large-bank peers trade well above tangible book, and Citi at 1.29x with a credible 12–13% RoTCE path has room to close that gap. A ~$4B/quarter buyback pace (~$16B/yr, roughly 7% of market cap) materially supports EPS growth and signals capital strength, though repurchases above tangible book are modestly dilutive to TBV/share itself. Consent-order lifting (work ~90% done) and Banamex closing are unpriced optionality.
Bear case
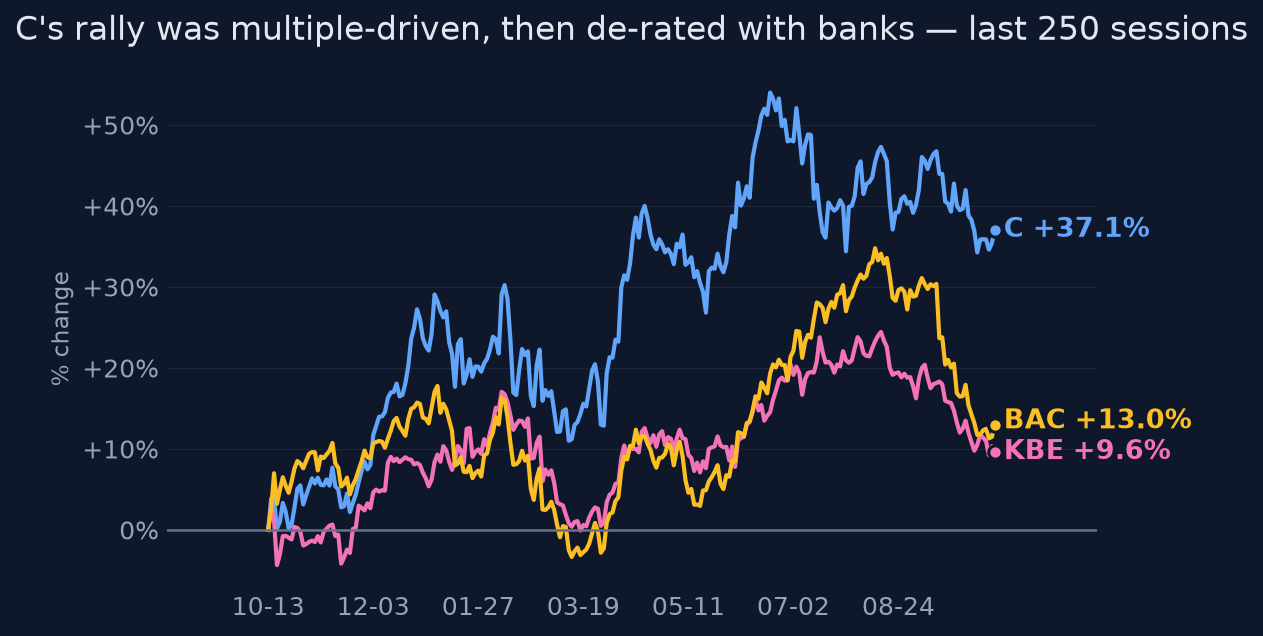
The entire 1y rally is multiple expansion on a capital-markets peak — estimates never followed the price. If Q3 shows Markets soft (BofA precedent), card NCLs accelerating beyond normalization, or NII guidance trimmed as deposit betas catch up with the hiking cycle, FY26 $11.19 has downside and a 1.29x TBV multiple on a 10–11% RoTCE bank compresses back toward 1.0–1.1x — implying 15–20% downside with no estimate cushion. The Fed hiking into 2027 worsens both credit and funding costs.
What would change our mind
- Bull case invalidated if Q3 RoTCE lands ≤11% with no guide raise AND card NCLs exceed plan — confirms 13% was a peak
- Bear case invalidated if management raises the RoTCE framework above 11% or signals sustained 12%+ for 2027 while credit stays in line
- If FY27 consensus (~$12.9) holds through two more quarters while the stock stays 10%+ below its high, the issue is multiple compression, not fundamental deterioration — reassess
Since publication vs SPY · closed horizons are frozen
The full research everything the view rests on
Direct answer to the question asked
Where the edge would come from
What the price assumes
Consensus Q3 2026: adjusted EPS $2.62–$2.66, revenue $23.66–23.72B, NII ~$16.6B (+11% YoY), Markets ~$6.1B; FY26 EPS ~$11.19, FY27 ~$12.9. Revisions flat-to-slightly-down. Price already embeds sustained ~12%+ returns: P/TBV 1.29x (TBV $100.89 at 6/30/26), buybacks ~$4B/quarter continuing ($10.3B in H1), and eventual consent-order relief (work reportedly ~90% complete).
Why the market may be wrong
Two ways. Bull: management has sandbagged — Q2 delivered 13% RoTCE and >9% operating leverage yet the 10–11% guide was retained; if Q3 confirms ~12%+ and the guide finally moves, FY27 EPS ~$12.9 could prove low and a 1.29x TBV multiple is cheap for a 13%+ RoTCE franchise. Bear: the re-rating is entirely multiple expansion on a capital-markets peak — BofA already flagged flat Q3 trading revenue, a hawkish Fed (hikes to a possible 4.25–4.50% peak) pressures deposit costs and loan demand, and Citi's outsized card book is the sector's most exposed asset if consumer credit cracks. Both are credible, hence no edge.
The one thing to watch
The variable to watch isn't EPS — it's the spread between printed RoTCE and the unrevised 10–11% guide. Citi's rally from sub-1.0x to 1.29x tangible book is a bet that 13% RoTCE is structural; the market has already paid for the answer, so only guidance language (a raise, or 2027 framing above 11%) can move the stock materially on a beat, while an in-line print with credit slippage breaks the multiple with no estimate cushion beneath it.
Key evidence (9)
- Q2 2026 actuals (Jul 14, 2026): revenue $24.8B (best in a decade), EPS $3.15, RoTCE 13.0% vs. 10–11% FY guide, >9% positive operating leverage [Citi release/8-K, T1/T4]
- Q3 2026 consensus: EPS $2.62–2.66, revenue ~$23.7B, NII ~$16.6B, Markets ~$6.1B; report due pre-market Oct 13, 2026 [MarketBeat/Yahoo/Zacks, T4]
- FY26 consensus EPS $11.19, FY27 ~$12.9; FY26 EPS revised down ~0.2% over 30 days [Yahoo/Zacks, T4]
- TBV/share $100.89 and CET1 12.8% at 6/30/26 (~120bp above requirement); H1 2026 buybacks $10.3B ($4.0B in Q2); $30B authorization; targeted CET1 ~12.6% [Citi Q2 10-Q/press release, T1/T4]
- Stock +36.2% 1y but -6.4% 1m, -11% off 52w high, RSI ~35, below 20/50d SMAs; bank index -6.8% in Sept, ~12% below mid-Aug high; BAC -13% 1m — move is sector-wide, not idiosyncratic [market data, quant analysis]
- Fed hiked to 3.75–4.00% in Sept 2026 with minutes pointing to another hike by year-end; some outlooks see 4.25–4.50% peak by Q1 2027, no easing before H2 2027 [T2/T3 macro reporting]
- BofA disclosed flat Q3 trading revenue, pressuring the group and questioning C's $6.1B Markets consensus [T2, cited in macro research]
- Consent orders: work reportedly ~90% complete per CEO Fraser, Citi preparing comprehensive audit; lifting requires regulator sign-off, targeting end-2026 completion of work [Reuters, T2]
- Banamex: 24% stake sale (~$2.5B, ~1.01x local TBV) expected to close 2026, not an IPO; no confirmed listing timeline [T2/T3]
Catalysts and risks
Catalysts
- Q3 2026 earnings pre-market Oct 13, 2026 — RoTCE guide language, card credit, NII trajectory, buyback pace
- Q4 2026 report Jan 14, 2027 (consensus EPS ~$2.38) and 2027 guidance framing
- Consent-order resolution: comprehensive audit submission and Fed/OCC sign-off, work targeted complete by end-2026
- Banamex 24% stake sale closing (~$2.5B) expected 2026
- FOMC meetings through Q1 2027 — market pricing a possible Dec hike and 4.25–4.50% peak
Risks
- Card credit deterioration beyond normalization — Citi has the largest card book among money-centers and previews flag credit as more important than headline EPS
- Markets revenue miss vs. $6.1B consensus after BofA's flat Q3 trading disclosure
- Deposit-cost pressure from higher-for-longer rates compressing NII below the 5–6% ex-Markets guide
- Regulatory slippage: consent-order lifting delayed beyond end-2026 work completion
- Multiple compression risk: 1.29x TBV is historically rich for Citi even if fundamentals hold
What to watch
- RoTCE guide: raised vs. reaffirmed 10–11%, and any 2027 framing
- Card NCLs and delinquency trends vs. plan
- Markets revenue vs. ~$6.1B consensus (BofA read-through)
- NII vs. ~$16.6B and commentary on 2027 NII as deposit betas rise
- Buyback pace (≥$4B/quarter?) and CET1 vs. ~12.6% target
- Consent-order audit submission and any regulator language; Banamex closing confirmation
Market snapshot when the call was made 2026-10-09
Price
| Return 1w | +0.9% |
| Return 1m | -6.4% |
| Return 3m | -7.9% |
| Return 6m | +4.7% |
| Return 1y | +36.2% |
| From 52-week high | -11.0% |
| Realized vol, 20d | 21.3% |
| SPY 3m / 1y | +3.9% / +15.7% |
| QQQ 3m / 1y | +5.5% / +22.9% |
Technicals
C technicals as of 2026-10-09: last close $129.64; 20d SMA 131.24 (bearish); 50d SMA 133.63; 12d EMA 129.65; 26d EMA 131.41; RSI 14 34.8 (balanced); 20d vol 20.4%; volume x0.6 vs 20d avg
Next earnings: 2027-01-14 AMC
Verifier notes REVISE · opinion revised once
Unsupported claims
- Bull case: 'buybacks of $4B+/quarter compound TBV ~10%+ annually at these prices' — no figure in the evidence supports ~10% TBV-per-share compounding, and the arithmetic is dubious: repurchasing stock at 1.29x tangible book (price ~$130 vs TBV $100.89) is dilutive, not accretive, to TBV/share; $16B/yr of buybacks is ~7% of the ~$225B market cap, not 10%+ TBV growth.
- Bull case: 'JPM trades far higher on ~17% RoTCE' — the bundle contains no JPM RoTCE or valuation data; the only JPM data in evidence are price returns/beta/correlation. This specific comparison figure appears from nowhere.
Corrections applied
- Remove or soften the '~10%+ TBV compounding' claim; a defensible version is 'a ~$16B/yr buyback pace (~7% of market cap) supports EPS growth and signals capital strength, though buybacks above tangible book are modestly dilutive to TBV/share.'
- Delete the '~17% RoTCE' figure for JPM or rephrase without a specific number (e.g., 'higher-returning peers trade well above tangible book'), since the evidence bundle contains no JPM returns or valuation data.
Sources (32 · T1 = primary filings)
- T4https://www.investing.com/news/stock-market-news/citi-seeks-rapid-resolution-of-its-us-regulatory-burdens-4943…
- T2https://www.reuters.com/business/finance/citigroup-aims-complete-work-consent-orders-this-year-sources-say-202…
- T4https://it.marketscreener.com/notizie/citi-punta-a-risolvere-rapidamente-i-vincoli-normativi-negli-stati-uniti…
- T4https://at.marketscreener.com/boerse-nachrichten/citi-strebt-rasche-loesung-seiner-regulatorischen-probleme-in…
- T4https://www.citigroup.com/global/news/press-release/2026/citi-third-quarter-2026-earnings-call
- T4https://www.citigroup.com/global/news/press-release/2026/citi-announces-agreements-with-investors-for-commitme…
- T4https://finance.yahoo.com/economy/policy/articles/market-chatter-citigroup-seeks-speed-110105954.html
- T4https://ca.finance.yahoo.com/news/citi-reaffirms-focus-regulatory-compliance-130411728.html
- T4https://www.marketbeat.com/earnings/reports/2026-10-13-citigroup-inc-stock/
- T4https://tickeron.com/blogs/citigroup-c-q3-2026-earnings-preview-19-eps-growth-in-focus-18594/
- T4https://www.investing.com/analysis/big-banks-enter-earnings-season-cheap-oversold-and-facing-a-growth-hangover…
- T4https://finance.yahoo.com/markets/stocks/articles/citigroup-reports-q3-earnings-october-160451058.html
- T4https://finance.yahoo.com/quote/C/analysis/
- T4https://www.zacks.com/stock/news/3003152/heres-how-to-play-citigroup-stock-ahead-of-q3-earnings-release
- T4https://www.perplexity.ai/finance/C?comparing=C,HSBC,STT,MS,NTRS,ALLY
- T4https://www.marketbeat.com/stocks/NYSE/C/earnings/
- T4https://www.citigroup.com/rcs/citigpa/storage/public/Earnings/Q22026/2026prqtr2rslt.pdf
- T4https://www.citigroup.com/rcs/citigpa/storage/public/citigroup-2q26-10-q.pdf
- T4https://www.stocktitan.net/sec-filings/C/10-q-citigroup-inc-quarterly-earnings-report-f63188bd8160.html
- T1https://www.sec.gov/Archives/edgar/data/831001/000110465926083383/c-20260714xex99d1.htm
- T4https://www.citigroup.com/rcs/citigpa/storage/public/Earnings/Q22026/8-K-2Q26-earnings-071426.pdf
- T4https://stockanalysis.com/stocks/c/transcripts/649259-q2-2026/
- T4https://www.investing.com/news/company-news/citigroup-q2-2026-slides-record-revenue-market-eyes-spending-plans…
- T4https://www.citigroup.com/rcs/citigpa/storage/public/Earnings/Q22026/2026fsqtr2rslt.pdf
- T4https://finance.yahoo.com/markets/stocks/articles/us-banks-correction-territory-ahead-002549326.html
- T4https://www.swissinfo.ch/eng/a-higher-rate-world-is-in-store-as-central-banks-approach-2027/92200921
- T4https://www.usbank.com/corporate-and-commercial-banking/insights/economy/outlook/monthly.html
- T3https://www.cnbc.com/2026/10/06/stock-market-today-live-updates.html
- T3https://www.cnbc.com/2026/10/09/bank-stocks-selloff-q3-earnings.html
- T3https://www.spglobal.com/market-intelligence/en/news-insights/articles/2026/10/most-us-bank-stocks-trade-lower…
- T4https://www.theepochtimes.com/business/fed-expects-another-rate-hike-before-end-of-2026-minutes-6100699
- T4https://www.perplexity.ai/finance/USB?comparing=USB,WFC,HSBC,TD,RY,C
Want a fresh look at C, or another name?
Queue a new deep-research run. Published to the feed when done.
Automated research opinion, published as-is on Oct 12, 2026. Not personalised advice. Figures use end-of-day closes.