A raise is already priced in.
Thesis
Bull case
GE beats the ~$2.00 bar and raises FY26 EPS guidance to ≥$7.95–8.00 with FCF above $9.2B, validating consensus and confirming the Q2 raise was conservative. CES margin commentary shows stabilization and a credible 2H re-acceleration path as LEAP mix matures and pricing offsets inflation; tariff costs are quantified and recoverable. With the stock 18% off its high, estimates rising, and a quiet tape, a clean raise re-rates the stock toward the $380–435 target range — the de-rating is revealed as overdone multiple compression, not deterioration.
Bear case
Q3 is in-line-to-modestly-beaten but guidance is held — which, with consensus above the guide top, trades as a miss. CES margins slip again on LEAP mix, GE9X drag, and inflation; management's 'margin expansion resumes in 2H' loses credibility after a second consecutive quarter of compression. A larger-than-expected tariff cost or LEAP delivery slippage compounds it. At ~40x forward with a 5.5% implied move and the stock below its 50-day, a guidance disappointment overshoots to the downside, and the late-September target cuts prove to be the beginning, not the end, of multiple normalization toward the low-30s.
What would change our mind
- For the 'margin problem' framing: Q3 shows CES margin up sequentially with management confirming 2H expansion on track — then the de-rating is overdone and the bull case activates
- For the 'raise is priced' framing: FY26 guidance is raised above $7.91 AND the stock fails to rally — indicating expectations ran ahead of even the whisper
- For the demand thesis: spare-parts/shop-visit commentary weakens or departures guidance is cut — that would break the aftermarket foundation both cases assume
- If FY27 consensus ($9.04) starts being cut while the stock holds ~$312, the multiple debate is resolving bearishly regardless of the Q3 print
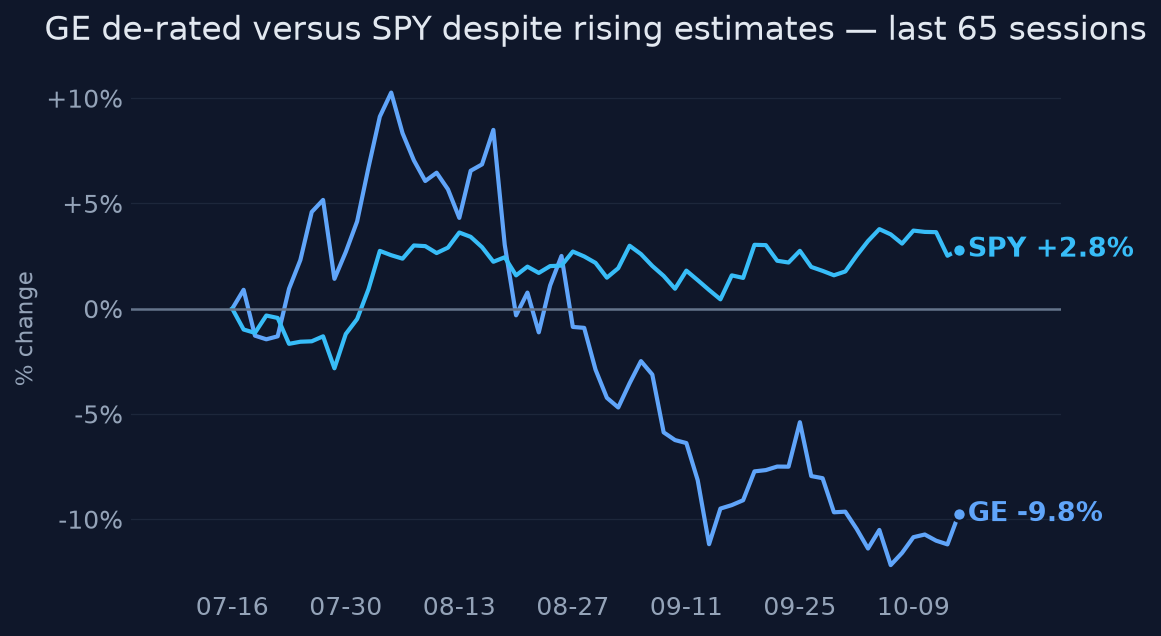
Since publication vs SPY · closed horizons are frozen
The full research everything the view rests on
Direct answer to the question asked
Where the edge would come from
What the price assumes
Consensus: ~$1.99–$2.04 adj. EPS on ~$12.8–13.2B revenue for Q3; FY2026 EPS consensus of $7.91 and revenue ~$50.3–50.6B, both above/at the raised guidance framework set July 16. 21 analysts raised 2026 EPS estimates in the last 30 days while Wells Fargo and Jefferies cut price targets — the street expects the numbers but has lost faith in the multiple. Options imply a ~5.5% one-day move (~$17), elevated for an industrial and consistent with guidance being the real variable.
Why the market may be wrong
Two-sided. Bulls may be wrong that a raise is a formality: management raised guidance only three months ago and flagged 'three large issues' on margins (installed-engine growth, GE9X investment, inflation); if those persist, holding guidance is the disciplined choice and consensus is one raise ahead of reality. Bears may be wrong that margin pressure is structural: LEAP economics are mix-driven and improving as the installed base matures, spare-parts orders +40% signal aftermarket pricing power, and a de-rated stock at RSI ~32 with quiet 20-day vol (0th percentile) means even a clean hold-and-stabilize print could squeeze higher.
The one thing to watch
FY2026 consensus EPS ($7.91) sits above the top of management's own raised guidance ($7.85) — so the usual 'beat the quarter' framing is obsolete; the variable to watch is whether CES margin commentary turns a guidance hold from a non-event into a de facto miss, and whether a raise to ≥$7.95 re-rates the multiple rather than just validating estimates.
Key evidence (9)
- Q3 2026 report scheduled Oct 20, 2026 pre-market (GE Aerospace IR events page [T1-hosted])
- Q2 2026 (July 16): adj. EPS $2.02 vs $1.86 est; revenue $12.63B vs $11.87B est, +21% y/y; FY26 guidance raised — EPS $7.65–$7.85, op profit $10.55–10.75B, FCF $8.9–9.2B, LEAP deliveries to high-teens growth (GE Q2 press release/transcript [T1 content])
- Q2 margin deterioration: operating margin -130bp to 21.7%, CES margin -160bp to 27.3%; management cited installed-engine growth, GE9X investment, inflation — 'three large issues' (GE Q2 transcript [T1 content])
- FY2026 consensus $7.91 EPS / ~$50.3–50.6B revenue; FY2027 EPS $9.04; 21 analysts raised 2026 EPS in last 30 days; estimates +0.6% over 60 days (stockanalysis/Zacks [T4] — approximate)
- Price-target cuts despite rising estimates: Wells Fargo $390→$380 (Sep 30), Jefferies $455→$435 (Sep 23) [T4]
- Stock $312 close Oct 15, -15% over 3 months, -18% below $388.84 52w high, RSI ~32, 20d realized vol at 0th percentile of past year; SPY +3.8% over same period (market data)
- Options-implied one-day move ~5.5% / ~$17 (Barchart [T4] — approximate)
- Aftermarket strength: spare-parts orders +40% y/y (spring), CFM56 parked aircraft declining; GE/CFM departures flat-to-low-single-digit in 2026 (GE IR Q&A [T1-hosted])
- Peer read-throughs: Rolls-Royce raised 2026 op profit guide to £4.7–4.9B on LTSA margins; Howmet guided ~27% adj. EBITDA growth; Boeing at 47/mo MAX studying 63, Airbus targeting 70–75 narrowbody/mo by end-2027 (RR/Howmet releases, Reuters [T2])
Catalysts and risks
Catalysts
- Q3 2026 earnings and call, Tuesday Oct 20, 2026, 7:30am ET — the immediate binary
- FY2026 guidance decision: raise (≥$7.95), hold, or trim — the single largest repricing trigger
- CES margin print and management commentary on 2H margin trajectory
- Quantified tariff cost exposure and pricing-recovery commentary
- LEAP delivery cadence and durability-kit cutover progress toward early 2027
- RTX and Safran Q3 results (peer aftermarket read-throughs, late October)
- Boeing 737 MAX rate decisions (47→63/mo study) and Airbus ramp execution through year-end
Risks
- Guidance hold interpreted as a miss given consensus above guide top — asymmetric near-term downside
- Continued CES/operating margin erosion reframed as structural rather than ramp-related
- Tariff cost burden larger or less recoverable than assumed (no quantified primary-source estimate available)
- LEAP delivery slippage or working-capital/cash-conversion pressure from the ramp
- Supply-chain constraints (castings, forgings, repair capacity) cap conversion of strong orders into revenue
- ~40x forward multiple leaves little room for narrative slippage even on decent fundamentals
- Key consensus/implied-move figures rest on [T4] aggregators, not primary sources
What to watch
- FY26 EPS guidance: raised to ≥$7.95 (bullish), held at $7.65–$7.85 (de facto miss vs $7.91 consensus), or trimmed (bearish)
- CES segment margin vs Q2's 27.3% — sequential direction matters more than the level
- FCF guide relative to $8.9–9.2B and working-capital commentary
- Any quantified tariff number and stated recovery mechanism
- LEAP deliveries vs high-teens growth guide; durability-kit industrialization timeline
- Post-print: whether FY27 estimates ($9.04) move, and whether price targets stabilize after September's cuts
- RTX/Safran prints later in October for confirmation or contradiction of the services-margin narrative
Market snapshot when the call was made 2026-10-15
Price
| Return 1w | +2.1% |
| Return 1m | -0.3% |
| Return 3m | -10.6% |
| Return 6m | +4.7% |
| Return 1y | +4.4% |
| From 52-week high | -18.2% |
| Realized vol, 20d | 19.4% |
| SPY 3m / 1y | +3.8% / +16.5% |
| QQQ 3m / 1y | +4.7% / +21.7% |
Technicals
GE technicals as of 2026-10-15: last close $312.00; 20d SMA 312.90 (bearish); 50d SMA 331.65; 12d EMA 310.12; 26d EMA 316.25; RSI 14 31.8 (balanced); 20d vol 19.4%; volume x0.9 vs 20d avg
Sources (24 · T1 = primary filings)
- T4https://www.geaerospace.com/sites/default/files/geaerospace_webcast_transcript_07162026.pdf
- T4https://www.geaerospace.com/news/investor-relations/ir-updates/ge-aerospace-releases-its-2q26-results
- T4https://www.geaerospace.com/sites/default/files/geaerospace_webcast_presentation_07162026_2.pdf
- T4https://www.geaerospace.com/sites/default/files/geaerospace_webcast_pressrelease_07162026.pdf
- T4https://stockanalysis.com/stocks/ge/transcripts/652118-q2-2026/
- T4https://finance.yahoo.com/quote/GE.MX/earnings/GE.MX-Q2-2026-earnings_call-652118.html
- T4https://fortune.com/company/general-electric/earnings/q2-2026/
- T4https://www.investing.com/news/transcripts/earnings-call-transcript-ge-aerospace-beats-q2-2026-estimates-raise…
- T4https://finance.yahoo.com/markets/stocks/articles/why-time-load-ge-aerospace-133539208.html
- T2https://www.reuters.com/legal/transactional/aerospace-dealmaking-gathers-pace-jet-production-ramps-up-2026-09-…
- T4https://www.marketbeat.com/stocks/NYSE/GE/news/
- T4https://www.rolls-royce.com/media/press-releases/2026/30-07-2026-rr-holdings-plc-2026-half-year-results.aspx
- T4https://www.howmet.com/wp-content/uploads/sites/3/2026/05/2026-Q1-Earnings-Presentation-Final.pdf
- T2https://www.reuters.com/business/aerospace-defense/boeing-studying-boost-737-max-plane-production-highest-ever…
- T4https://www.geaerospace.com/news/investor-relations/ir-updates/recent-events-your-questions-answered
- T2https://www.reuters.com/business/aerospace-defense/boeing-weighs-737-ramp-up-approach-airbus-production-target…
- T4https://www.geaerospace.com/investor-relations/events-reports/ge-aerospace-3rd-quarter-2026-earnings-webcast
- T4https://www.geaerospace.com/investor-relations/events-reports
- T3https://www.morningstar.com/stocks/ahead-ge-aerospace-earnings-is-stock-buy-sell-or-fairly-valued
- T4https://www.geaerospace.com/ja/node/5614
- T4https://www.geaerospace.com/investor-relations/ir-updates
- T4https://www.el-fondo.com/en/news/ge-aerospace-to-report-third-quarter-results-on-tuesday
- T4https://www.barchart.com/futures/quotes/GE
- T4https://www.perplexity.ai/finance/GE
Want a fresh look at GE, or another name?
Queue a new deep-research run. Published to the feed when done.
Automated research opinion, published as-is on Oct 16, 2026. Not personalised advice. Figures use end-of-day closes.