Fundamentals yes; setup already broken.
Thesis
Bull case
Earnings power is real and the multiple is not extended: ~11.4x forward earnings in a sector trading below long-run valuation norms, with net cash, record FCF, lowered FY AISC guidance ($1,520/oz), Cadia copper recovering, and Q4 guided as the strongest production quarter. If gold merely holds ~$4,000 and Q4 costs prove one-off, FY27 EPS of $10.18 is credible and the stock re-rates; bank gold targets ($4,600-5,000+) provide optionality. 20d vol at the 5th percentile means compression could resolve sharply upward on any gold stabilization.
Bear case
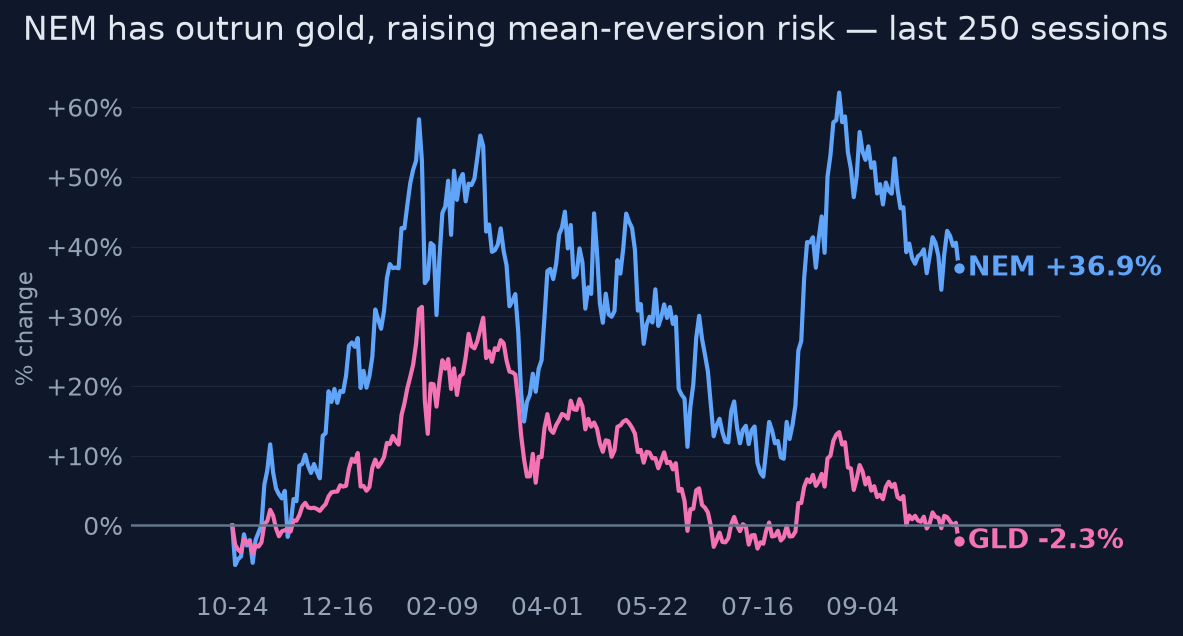
The stock just sold a beat — the market is pricing forward, and forward is worse: Q4 AISC ~$1,900/oz, $1.95B to Barrick, $600M Q4 sustaining capex, and a production target that requires a flawless ramp after a down y/y Q3. Gold, the dominant driver (0.89 correlation), is in a downtrend with a December hike nearly fully priced; miners' operating leverage cuts both ways. The NEM/GLD ratio at an extreme means even flat gold could mean miner underperformance. FY27 consensus is a margin assumption with revenue revisions already net negative.
What would change our mind
- For a constructive view: gold breaks below ~$3,800 or Q4 print shows AISC staying above ~$1,700/oz into 2027 guidance — the margin story is impaired
- For a cautious view: NEM reclaims its 50d SMA and makes new highs while gold is flat-to-down — that would signal genuine idiosyncratic re-rating, not beta
- If FY27 EPS estimates hold ~$10 while the stock stays 15%+ below its high into February, the weakness is multiple compression, not deterioration — that flips the risk/reward constructive
Since publication vs SPY · closed horizons are frozen
No price data after the entry date yet.
The full research everything the view rests on
Direct answer to the question asked
Where the edge would come from
What the price assumes
At ~11.4x FY26 EPS of $9.20, the market prices NEM as a cyclical at elevated-but-not-euphoric earnings; FY27 consensus of $10.18 embeds continued wide margins (gold high, costs controlled). Revenue revisions 3 up/10 down over 3 months while EPS revisions stayed net positive shows consensus is a margin/gold-price assumption, not volume growth.
Why the market may be wrong
Either side could be wrong: bulls underestimate how much of FY27 EPS is a gold-price derivative with operating leverage working in reverse if bullion slides toward $3,500-3,800; bears underestimate that the sector de-rated while earnings quadrupled since 2023, so a gold stabilization alone could re-rate miners without needing new highs in bullion.
The one thing to watch
The variable to watch isn't NEM's earnings — it's the NEM/GLD ratio. NEM outperformed gold itself by ~34% over 1y and ~23% over 3m, meaning the stock has already priced in sustained margin expansion, not just a high gold price. If the NEM/GLD ratio mean-reverts while gold merely drifts sideways, NEM underperforms even in a benign gold tape. The scan is effectively flagging a ratio trade at its extreme.
Key evidence (8)
- Q3 2026 (Oct 22, [T2] Reuters): adj EPS $2.20 vs $2.05 consensus; revenue $6.36B +15% y/y; record FCF ~$1.9B; net cash ~$3.2B — fundamentals strong [fact]
- FY guidance: production held at 5.3Moz but Q3 output fell y/y (1.30 vs 1.42Moz); Q4 must ramp to ~1.4Moz with AISC spiking to ~$1,900/oz vs $1,454 in Q3 [fact, company guidance]
- $1.95B cash payment to Barrick (Nevada JV amendment) due in Q4; Red Chris block cave $4.2-4.8B capex, FID early 2027, production only 2033 [fact]
- Technicals (Oct 22-23 data): below 20d/50d SMA, -7.6% 1m, -15.6% from 52w high, sold ~3.5% on an earnings beat; RS vs SPY flipped from +18% (3m) to -7% (1m) [fact]
- Gold at ~$4,085/oz, 26% below Jan 2026 peak of $5,595; 94% priced probability of a December Fed hike; GLD -14% over 6m [T2 macro reporting]
- NEM correlation to GLD 0.89 and AEM 0.93; 1y spread vs GLD +34% [computed from price history]
- Sector at ~5.7x forward EV/EBITDA vs ~9.9x historical peak, ~22% below 20y average earnings multiple [T3/T4 — treat as directional]
- EPS trajectory: -$2.97 (2023) → $2.92 (2024) → $6.39 (2025); FY26 consensus $9.20, FY27 $10.18 [SEC XBRL / consensus aggregators]
Catalysts and risks
Catalysts
- December 2026 FOMC decision (94% hike probability priced) — direct hit to gold and thus NEM
- Q4 2026 earnings Feb 17, 2027: whether AISC normalizes from ~$1,900/oz and whether the 1.4Moz Q4 ramp delivered
- AEM and Barrick Q3 prints — peer read on whether cost inflation is sector-wide
- Red Chris FID (early 2027) — capital allocation signal
- Gold ETF flow continuation after Q3's $6.8B inflow
Risks
- Gold correction toward $3,500-3,800 on higher real yields — amplified through operating leverage
- Q4 cost spike proves to be a 2027 cost reset rather than one-off timing
- FY production miss if the Q4 ramp disappoints
- NEM/GLD ratio mean reversion independent of gold direction
- December Fed hike stronger/more hawkish than priced
What to watch
- NEM/GLD ratio — the single best gauge of whether miner leverage is over- or under-priced
- December FOMC and real-yield trajectory
- Gold ETF flows (Q3 added $6.8B; continuation or reversal)
- Q4 production/AISC commentary ahead of the Feb 17 print
- AEM and Barrick Q3 results for sector-wide cost read
- Whether the 20d vol compression (5th percentile) resolves with the trend or against it
Market snapshot when the call was made 2026-10-22
Price
| Return 1w | -1.4% |
| Return 1m | -7.6% |
| Return 3m | +22.4% |
| Return 6m | +2.8% |
| Return 1y | +32.2% |
| From 52-week high | -15.6% |
| Realized vol, 20d | 32.3% |
| SPY 3m / 1y | +3.4% / +13.8% |
| QQQ 3m / 1y | +3.0% / +15.2% |
Technicals
NEM technicals as of 2026-10-22: last close $114.11; 20d SMA 116.20 (bearish); 50d SMA 121.77; 12d EMA 116.41; 26d EMA 117.55; RSI 14 47.3 (balanced); 20d vol 32.2%; volume x1.8 vs 20d avg
Next earnings: 2027-02-17 AMC
Verifier notes PASS
Weakly sourced
- The '~11.4x forward P/E' figure rests on a [T4] stockanalysis.com citation and does not reconcile with the opinion's own stated price and EPS: $114.11 / $9.20 FY26 consensus = ~12.4x, not 11.4x (11.4x would imply a ~$105 price or ~$10 forward EPS, i.e., roughly the FY27 multiple at 11.2x). The number appears verbatim in the evidence so it is not fabricated, and the discrepancy does not change the NO_CLEAR_EDGE conclusion (12.4x is still below the ~14.4x trailing multiple and sector norms), but the opinion should not present '11.4x FY26 EPS of $9.20' as internally consistent arithmetic.
- The gold downside scenario of '$3,500-3,800' (used in why_market_may_be_wrong, risks, and invalidation_conditions) appears nowhere in the evidence bundle; bank targets in evidence run $4,600-5,000+ to the upside. It is framed as a conditional scenario rather than a sourced forecast, so it is acceptable as an analyst-constructed invalidation threshold, but a reader could mistake it for a sourced downside estimate.
Internal inconsistencies
- Minor: the opinion's valuation framing ('~11.4x FY26 EPS of $9.20' and 'No asymmetric edge at $114') is arithmetically inconsistent — $114.11 / $9.20 = 12.4x. The 11.4x figure matches FY27 EPS ($114.11 / $10.18 = 11.2x) or a lower price, not the stated FY26 basis. Not decision-changing but worth cleaning up since the multiple is a pillar of the bull case.
Corrections applied
- In 'answer', 'market_expectation', and 'bull_case', restate the multiple accurately: either '~12.4x FY26 consensus EPS of $9.20 (and ~11.2x FY27 EPS of $10.18)' or attribute the 11.4x figure explicitly to the [T4] data provider's forward (NTM) P/E rather than to FY26 EPS at the current price.
- Optionally mark the $3,500-3,800 gold downside level as an illustrative scenario threshold chosen for invalidation purposes, not a sourced forecast, to avoid confusion with the evidence's bank target range ($4,600-5,000+).
Sources (27 · T1 = primary filings)
- T4https://www.newmont.com/investors/news-release/news-details/2026/Newmont-Reports-Third-Quarter-2026-Results-wi…
- T4https://www.newmont.com/investors/events-and-presentations/event-details/2026/Newmonts-Third-Quarter-2026-Resu…
- T4https://finance.biggo.com/news/US_NEM_2026-10-22
- T4https://www.investing.com/news/company-news/newmont-q3-2026-slides-record-cash-flow-red-chris-nears-decision-9…
- T2http://rmb.reuters.com/rmd/rss/item/tag:reuters.com,2026:newsml_KBN3W22W1?channel=frL012
- T4https://ca.investing.com/news/stock-market-news/earnings-call-transcript-newmont-beats-q3-2026-estimates-as-ca…
- T4http://www.kitco.com/news/article/2026-10-22/newmont-beats-third-quarter-earnings-expectations-higher-gold-sal…
- T4https://ng.investing.com/news/stock-market-news/earnings-call-transcript-newmont-beats-q3-2026-estimates-as-ca…
- T4https://www.invesco.com/apac/en/institutional/insights/etf/gold-report-quarterly-update.html
- T4https://www.thehindubusinessline.com/markets/gold/
- T4https://www.scrapmonster.com/news/gold/china-gold-reserves-surge-as-pboc-adds-63-tonnes-in-q3-2026-10-19/10028…
- T3https://global.morningstar.com/en-gb/markets/investors-keep-buying-gold-etfs-even-prices-fall
- T2https://www.bloomberg.com/news/articles/2026-10-09/banks-head-for-5-billion-gold-trading-windfall-in-record-ye…
- T4https://finance.yahoo.com/markets/commodities/articles/top-bank-revises-2026-gold-191300724.html
- T3https://global.morningstar.com/en-eu/markets/why-is-gold-price-falling-even-etf-investors-central-banks-pile
- T2https://www.reuters.com/world/india/gold-slips-investors-weigh-fed-rate-outlook-2026-10-20/
- T4https://www.kitco.com/opinion/2026-10-13/gold-mining-20-are-investors-looking-through-outdated-lens
- T4https://goldinvest.de/en/historic-valuation-gap-gold-producer-share-prices-lag-far-behind-earnings
- T1https://www.cruxinvestor.com/posts/golds-rebound-favors-royalty-holders-and-fuel-hedged-miners-as-costs-rise
- T4https://www.gold-eagle.com/forecasts_predictions
- T4https://news.metal.com/newscontent/104170129-gold-price-weakness-as-an-opportunity
- T4https://mining.com.au/gold-price-slides-under-pressure-but-barclays-sees-upside-ahead/
- T4https://www.perplexity.ai/finance/NEM?comparing=NEM,WPM,GMINF,AEM,DPMLF,AU
- T4https://econotimes.com/Newmont-Sets-Third-Quarter-Adjusted-Net-Income-Record-at-2-31-Billion-1761081
- T4https://seekingalpha.com/news/4656424-newmont-targets-red-chris-commercial-production-in-2033-while-lifting-fu…
- T4https://www.stocktitan.net/news/NEM/newmont-reports-third-quarter-2026-results-with-record-third-quarter-ldp1h…
- T4https://finchannel.com/newmont-beats-profit-estimates-as-cadia-recovery-lifts-copper-output/139219/american-bu…
Want a fresh look at NEM, or another name?
Queue a new deep-research run. Published to the feed when done.
Automated research opinion, published as-is on Oct 23, 2026. Not personalised advice. Figures use end-of-day closes.