Reaction overdone, but no cheap edge.
Thesis
Bull case
The sell-off is an overreaction to one-time optics: adjusted EPS beat, guidance was raised, Tremfya is growing 68% and absorbing Stelara losses, the talc resolution (if the 95% threshold is met) removes the largest legal overhang in the sector, and sell-side targets ($282-290) imply 13-16% upside from $248. A 0.24-beta stock that just had a 1.75-sigma idiosyncratic flush on a beat-and-raise historically mean-reverts; the 10.7% drawdown from the 52-week high at RSI ~30 supports that.
Bear case
The market is right to reprice: adjusted operational EPS growth guidance is only ~2%, Darzalex — the largest growth engine — decelerated and missed, MedTech missed in what should be the stable segment, and management is buying growth via dilutive acquisitions ($0.64 EPS hit) rather than generating it organically. At ~22x forward earnings with Stelara's biosimilar cliff still in progress and the talc deal not final, there is no valuation cushion if FY27's $12.26 consensus starts to slip.
What would change our mind
- If FY27 consensus EPS of $12.26 is cut materially (e.g., below ~$11.80) after Q4 earnings, the 'trough year' thesis fails and the multiple likely compresses further
- If the talc participation threshold is not met or the deal collapses, the de-risking leg of the bull case is void
- If Darzalex misses consensus again in Q4, treat the Q3 miss as trend, not noise
- If the stock holds above ~$260 on no new fundamental news within 3 months, the flush was purely technical and the dip-buy thesis worked
Since publication vs SPY · closed horizons are frozen
The full research everything the view rests on
Direct answer to the question asked
Where the edge would come from
What the price assumes
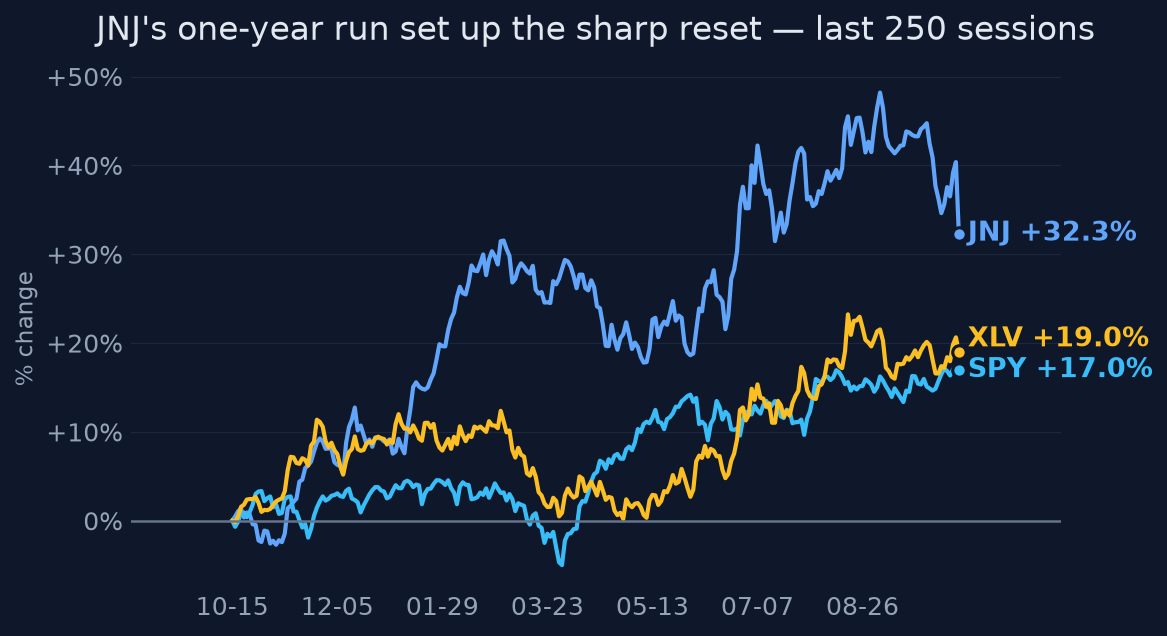
Heading into the print, JNJ was up 32.6% over one year (vs SPY +19.1%), trading at ~21-22x forward earnings near the top of its recent range, with 6 of 7 analysts at Buy and an average target just under $290. A clean beat-and-raise with no blemishes was substantially priced in; the market was paying for acceleration, and instead got 2% adjusted operational EPS growth guidance.
Why the market may be wrong
The drop was almost entirely idiosyncratic (60-day SPY correlation -0.08) and disproportionate: analysts actually raised targets post-print (RBC to $290 Outperform, BofA to $282 Hold), the talc charge is one-time and the proposed resolution removes a decades-long overhang, and the Firefly/Sail margin hit is acquired IPR&D — an accounting charge for pipeline investment, not operating decay. If Darzalex's miss proves one-off and MedTech's weakness is geopolitical/transitory, the market punished a 2% EPS-growth year at 22x while ignoring that the talc resolution could unlock a re-rating.
The one thing to watch
The variable to watch is not the talc headline or the $0.09 reported EPS — it is whether FY2027 consensus of $12.26 (+10.7%) survives the next two quarters, because that estimate implicitly assumes Darzalex re-accelerates and MedTech normalizes; the stock's ~22x multiple only works if 2026's ~2% adjusted operational EPS growth is a trough, not a trend.
Key evidence (8)
- Q3 2026 sales $25.4B, +5.9% reported / +6.0% operational; adjusted EPS $2.59 vs ~$2.52-2.53 consensus [T1 JNJ earnings presentation, 10/13/26]
- Reported EPS $0.09 (net income -96% to $210M) on talc resolution and Firefly/Sail charges; press characterizes talc charge ~$5.5B, but figures of ~$8B and >$9B nominal also cited — only partially verified [T1 SEC/IR; T3/T4 press]
- FY26 guidance raised to adjusted EPS $11.05-11.15 (midpoint $11.10, +$0.06) but still ~$0.58 below the July 15 midpoint of $11.68 after the July 29 acquisition-driven $0.64 cut [T1 SEC 8-K 7/29/26]
- Darzalex +16% to $4.24B vs ~$4.4B expected (miss); Stelara -54% to $716M; Tremfya +68% to $2.4B (beat) [T3 CNBC coverage]
- Innovative Medicine margin fell 44.3% to 35.4%, driven by ~$1B acquired IPR&D and mix; MedTech sales missed on Middle East/geopolitics though margin improved to 22.9% [T3]
- Stock fell ~6% on the print; 1-month return -1.75 sigma vs own history, 20d vol at 89th percentile, volume 2.2x average, 60-day correlation to SPY -0.08 (idiosyncratic) [quant analysis]
- Talc resolution is an agreement in principle (~$5.5B nominal, ~76,000 claims) requiring >=95% claimant participation; not court-approved or final as of Oct 2026 [T2/T4, partially verified]
- Post-earnings: RBC raised target to $290 (Outperform), BofA to $282 (Hold); pre-earnings average target just under $290 [T3/T4]
Catalysts and risks
Catalysts
- Q4 2026 earnings on 2027-01-26 (consensus EPS ~$3.02, revenue ~$26.8B) — first look at FY27 guidance
- Talc settlement participation milestone: confirmation that >=95% of claimants opted in, and court approval steps
- Darzalex quarterly trajectory — whether the Q3 miss was competitive or transitory
- RYBREVANT FASPRO priority review decision in head-and-neck cancer; OTTAVA robotics rollout
- JNJ 10-Q filing clarifying the true size/structure of the talc charge ($5.5B vs $8-9B nominal)
Risks
- Talc deal fails the 95% participation threshold, reopening trial risk and potentially a larger ultimate liability
- Darzalex miss signals competitive erosion, putting the +10.7% FY27 EPS consensus at risk
- Continued acquisition-driven EPS dilution and margin compression from IPR&D charges
- MedTech weakness persists beyond geopolitical one-offs
- Valuation: ~22x forward is the top of JNJ's recent range for ~2% EPS growth
What to watch
- FY2027 EPS estimate revisions — the single most important number
- Talc claimant opt-in rate and any court rulings on the settlement
- Darzalex and Tremfya prescription/sales trends into Q4
- MedTech order commentary and ex-US growth (only +1.8% in Q3)
- Whether the 10-Q confirms the talc charge at ~$5.5B or closer to $8-9B nominal
Market snapshot when the call was made 2026-10-13
Price
| Return 1w | -2.4% |
| Return 1m | -6.7% |
| Return 3m | +0.6% |
| Return 6m | +4.1% |
| Return 1y | +32.6% |
| From 52-week high | -10.7% |
| Realized vol, 20d | 26.6% |
| SPY 3m / 1y | +3.1% / +19.1% |
| QQQ 3m / 1y | +3.6% / +26.1% |
Technicals
JNJ technicals as of 2026-10-13: last close $248.61; 20d SMA 263.63 (neutral); 50d SMA 265.37; 12d EMA 259.41; 26d EMA 262.48; RSI 14 30.1 (balanced); 20d vol 26.1%; volume x2.2 vs 20d avg
Next earnings: 2027-01-26 AMC
Sources (22 · T1 = primary filings)
- T3https://www.cnbc.com/2026/10/13/jnj-earnings-q3-2026.html
- T4https://www.jnj.com/media-center/press-releases
- T1https://www.investor.jnj.com/investor-news/news-details/2026/Johnson--Johnson-reports-Q3-2026-results-raises-2…
- T4https://www.jnj.com/media-center/press-releases/financial
- T4https://finance.yahoo.com/quote/JNJ/earnings/JNJ-Q3-2026-earnings_call-682030.html
- T4https://www.rttnews.com/3698499/johnson-johnson-q3-profit-declines-lifts-fy26-outlook-stock-drops.aspx
- T4https://www.stocktitan.net/articles/johnson-johnson-q3-2026-earnings-talc-settlement
- T4https://finance.yahoo.com/healthcare/articles/j-j-q3-earnings-beat-135700661.html
- T1https://www.sec.gov/Archives/edgar/data/200406/000020040626000163/jnj-20260729.htm
- T1https://www.sec.gov/Archives/edgar/data/200406/000020040626000146/a2026q2exhibit991.htm
- T4https://www.jnj.com/media-center/press-releases/johnson-johnson-reports-q3-2026-results-raises-2026-guidance
- T1https://s203.q4cdn.com/636242992/files/doc_financials/2026/q2/JNJ-Earnings-Presentation-Q2-2026-Final-V2.pdf
- T4https://stockanalysis.com/stocks/jnj/transcripts/649224-q2-2026/
- T1https://s203.q4cdn.com/636242992/files/doc_financials/2026/q2/JNJ-Earnings-Presentation-Q2-2026-Final.pdf
- T4https://www.investing.com/news/transcripts/earnings-call-transcript-johnson--johnson-tops-q3-2026-eps-forecast…
- T4https://www.marketbeat.com/earnings/reports/2026-10-13-johnson-johnson-stock/
- T4https://www.stocktitan.net/sec-filings/JNJ/page-2.html
- T4https://markets.businessinsider.com/news/stocks/johnson-johnson-q3-earnings-on-october-13-analysts-see-10-upsi…
- T4https://www.drugwatch.com/talcum-powder/lawsuits/
- T4https://pharmaphorum.com/news/jj-approaching-end-its-talc-litigation-hangover
- T4https://finance.yahoo.com/quote/JNJ/analysis/
- T4https://www.analystlens.com/stocks/jnj/filings
Want a fresh look at JNJ, or another name?
Queue a new deep-research run. Published to the feed when done.
Automated research opinion, published as-is on Oct 14, 2026. Not personalised advice. Figures use end-of-day closes.