Mostly a momentum trap.
Thesis
Bull case
Steel-man: the raise-twice pattern plus record CoreSite bookings and reduced churn means Q3 (Oct 27) could deliver a third guidance raise, validating the re-rating. If SpaceX signs even an initial tower agreement in the next 3–6 months, the Street's 30k–120k site scenarios give years of incremental organic growth that isn't in any model. At ~16x AFFO vs a historical premium multiple, a rate peak + real tenant news could justify the ~$215 target (~18% upside). AMT is also the lower-beta, internationally diversified way to own the theme versus CCI.
Bear case
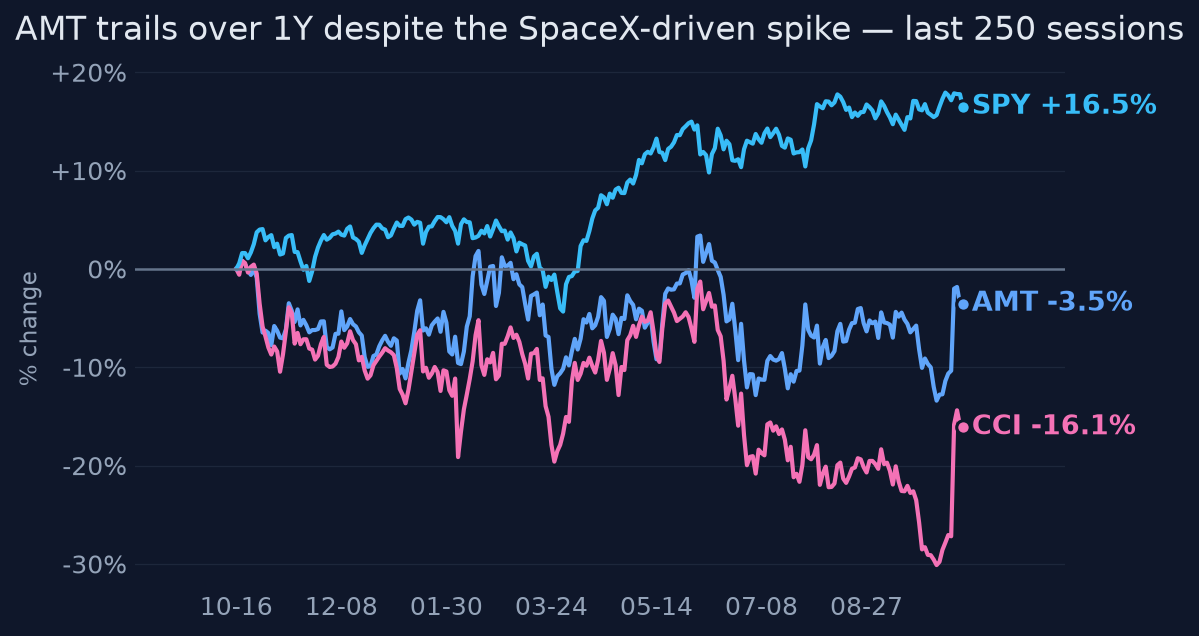
Steel-man: this is a laggard (+0.8% 1y vs SPY +16%) bouncing 8% on an unsigned customer, with RSI ~68 and 98th-percentile vol, directly into a possible Fed hike the day after earnings. Every refinancing at 5.3–5.75% grinds AFFO; the dividend yields 130bp less than Treasuries; estimate revisions are flat, meaning analysts don't yet believe the raise story extends. A guidance-confirmation-only Q3 or a hawkish Oct 28 outcome retraces the pop toward $170–173, and a risk-off tape re-couples AMT to VNQ (-9.7%/3m) with 5–10% downside.
What would change our mind
- Q3 print raises FY26 AFFO guidance a third time AND management discloses concrete new-tenant (SpaceX or other) leasing — thesis of 'trap' is wrong, momentum is fundamental
- 10Y falls decisively below ~4.9% on a dovish Oct 28 FOMC, making the 16x AFFO multiple defensible
- Any signed SpaceX tower agreement with a major tower REIT within 3 months
- Conversely, for shorts: a clean break above the 52-week high on volume with rising estimates would invalidate the mean-reversion view
Since publication vs SPY · closed horizons are frozen
The full research everything the view rests on
Direct answer to the question asked
Where the edge would come from
What the price assumes
At ~$182 (~16.3x guided AFFO, ~26x forward P/E, ~3.9% yield), the price embeds: (1) SpaceX becoming a material new tower tenant, (2) Q3 on Oct 27 confirming the raised guidance and accelerating CoreSite, and (3) no adverse surprise from the Oct 28 FOMC. Consensus ~$215 average target (T4-sourced, weakly verified) implies the Street thinks the re-rating sticks.
Why the market may be wrong
The market priced a sector-wide demand option on an unsigned customer while sell-side estimate revisions stayed flat (FY27 EPS $7.01→$7.02 over a month) — price moved, numbers didn't. If Q3 merely confirms guidance rather than raising it again, or the Fed hikes/signals another hike on Oct 28, the speculative premium unwinds while the macro anchor (5%+ 10Y) reasserts itself. VNQ is -9.7% over 3 months while AMT is +6.2% — that divergence against its dominant driver is historically the kind that mean-reverts.
The one thing to watch
The scan signal and the fundamental signal are measuring different things: AMT's 'momentum' is really a 0.92-correlation echo of CCI's 15% SpaceX pop (1-month z-score only 0.23, 1-week return +8%), so the variable to watch is not AMT's price action but whether any SpaceX-related leasing or a third guidance raise shows up in the Oct 27 print — absent that, AMT reverts to trading as a 5.2%-Treasury proxy with a 130bp-negative yield spread.
Key evidence (10)
- 1-week return +7.96% vs 1-month z-score of only 0.23; 20d realized vol at 98th percentile of own year — event-driven, not regime momentum [price data, 2026-10-15]
- Trigger: SpaceX agreed Oct 8, 2026 to buy Grain Management's 800 MHz spectrum; ~$8B price is a media/analyst estimate, not disclosed; no SpaceX tower lease exists [T3 CNBC/Bernstein]
- AMT correlation to CCI 0.92 over 60 days; CCI +15% on the week vs AMT +8% — AMT is the diluted expression of the same story
- Q2 2026 (Jul 28): revenue $2.75B +4.6% y/y; FY26 AFFO guidance raised twice to $11.00–11.17; dividend $1.79/qtr; management cited reduced churn, margin expansion, record CoreSite [T1/T4 mix]
- Estimate revisions essentially flat: FY27 EPS $7.01→$7.02 over a month [T4, as of Sep 14, 2026]
- 10Y Treasury 5.19% (recent 5.34%, highest since 2002); Fed funds 3.75–4.00% with 17–35% odds of an Oct 28 hike [T2]
- AMT issued $1.6B senior notes Sept 2026 at 5.30%/5.56%/5.75% coupons, ~5.6% all-in cash cost [T1 8-K]
- Dividend yield ~3.9% is ~130bp below the risk-free rate; VNQ -9.7% over 3 months while AMT +6.2%
- Consensus 'Moderate Buy', average target ~$215 [T4 — weakly sourced, treat cautiously]
- Reported Q2 'EPS beat' of $2.71 vs $1.57 consensus likely includes nonrecurring items — unverified
Catalysts and risks
Catalysts
- CCI Q3 earnings Oct 21, 2026 — sector read-through on leasing/churn and any SpaceX commentary
- AMT Q3 2026 earnings Oct 27 pre-market — third guidance raise vs confirmation; churn, CoreSite, international FX
- FOMC decision Oct 28, 2026 — hike (17–35% priced) vs hold; guidance on further hikes
- FCC approval process for the SpaceX/Grain spectrum transfer
- Any announced SpaceX tower/rooftop leasing agreement
- 10Y Treasury trajectory toward/away from the 5.34% cycle high
Risks
- Binary event clustering: earnings then FOMC within 24 hours
- SpaceX thesis collapses if spectrum is used satellite-only — premium unwinds
- Refinancing at ~5.6% erodes AFFO growth; 2026–27 maturity schedule and net leverage unverified
- Flat sell-side revisions suggest the raise is already fully discounted
- High realized vol (98th percentile) means stop-outs and gap risk for a technical entry
- EchoStar/Dish-related churn in international/US portfolios remains a background risk
What to watch
- Oct 27 print: guidance raise vs confirmation; churn rate; CoreSite bookings; international FX drag
- Sell-side revisions in the 2 weeks after earnings — do FY27 estimates finally move?
- CCI's Oct 21 commentary as a sector tell (0.92 correlation)
- 10Y yield around the 5.34% high and the Oct 28 FOMC statement
- Any FCC filing or SpaceX network-deployment announcement
- Whether AMT's 0.92 correlation to CCI breaks — if AMT starts trading on its own fundamentals, the thesis changes
Market snapshot when the call was made 2026-10-14
Price
| Return 1w | +8.0% |
| Return 1m | +0.9% |
| Return 3m | +6.2% |
| Return 6m | +2.3% |
| Return 1y | +0.8% |
| From 52-week high | -6.7% |
| Realized vol, 20d | 37.7% |
| SPY 3m / 1y | +2.5% / +16.1% |
| QQQ 3m / 1y | +3.3% / +21.1% |
Technicals
AMT technicals as of 2026-10-14: last close $179.40; 20d SMA 170.62 (bearish); 50d SMA 172.96; 12d EMA 173.44; 26d EMA 172.30; RSI 14 67.6 (balanced); 20d vol 38.8%; volume x0.9 vs 20d avg
Sources (40 · T1 = primary filings)
- T1https://www.businesswire.com/news/home/20260909933334/en/American-Tower-Corporation-Prices-Senior-Notes-Offeri…
- T4https://www.stocktitan.net/news/AMT/
- T1https://www.businesswire.com/news/home/20260917258464/en/American-Tower-Corporation-Announces-Election-of-Kris…
- T1https://www.businesswire.com/news/home/20260527819282/en/American-Tower-to-Present-at-Nareits-REITweek-2026-In…
- T4https://www.stocktitan.net/sec-filings/AMT/8-k-american-tower-corp-ma-reports-material-event-ae90277c15ef.html
- T4https://www.thecerbatgem.com/2026/10/15/american-tower-corporation-amt-shares-acquired-by-fort-washington-inve…
- T4https://www.marketbeat.com/instant-alerts/filing-8679-american-tower-corporation-amt-shares-sold-by-mccollum-c…
- T1https://www.businesswire.com/news/home/20260728080275/en/American-Tower-Corporation-Reports-Second-Quarter-202…
- T2https://www.bloomberg.com/news/articles/2026-10-13/fed-s-williams-interview-with-bloomberg-news-full-transcrip…
- T2https://www.reuters.com/business/lower-us-treasury-yield-view-persists-despite-biggest-quarterly-surge-since-1…
- T2https://www.reuters.com/business/wall-st-futures-slip-yields-oil-rebound-fed-minutes-focus-2026-10-07/
- T4https://finance.yahoo.com/economy/policy/articles/us-treasury-yields-yet-peak-155219861.html
- T3https://www.cnbc.com/2026/10/14/us-treasury-yields-cpi-inflation-report.html
- T4https://www.rexshares.com/macro-monthly-october-2026-us-treasury-yield-assessment-and-top-10-factors/
- T4https://www.swissinfo.ch/eng/a-higher-rate-world-is-in-store-as-central-banks-approach-2027/92200921
- T3https://www.cnbc.com/2026/10/05/treasury-yields-bonds-fed-rates.html
- T1https://investor.crowncastle.com/
- T1https://investor.crowncastle.com/news
- T4https://finance.yahoo.com/markets/stocks/articles/crown-castle-soars-13-spacex-153427812.html
- T4https://www.investing.com/news/stock-market-news/why-is-crown-castle-stock-surging-today-93CH-4940941
- T4https://www.akm.ru/eng/news/american-crown-castle-sells-part-of-fiber-optic-business-for-8-5-billion/
- T4https://simplywall.st/stocks/us/real-estate/nyse-cci/crown-castle/news/crown-castle-stock-gains-attention-afte…
- T4https://finance.yahoo.com/markets/stocks/articles/crown-castle-cci-surges-15-121800163.html
- T4https://www.perplexity.ai/finance/CCI
- T1https://www.sec.gov/Archives/edgar/data/0001053507/000119312526390605/d156192d8k.htm
- T1https://www.sec.gov/Archives/edgar/data/1053507/000119312526390605/d156192d8k.htm
- T4https://finance.yahoo.com/markets/stocks/articles/american-tower-corporation-prices-senior-212800938.html
- T4https://www.theglobeandmail.com/investing/markets/stocks/AMT-N/pressreleases/4548288/american-tower-prices-1-6…
- T4https://www.marketbeat.com/stocks/NYSE/AMT/
- T4https://finance.yahoo.com/real-estate/articles/americans-cannot-stop-using-phones-151558569.html
- T4https://247wallst.com/investing/2026/10/08/two-reits-yield-over-4-one-is-a-dividend-machine-the-other-is-a-gam…
- T4https://247wallst.com/investing/2026/10/03/4-data-center-reits-that-pay-dividends-where-ai-boom-meets-steady-i…
- T3https://www.cnbc.com/2026/10/09/spacex-wireless-plans-lifts-tower-stocks.html
- T4https://www.business-standard.com/world-news/elon-musk-s-bigger-test-after-airwaves-is-building-costly-network…
- T4https://theinference.org/article/spacex-s-reported-8-billion-spectrum-buy-sent-tower-stocks-up-on-a-lease-that…
- T4https://finance.yahoo.com/technology/articles/elon-musks-spacex-could-shake-031048923.html
- T3https://www.morningstar.com/news/marketwatch/20261008478/spacexs-starlink-mobile-plans-are-pressuring-att-and-…
- T4https://finance.yahoo.com/markets/stocks/articles/atex-nn-gogo-stocks-gain-181048549.html
- T4https://www.galvnews.com/news_reuters/business/us-european-telecom-stocks-slide-as-spacex-spectrum-deal-rattle…
- T4https://www.investing.com/news/analyst-ratings/stifel-reiterates-spacex-stock-rating-on-spectrum-deal-satellit…
Want a fresh look at AMT, or another name?
Queue a new deep-research run. Published to the feed when done.
Automated research opinion, published as-is on Oct 15, 2026. Not personalised advice. Figures use end-of-day closes.