Reset, not broken — lean bullish.
Thesis
Bull case
The earnings line never broke: 32–35% guided revenue growth, rule-of-40 score of 70 for the 19th straight quarter, rising 2027 estimates, and improving credit. At ~21x forward (~18.5x 2027) versus a 5-year median trailing P/E of ~42x, even a partial re-rating toward the high-20s multiple on in-line execution yields 30–45% upside, consistent with the $22 mean target. Catalysts are identifiable: a Q3/Q4 print that finally raises the EBITDA or EPS line, evidence the December Fed meeting ends the hiking cycle, or continued peer recovery forcing SOFI's correlation discount to close. Deposit-funded model and 69% origination growth give it more resilience than warehouse-funded peers like UPST.
Bear case
The de-rating is rational: SOFI has twice raised revenue guidance while refusing to raise profit guidance, implying structural earnings-conversion problems — heavy marketing spend, rising deposit/funding costs in a hiking cycle, and a 700bp tax headwind. The Technology Platform's ~27% decline guts the 'diversified fintech platform' premium that justified 48x. Headline credit is flattered by selling late-stage delinquent loans (3.7% economic vs 2.62% reported charge-offs), and GAAP earnings (~$0.39) are roughly half the adjusted figures the 21x multiple is computed on — on GAAP, the stock is at ~39x trailing with FY25 net income actually down year over year. Into a December hike with 2.3–3.4 beta, another leg down to the $15 low-target zone requires no company-specific bad news at all.
What would change our mind
- FY26 adjusted EBITDA guidance (~$1.6B) or EPS guidance (~$0.60) is cut at the next print — this converts the thesis from multiple compression to deterioration
- All-in personal-loan charge-offs (ex-loan-sales) rise back above ~4.4% or management lifts the 7–8% max cumulative loss assumption
- 2027 EPS consensus breaks below ~$0.80 on net downward revisions
- Two or more Fed hikes materialize by Q1 2027 with CPI re-accelerating — the macro leg of the re-rating case fails
- Stock breaks below the $14.30 area (52w low, ~6% below current) on heavy volume — the 'coil resolves up' assumption fails
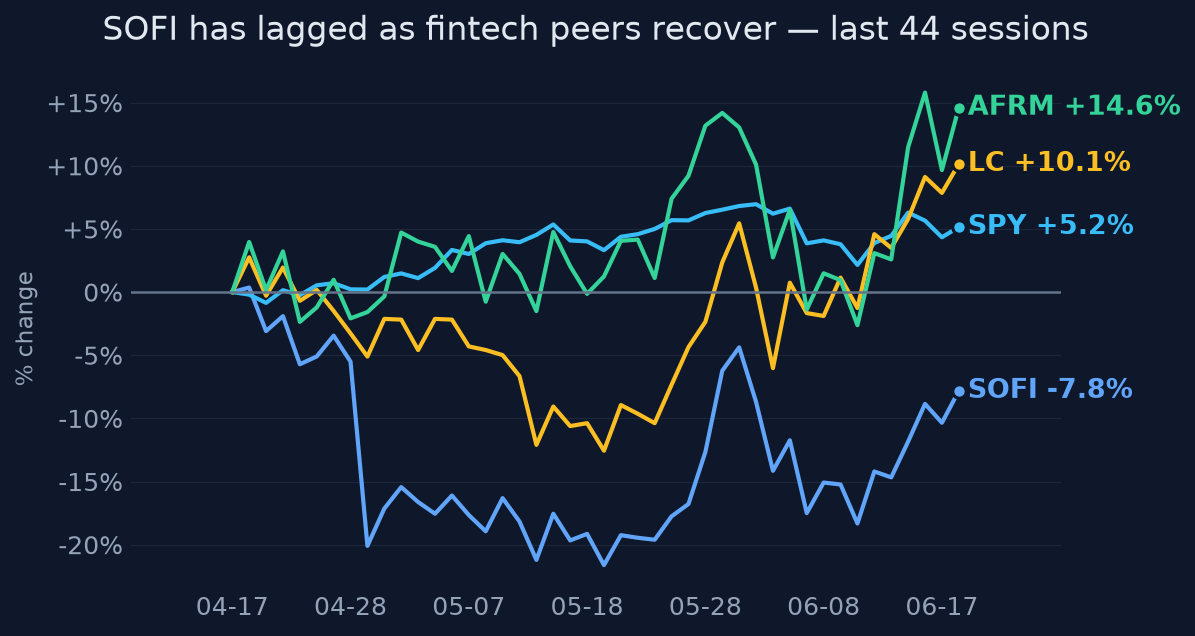
Since publication vs SPY · closed horizons are frozen
The full research everything the view rests on
Direct answer to the question asked
Where the edge would come from
What the price assumes
At $15.26 (~21x 2026 consensus EPS of ~$0.59, ~18.5x 2027's $0.82), the price assumes the de-rating is at least partly permanent: that revenue growth will keep failing to convert into earnings, that 'higher for longer' rates compress NIM and funding economics, and that the Technology Platform decline signals the diversification premium was undeserved. Consensus rating is Hold with a wide target range ($15–$35), i.e., the street itself is undecided.
Why the market may be wrong
The selloff's magnitude is disproportionate to the evidence: FY26 revenue guidance was RAISED twice this year, 2027 EPS consensus rose ~1.4% over 90 days, Q2 personal-loan charge-offs fell 41bp QoQ and 90-day delinquencies fell 7bp, and management maintained its 7–8% max cumulative vintage loss assumption. Meanwhile LendingClub (+39% over 3m) and Affirm (+26% over 6m) have recovered from the same sector shock while SOFI has not — the de-rating has become SOFI-specific sentiment rather than sector or credit fundamentals. Recent analyst actions (Benchmark Strong Buy Oct 12, StoneX Buy initiation $25 PT Oct 13) suggest the marginal informed view is turning.
The one thing to watch
This is multiple compression with a rising earnings line, not a deteriorating business — so the variable to watch is not revenue growth (already 32–35% guided) but the EBITDA/EPS guidance line: SOFI has beaten and raised revenue twice in 2026 while holding EBITDA at ~$1.6B and EPS at ~$0.60, and the stock fell both times. The single print that changes the thesis is the first guidance raise on the profit line, because that is precisely the conversion doubt the 46% discount is pricing.
Key evidence (9)
- Price: -45.9% 1y, -53% below 52w high, -10.4% 1m vs SPY +16.5% 1y; 60d beta to SPY 3.4, ~50% idiosyncratic variance; 20d realized vol at 14th percentile of past year (coiling) [market data, 2026-10-16]
- Forward P/E compressed from ~48x (Sep 2025) and ~29x (Mar–Jun 2026) to ~21x (Oct 2026) while 2027 EPS consensus rose from $0.8127 to $0.8240 over 90 days [T4 Zacks/Yahoo aggregation — valuation history rests partly on T4]
- Q2 2026 (reported Jul 29): adj. revenue $1.20B +40% YoY (beat $1.11B consensus), adj. EBITDA $358M at 30% margin, net income +61% YoY, adj. EPS $0.12 vs $0.11 est.; FY26 revenue guidance raised to $4.75–4.85B but EBITDA held at ~$1.6B and EPS at ~$0.60, partly on a 700bp higher tax assumption [T1 company release]
- Credit improved: Q2 headline personal-loan charge-off rate 2.62% (-41bp QoQ), all-in ex-loan-sales estimate 3.7% (down from ~4.4% in Q1), 90-day delinquency 40bp (-7bp QoQ), 7–8% max vintage loss assumption maintained [T1/T4]
- Quality-of-earnings flag: ~$90M of late-stage delinquent loans sold in Q2 flatters the headline 2.62% charge-off figure; FY25 GAAP net income $481M was slightly below FY24's $499M [T1 SEC XBRL/T4]
- Technology Platform adjusted revenue down ~27% YoY to ~$75M, revenue per account -14%; named lost clients not confirmed in any filing [T4 — rests on general finance coverage, treat cautiously]
- Macro: Fed hiked Sep 2026 to 3.75–4.00% target; CPI 3.7% YoY; base case hold in October, possible December hike; SOFI guidance now embeds 1–2 hikes vs. cuts previously assumed [T2 Reuters]
- Peers diverging: UPST -51% 1y (SOFI trades at 0.81 correlation to it), but LC +38.7% over 3m and AFRM +26% over 6m — sector shock is fading while SOFI remains at lows [computed from price history]
- Street: consensus Hold, mean PT ~$22.20 (range $15–$35); Benchmark upgraded to Strong Buy Oct 12; StoneX initiated Buy with $25 PT Oct 13 [T3 CNBC/T4 aggregators]
Catalysts and risks
Catalysts
- Q3 2026 earnings (expected late Oct/early Nov 2026; the next confirmed report date in the data is Jan 28, 2027 for Q4 — timing should be verified): the key tell is whether EBITDA/EPS guidance is raised, not revenue
- FOMC meetings Oct 27–28 and December 2026: a confirmed end to hikes removes the macro overhang; a surprise hike hits a 3.4-beta stock hard
- Q4 2026 report Jan 28, 2027 (consensus EPS est. $0.19, revenue ~$1.34B) and any preliminary FY27 guidance
- Monthly/periodic credit disclosures: any break in the 7–8% max cumulative vintage loss assumption
- Further analyst re-ratings following Benchmark's Strong Buy and StoneX's $25 initiation
Risks
- Fed hikes December (or more) — funding costs, NIM pressure, fair-value marks, and multiple compression on a 2.3–3.4 beta name
- Third consecutive revenue-beat-without-profit-raise entrenches the earnings-conversion narrative
- Credit normalization: all-in economic charge-offs (3.7%) rise toward the 7–8% vintage loss ceiling as loan sales stop flattering headlines
- Technology Platform decline accelerates, removing the diversification argument
- GAAP vs adjusted earnings gap (~2x) invites a re-anchor of the multiple on GAAP numbers
- 20d volatility at the 14th percentile — the coil can resolve downward in a macro shock
What to watch
- The profit guidance line at the next earnings print — EBITDA/EPS raise vs. hold is the single decisive data point
- SOFI's correlation to UPST (0.81): a break lower while peers (LC, AFRM) keep recovering would signal the market is re-underwriting SOFI on its own fundamentals
- Q3 credit disclosures: charge-offs excluding late-stage delinquent loan sales, and the dollar volume of such sales
- December FOMC and November/December CPI prints
- Technology Platform revenue trajectory and any named enterprise client wins/losses
- Estimate revision breadth (currently 5 up / 2 down over 30 days) and whether the $15 low target (GS) gets revised
Market snapshot when the call was made 2026-10-15
Price
| Return 1w | -3.3% |
| Return 1m | -10.4% |
| Return 3m | -12.7% |
| Return 6m | -20.7% |
| Return 1y | -45.9% |
| From 52-week high | -53.1% |
| Realized vol, 20d | 42.1% |
| SPY 3m / 1y | +3.8% / +16.5% |
| QQQ 3m / 1y | +4.7% / +21.7% |
Technicals
SOFI technicals as of 2026-10-15: last close $15.09; 20d SMA 15.94 (bearish); 50d SMA 17.16; 12d EMA 15.47; 26d EMA 16.10; RSI 14 32.1 (balanced); 20d vol 41.2%; volume x1.3 vs 20d avg
Next earnings: 2027-01-28 AMC
Verifier notes PASS
Weakly sourced
- Bear case claim that 'on GAAP, the stock is at ~39x trailing' — this is defensible only as price ($15.26) divided by FY25 GAAP EPS ($0.39); the evidence bundle's valuation snapshot reports a current trailing P/E of 31.8x, implying TTM GAAP EPS nearer ~$0.48. The 39x figure should be relabeled 'on FY25 GAAP EPS' or reconciled with the 31.8x trailing figure; the underlying GAAP-vs-adjusted gap point is unaffected.
Corrections applied
- Reword the bear-case GAAP multiple to 'at ~39x FY25 GAAP EPS ($0.39), and ~32x on a trailing basis' to remove the conflict with the evidence's 31.8x trailing P/E while preserving the GAAP/adjusted gap argument.
Sources (31 · T1 = primary filings)
- T4https://www.theglobeandmail.com/investing/markets/stocks/SOFI/pressreleases/3729955/sofi-sofi-q2-2026-earnings…
- T3https://www.morningstar.com/news/business-wire/20260729569583/sofi-reports-second-quarter-2026-with-record-net…
- T4https://www.benzinga.com/trading-ideas/movers/26/10/62337151/sofi-stock-slides-whats-going-on
- T1https://www.sec.gov/Archives/edgar/data/1818874/000181887426000020/a2026q1earningsrelease.htm
- T4https://finance.yahoo.com/quote/SOFI/earnings/SOFI-Q2-2026-earnings_call-656821.html?fr=sycsrp_catchall
- T1https://www.sec.gov/Archives/edgar/data/1818874/000181887426000050/a2026q2earningsrelease.htm
- T4https://247wallst.com/investing/2026/10/15/sofi-technologies-imploded-in-2026-a-wall-street-pro-predicts-it-wi…
- T2https://www.reuters.com/company/sofi-technologies-inc/
- T4https://247wallst.com/investing/2026/10/14/sofi-falls-6-despite-stonex-buy-initiation-as-rising-yields-hit-fin…
- T4https://pluang.com/en/news-feed/sofi-turun-6-persen-meski-inisiasi-beli-stonex-yield-naik-tekan-fintech-affirm
- T4https://www.perplexity.ai/finance/SOFI?comparing=SOFI,AFRM,TREE,LC,NRDS,RUM
- T4https://finance.yahoo.com/markets/stocks/articles/stock-market-today-oct-14-215817008.html
- T4https://www.perplexity.ai/finance/SOFI?comparing=SOFI,EZPW,SYF,NRDS,AFRM,BETR
- T4https://www.diamond-hill.com/insights/a-939/infographics/securitization-in-focusmdashaugust-2026/
- T4https://breakoutshappen.com/stock/AFRM
- T2http://rmb.reuters.com/rmd/rss/item/tag:reuters.com,2026:newsml_KBN3VU1SN?channel=frL012
- T2http://rmb.reuters.com/rmd/rss/item/tag:reuters.com,2026:newsml_KBN3VU1ST?channel=frL012
- T2https://www.reuters.com/5f374b32b07b/world/feds-williams-currently-sees-no-need-rate-hike-2027-bloomberg-news-…
- T2https://www.reuters.com/markets/us/fed-rate-hike-seen-more-likely-after-inflation-data-2026-10-14/
- T2https://www.reuters.com/business/fed-seen-skipping-october-rate-hike-job-market-cools-2026-10-02/
- T4https://www.theasianbanker.com/updates-and-articles/fed-raises-rates-for-first-time-since-2023-as-inflation-ou…
- T4https://finance.yahoo.com/economy/policy/articles/feds-collins-sees-another-rate-200122592.html
- T3https://www.cnbc.com/2026/10/14/fed-may-now-have-to-hike-twice-or-increase-by-a-half-point-in-december-traders…
- T4https://www.pricetargets.com/NASDAQ/SOFI/
- T3https://www.cnbc.com/2026/10/13/sofi-stock-stonex-buy-rating.html
- T4https://www.marketbeat.com/instant-alerts/analyst-sofi-technologies-nasdaq-sofi-upgraded-at-benchmark-2026-10-…
- T4https://stockanalysis.com/stocks/sofi/
- T4https://www.marketbeat.com/stocks/NASDAQ/SOFI/forecast/
- T4https://public.com/stocks/sofi/forecast-price-target
- T4https://finance.yahoo.com/quote/SOFI/analyst-insights/
- T4https://www.thecerbatgem.com/2026/10/14/sofi-technologies-nasdaqsofi-raised-to-strong-buy-at-benchmark.html
Want a fresh look at SOFI, or another name?
Queue a new deep-research run. Published to the feed when done.
Automated research opinion, published as-is on Oct 16, 2026. Not personalised advice. Figures use end-of-day closes.