Lean bullish — cautiously.
Thesis
Bull case
The guidance reset alone is a near-mechanical catalyst: Q1'27 revenue guided at $33-37B vs ~$22B consensus forces FY27 estimate revisions of +50% or more over the next two quarters, making the current price embed a multiple off numbers everyone knows are wrong. The Q4 print (~Jan 2027) plus any SI customer/contract disclosure confirming external, take-or-pay, cash-paying demand removes the circularity discount that the sector selloff applied indiscriminately. Unlike CoreWeave, SPCX has $4.4B of quarterly net income, a +69% profitable Starlink business, and launch dominance as ballast. Management's ARR commentary ($100B by end-2026; $500B-1T discussed for end-2027), if even partially delivered, reframes the company as the largest AI compute platform, not a neocloud.
Bear case
Free cash flow is approximately -$25B on an H1 run-rate with Q4 capex guided to $35-40B — the buildout cannot be internally funded and the stack already includes $25B of notes and >$20B of lease obligations, some engineered as failed sale-leasebacks through xAI-related entities, the exact related-party circularity the market is punishing. SI revenue (52% of the quarter) has no disclosed customer list, duration, or take-or-pay terms; growth is partly attributed to cloud agreements and the Cursor integration, so captive xAI demand may be inflating it. Net income ($4.4B) exceeded operating income ($2.8B), implying large non-operating/fair-value gains in the headline. At $2.1T, any forced equity raise at depressed levels is dilutive, and a continued AI-infra de-rating (CoreWeave credit spiral, rate hikes) drags SPCX regardless of its print. FY26 'consensus' of ~$0.01 EPS also warns the sell-side has no working model — price discovery is poor in both directions.
What would change our mind
- Q4 2026 revenue comes in materially below the guided Q1'27 trajectory (e.g., <$28B annualized run-rate) — guidance was promotional, thesis dead
- SI disclosures show majority of segment revenue from xAI/related parties or short-duration cancelable contracts
- An equity raise of >$20B at or below current prices, confirming internal funding inadequacy
- FY27 consensus fails to migrate toward guidance within ~6 weeks of the Q4 print — analysts themselves don't believe it
- FCF deterioration beyond ~-$30B on an H2 annualized basis with no stated path to funding-gap closure
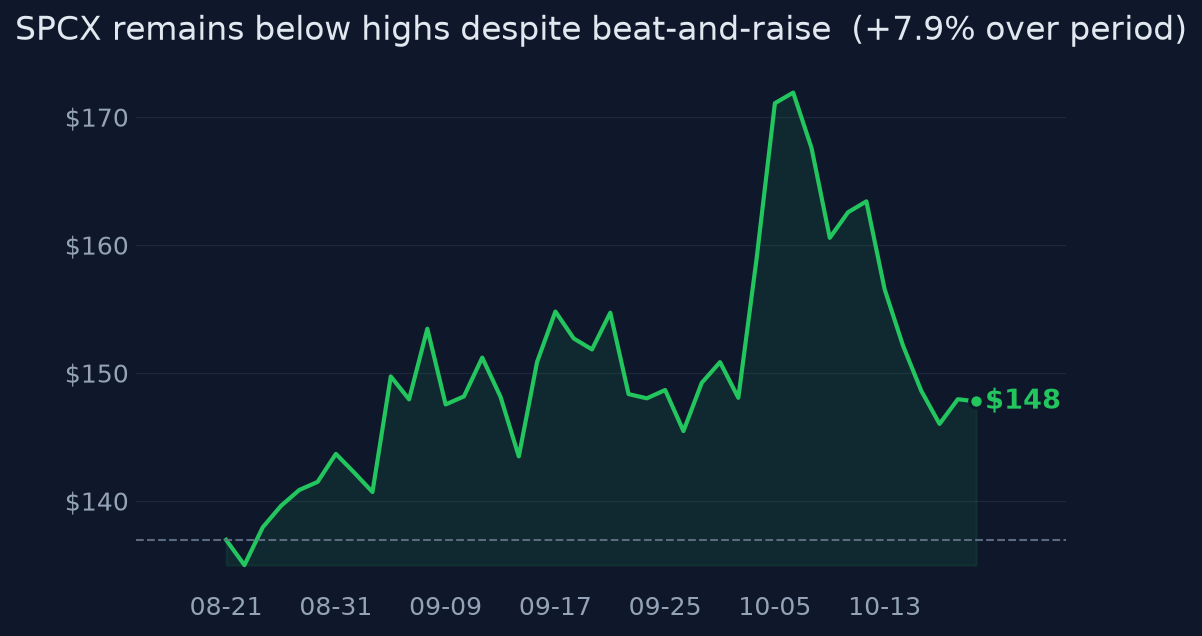
Since publication vs SPY · closed horizons are frozen
The full research everything the view rests on
Direct answer to the question asked
Where the edge would come from
What the price assumes
At ~$2.1T market cap and -14% off the 52-week high, the price assumes the Q3 surge is substantially non-recurring: that Super Intelligence revenue is partly captive/circular (xAI internal demand, Cursor integration), that the $19.6B quarterly capex run-rate (84% SI) will keep FCF deeply negative (~-$25B H1'26), and that funding it requires continued debt issuance ($25B notes, >$20B lease obligations) and eventual dilutive equity raises. The stock is trading as a high-beta AI-infra proxy (moved tick-for-tick with NVDA; 2.33 beta to SPY but only 0.48 correlation), not on its own fundamentals.
Why the market may be wrong
Two ways. First, the published consensus is stale garbage — FY26 EPS ~$0.01 versus a single guided quarter of $33-37B revenue — so the mechanical act of revising estimates upward over the next two quarters is a catalyst that needs no operational improvement, only confirmation. Second, the selloff was sector-wide (rate-hike bets + CoreWeave credit stress, its 2031 bonds >16% yield), not a verdict on SPCX's print: SPCX actually has what CoreWeave lacks — two profitable non-AI businesses and $4.4B of quarterly net income. If SI revenue proves external, the 'circular revenue' discount is misapplied.
The one thing to watch
Stop watching the P/E — it is computed off a consensus ($45B FY26 revenue) that management's own guidance for a single upcoming quarter ($33-37B) already contradicts. The variable to watch is the FY27 consensus revision rate between now and the Q4 print: if estimates migrate toward guidance while the stock stays ~15% below its high, you are seeing forced multiple expansion-by-arithmetic, not sentiment recovery. The one disclosure that settles the thesis either way is the SI segment's customer list and contract terms (external vs xAI-captive) — that, not the headline growth rate, determines whether SPCX deserves the CoreWeave discount.
Key evidence (8)
- Q3 2026 (reported Oct 20, 2026): revenue $14.58B vs $12.7B Bloomberg consensus (+161% YoY); GAAP EPS $0.35 vs ~$0.10-0.15; adj. EBITDA $8.81B (+306%); net income $4.4B vs -$1.1B LY [T1 SEC/T2 Bloomberg via earnings summaries]
- Guidance: Q1 2027 revenue $33-37B vs ~$22.2B consensus; Q4 2026 capex $35-40B [T4 transcript summaries — treat as approximate until verified against the 8-K]
- Super Intelligence (AI) revenue $7.56B in Q3, +830% YoY, larger than launch + Starlink combined; $16.4B of $19.6B Q3 capex (84%) went to SI [T1 SEC per coverage; NYT-cited figure]
- Funding: $25B five-tranche notes June 2026; >$20B AI-infrastructure lease obligations, some failed sale-leasebacks recorded as debt, involving xAI-related entities and Valor [T1 SEC R20/R21 per coverage]; H1'26 OCF ~$3.5B vs ~$28.5B capex ≈ -$25B FCF [T4 secondary, unverified]
- Starlink/connectivity revenue $5.25B (+69%), 13.6M subs, ~$2.37B segment operating income; consumer adds 1.6M missed ~2.29M expected [T2/T4]
- xAI merger Feb 2026 at ~$1.25T combined; xAI holders received 0.1433 SPCX shares [T2 Reuters/Bloomberg]; Tesla holds $2B stake [T2]
- Price/quant: $159.31 reference (Oct 21, 2026); -14% below 52w high; realized vol ~46-52%; beta 2.33 to SPY but correlation 0.48 (~76% idiosyncratic variance); fell ~10% the prior week in a broad AI-infra selloff with NVDA [computed]
- CoreWeave as sector cautionary tale: ~$50B debt, 2031 bonds yielding >16%, CDS implying extreme default risk, Nvidia backstopping unsold capacity through 2032 [T2 Reuters, Oct 2026]
Catalysts and risks
Catalysts
- Q4 2026 earnings (~Jan 2027) — first test of the $33-37B Q1'27 guidance trajectory
- Publication of the full 10-Q/8-K with SI segment customer identities, contract durations, and take-or-pay terms
- FY27 consensus revision cycle through Nov 2026-Jan 2027
- Any equity/debt raise announcement (size, pricing, dilution)
- CoreWeave credit developments and AI-infra sector sentiment (rate decisions)
- Starship weekly-cadence milestones and V3 Starlink deployments through H1 2027
- Management's end-2026 ~$100B ARR confirmation
Risks
- SI revenue proves largely captive/circular (xAI internal demand) — CoreWeave-style de-rating applies directly
- Forced dilutive equity raise to fund the $35-40B Q4 capex at a depressed price
- Net income inflated by non-operating/fair-value gains (NI > OI); quality of earnings disappoints under 10-Q scrutiny
- Continued sector-wide AI-infra selloff driven by rates/credit, independent of company execution
- Key facts rest on T4 transcript summaries and secondary sources; guidance figures may be misquoted
- Consumer Starlink adds missed (1.6M vs 2.29M expected) — the 'safe' business is decelerating at the margin
- Extreme realized vol (~46-52%) makes position sizing the primary risk control
What to watch
- FY27 consensus revenue/EPS revision rate weekly through January
- SI segment customer/contract disclosures in the 10-Q (external share, duration, take-or-pay)
- Cash collections vs booked SI revenue (receivables build, deferred revenue)
- Any debt/equity raise terms and Tesla/xAI related-party transaction expansions
- CoreWeave bond yields/CDS as the sector circularity barometer
- Q4 capex vs the $35-40B guide and the split between SI and core segments
- Starlink consumer net adds vs the ~2.3M/quarter expectation
Market snapshot when the call was made 2026-10-21
Price
| Return 1w | -5.6% |
| Return 1m | -2.7% |
| From 52-week high | -14.0% |
| Realized vol, 20d | 51.6% |
| SPY 3m / 1y | +2.9% / +15.8% |
| QQQ 3m / 1y | +1.7% / +18.8% |
Technicals
SPCX technicals as of 2026-10-21: last close $159.31; 20d SMA 155.24 (bullish); 50d SMA 149.14; 12d EMA 154.01; 26d EMA 153.14; RSI 14 58.1 (balanced); 20d vol 57.3%; volume x2.4 vs 20d avg
Sources (29 · T1 = primary filings)
- T2https://www.reuters.com/business/media-telecom/spacex-quarterly-revenue-surges-debut-results-strong-growth-its…
- T3https://www.cnbc.com/2026/10/20/spacex-spcx-earnings-live-updates-q3-2026html.html
- T1https://www.sec.gov/Archives/edgar/data/1181412/000162828026066482/spaceexplorationtechnologi.htm
- T1https://www.sec.gov/Archives/edgar/data/1181412/000162828026052515/earningsreleaseq22608042.htm
- T4https://fortune.com/2026/10/20/spacex-q3-profit-ai-si-elon-musk/
- T3https://www.cnbc.com/2026/10/20/spacex-spcx-earnings-live-updates-q3-2026html.html?taid=92985b00-d579-476b-92f…
- T4https://www.nytimes.com/2026/10/20/technology/spacex-earnings-elon-musk.html
- T3https://www.marketwatch.com/investing/stock/spcx/financials/secfilings?docid=19861088&eafs_enabled=false
- T2https://www.reuters.com/legal/transactional/spacex-reveals-musk-company-links-cybertrucks-jets-stock-investmen…
- T2https://www.reuters.com/business/media-telecom/spacex-quarterly-revenue-jumps-beats-estimates-ai-business-surg…
- T1https://www.sec.gov/Archives/edgar/data/1318605/000162828026026673/R20.htm
- T4https://money.usnews.com/investing/news/articles/2026-05-20/spacex-reveals-musk-company-links-from-cybertrucks…
- T2https://www.reuters.com/business/musks-spacex-merge-with-xai-combined-valuation-125-trillion-bloomberg-news-20…
- T4https://www.techi.com/quote/SPCX/financials/
- T1https://www.sec.gov/Archives/edgar/data/1318605/000162828026049270/R21.htm
- T4https://mizanrsharif.substack.com/p/spacex-third-quarter-2026-performance
- T4https://www.investmentnews.com/equities/spacex-delivered-a-blockbuster-quarter-advisors-should-keep-an-eye-on-…
- T4https://finance.yahoo.com/technology/ai/articles/spacex-shares-jump-ai-revenue-174147007.html
- T4https://finance.yahoo.com/markets/stocks/articles/spcx-rises-hours-ai-driven-210456555.html
- T4https://finance.yahoo.com/markets/article/elon-musks-spacex-is-now-mostly-an-ai-company-chart-of-the-day-10000…
- T4https://www.teslarati.com/spacex-spcx-delivers-blockbuster-q3-results-super-intelligence-booms/
- T4https://letsdatascience.com/news/topic/ai-infrastructure
- T2https://www.reuters.com/legal/transactional/why-coreweave-is-crosshairs-ai-scare-2026-10-16/
- T2https://www.reuters.com/legal/transactional/coreweaves-ai-contracts-lenders-financing-its-build-out-2026-10-15…
- T2https://www.reuters.com/business/ai-infrastructure-firms-slump-us-rate-hike-bets-rise-2026-10-14/
- T4https://fourweekmba.com/ai-huang-coreweaves-cost-of-capital-is-falling-no-backstop/
- T4https://thisweekinnvidia.substack.com/p/insight-on-nvidia-16-october-2026
- T4https://corevaluequest.com/2026/10/12/coverage-brief-2026-10-12/
- T2https://www.reuters.com/legal/transactional/wall-st-week-ahead-ai-rally-wobbles-stock-markets-spotlight-turns-…
Earlier and later calls on SPCX
- Aug 11, 2026Great company, not yet a clean buy.Lean bullish
Want a fresh look at SPCX, or another name?
Queue a new deep-research run. Published to the feed when done.
Automated research opinion, published as-is on Oct 22, 2026. Not personalised advice. Figures use end-of-day closes.