Mostly yes — but it's a multiple story.
Thesis
Bull case
Volume-led +4% organic growth across all categories and regions is the highest-quality print PG has delivered in years; if guidance proves conservative (Q1 already runs above the 1-3% guide) and H2 accelerates as management suggested, estimates rise into a defensible 23x while the defensive bid persists under sticky inflation and a hawkish Fed.
Bear case
The entire month of outperformance is multiple expansion for defensiveness: margins are contracting, the cost headwind grew 40%, EPS estimates are drifting down, and guidance caps core EPS growth at 3%. At the top half of its historical multiple with a 0.38 beta, PG lags any risk-on tape and de-rates hard if yields retreat.
What would change our mind
- For a constructive stance: Q2 organic volume falls below ~1% or core gross margin declines another 100bps+ despite productivity claims
- For a cautious stance: Q2 organic growth holds ≥3% with volume ≥2% AND management raises core EPS guidance — then the multiple is justified and estimates inflect up
- Regime check: if the 10-year yield breaks meaningfully below ~4.5%, assume the rotation premium unwinds regardless of company news
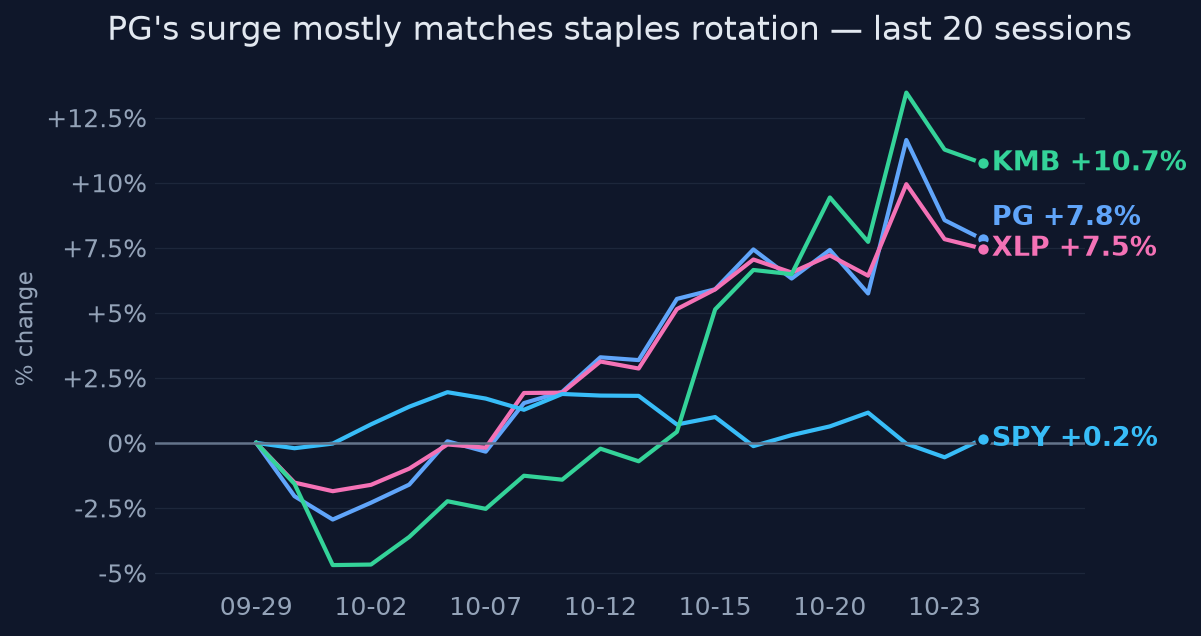
Since publication vs SPY · closed horizons are frozen
The full research everything the view rests on
Direct answer to the question asked
Where the edge would come from
What the price assumes
At ~22.6-23x FY27 consensus EPS of ~$6.97, the price assumes the defensive rotation persists and that PG's 4% organic growth is the start of an upward trajectory rather than a one-quarter print above the company's own 1-3% guide. Consensus already sits at the guidance midpoint, so the price embeds confidence that estimates won't be cut further despite the raised cost headwind.
Why the market may be wrong
Two-sided. Bears could be wrong because Q1 volume-led growth across all 10 categories and regions suggests pricing power and share gains that make 1-3% guidance look sandbagged — if H2 accelerates as management hinted, EPS estimates drift up into a 23x multiple, which is tolerable. Bulls could be wrong because the whole premium rests on a macro regime (~5% 10-year, hawkish Fed) that PG doesn't control; if yields retreat and risk-on resumes, PG's 0.38 beta and negative recent correlation to SPY mean it underperforms mechanically regardless of fundamentals.
The one thing to watch
PG is currently trading as an XLP proxy with an earnings overlay (60-day correlation 0.84, only 29% idiosyncratic share) — so the variable that actually moves the stock over the next 3-6 months is the 10-year Treasury yield, not anything PG reports until January. Watch yields for the direction; watch Q2 organic volume for whether the multiple is justified at all.
Key evidence (6)
- Q1 FY27 (reported Oct 22, 2026): core EPS $2.00 vs ~$1.88-1.89 est; net sales $23.28B vs ~$22.7-22.8B est; organic sales +4.0% with +2.4% volume, +0.4% price [T3 CNBC; T4 PG IR]
- Core gross margin -150bps; core operating margin 25.9% (-80bps); after-tax cost headwind raised from $1.0B to $1.4B [T4 investing.com slides]
- FY27 guidance maintained: organic sales +1-3%, core EPS +0-3% ($6.89-$7.11); all-in sales raised to 2-4% only due to Thorne acquisition scope change [T4]
- PG +9.4% 1m (1.6-sigma event) vs XLP +7.2%, CL +8.2%, KMB +11.4%, SPY -0.8%, QQQ -4.3%; PG-XLP 60d correlation 0.84, idiosyncratic share 29% [computed price data]
- Forward P/E ~22.6-23x, upper-middle of 10-year range (17.6-28.8x); FY27 EPS consensus drifted from $7.02 to $6.97 over 3 months [T3 MarketWatch, T4]
- Macro: 10-year yield ~5% after largest quarterly rise since 1994; Fed on hold at 3.75-4.00% with possible December hike; retail sales ex-gas/autos +0.1%; consumer sentiment near record low [T2 Reuters]
Catalysts and risks
Catalysts
- Fiscal Q2 FY27 earnings (~late January 2027) — organic volume growth vs the 1-3% guide
- December FOMC meeting — a hike extends the defensive bid; a dovish turn unwinds it
- 10-year Treasury trajectory — the actual driver of PG's relative performance
- Analyst estimate revisions as the $1.4B cost headwind is absorbed into FY27/28 models
Risks
- Yield retreat / risk-on rotation — PG mechanically underperforms with beta 0.38 and negative recent SPY correlation
- Q1 organic growth was pull-forward or timing-flattered and Q2 reverts toward 1%
- Margin pressure persists beyond the $1.4B headwind, forcing EPS guidance cuts in January
- Consensus revenue ($88.8B) already sits above guidance ($86.0-87.7B), creating room for downward estimate pressure
What to watch
- Q2 FY27 organic sales growth, volume component specifically (~late Jan 2027)
- 10-year Treasury yield and Dec FOMC outcome
- FY27 EPS consensus revisions ($6.97 today, from $7.02 three months ago)
- Core gross margin trajectory vs the $1.4B cost headwind
- PG/XLP relative strength — whether PG starts trading on its own story or stays a sector proxy
Market snapshot when the call was made 2026-10-26
Price
| Return 1w | +1.4% |
| Return 1m | +9.4% |
| Return 3m | +7.4% |
| Return 6m | +8.6% |
| Return 1y | +8.2% |
| From 52-week high | -3.4% |
| Realized vol, 20d | 28.6% |
| SPY 3m / 1y | +3.3% / +13.9% |
| QQQ 3m / 1y | +5.4% / +16.6% |
Technicals
PG technicals as of 2026-10-26: last close $159.92; 20d SMA 153.30 (bullish); 50d SMA 148.67; 12d EMA 157.55; 26d EMA 153.73; RSI 14 67.6 (balanced); 20d vol 28.8%; volume x0.9 vs 20d avg
Sources (16 · T1 = primary filings)
- T4https://us.pg.com/newsroom/news-releases/PG-Announces-Fiscal-Year-2027-First-Quarter-Results/
- T3https://www.cnbc.com/2026/10/22/procter-gamble-pg-q1-2027-earnings.html
- T4https://finance.yahoo.com/markets/stocks/articles/procter-gamble-q1-earnings-call-220417929.html
- T4https://finance.yahoo.com/markets/stocks/articles/pg-q1-earnings-call-highlights-130000792.html
- T4https://cranberryjournal.com/business/pg-price-up-point-four/
- T4https://in.investing.com/news/stock-market-news/pg-q1-fy-2027-slides-organic-sales-jump-4-margins-under-pressu…
- T4https://www.investing.com/news/company-news/pg-q1-fy-2027-slides-organic-sales-jump-4-margins-under-pressure-9…
- T4https://uk.investing.com/news/stock-market-news/pg-q1-fy-2027-slides-organic-sales-jump-4-margins-under-pressu…
- T2https://www.reuters.com/business/fed-hit-pause-rate-hikes-maybe-not-long-2026-10-26/
- T2https://www.reuters.com/business/lower-us-treasury-yield-view-persists-despite-biggest-quarterly-surge-since-1…
- T2https://www.reuters.com/business/fed-skip-october-raise-rates-again-december-nearly-all-economists-say-2026-10…
- T2http://rmb.reuters.com/rmd/rss/item/tag:reuters.com,2026:newsml_KBN3VP1LL?channel=FBi345
- T2http://rmb.reuters.com/rmd/rss/item/tag:reuters.com,2026:newsml_KBN3W30JE?channel=FBi345
- T2https://www.reuters.com/business/us-retail-sales-beat-expectations-september-higher-gasoline-prices-2026-10-15…
- T2http://rmb.reuters.com/rmd/rss/item/tag:reuters.com,2026:newsml_KBN3VV1TO?channel=FES376
- T2http://rmb.reuters.com/rmd/rss/item/tag:reuters.com,2026:newsml_KBN3VV1TO?channel=frL012
Want a fresh look at PG, or another name?
Queue a new deep-research run. Published to the feed when done.
Automated research opinion, published as-is on Oct 27, 2026. Not personalised advice. Figures use end-of-day closes.