Real activity — but stalling.
Thesis
Bull case
The fee switch is a genuine, irreversible-seeming tokenomics upgrade with unanimous governance support (46M+ UNI for, ~0 against on recent votes), zero unlock overhang, and a growing institutional wrapper (CME futures, SMBC Nikko/Nethermind Japan v4 venue targeting 2027). TVL is rising (+30%/90d), Unichain's OP Enterprise migration lands late October, and if the 30d fee decline proves seasonal or mix-driven rather than share loss, annualized revenue of ~$105M against a $4.6B mcap with an expanding burn could restart the re-rating — UNI is still 27% below its 52w high and 83% below ATH.
Bear case
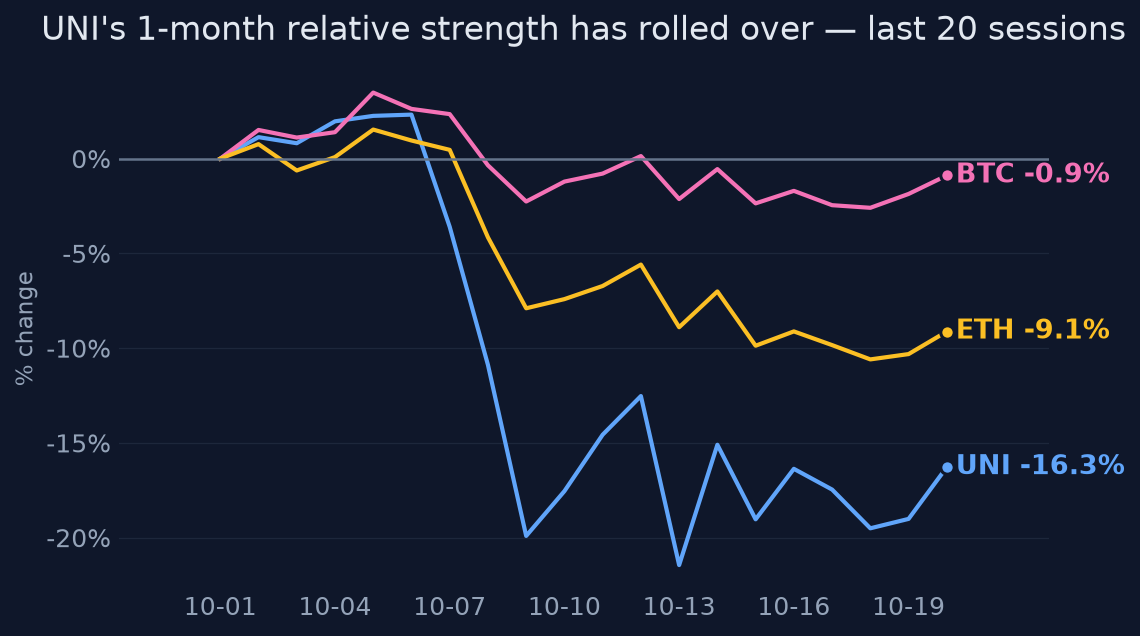
At 62x FDV/revenue with a burn yield of only 1-2.5% of market cap, UNI needs fee growth to justify the multiple — and fees are falling 45-49% month-over-month while DEX market share erodes structurally (PancakeSwap, Aerodrome, chain-specific venues). The burn is procyclical, so weakness compounds: lower fees → smaller burns → weaker tokenomics support → lower price. Momentum has already rolled over (below 20d/50d, RS negative 1m), sentiment is at a contrarian-extreme 100% bullish, and a -74.6% max drawdown within the past year shows how violently this asset reprices when the narrative breaks.
What would change our mind
- DefiLlama 30d fees/revenue return to flat or positive growth vs prior 30d within 1-2 months — would negate the deteriorating-fundamentals leg of the bearish lean
- Dune burn tracker shows recurring burns materially above the ~$49.6M/yr estimate (e.g., trending toward $100M+/yr) — would mean accrual is at the high end and valuation is defensible
- Price reclaims the 50d SMA with relative strength vs BTC turning positive — would signal the 1m pullback was consolidation, not reversal
- Conversely, a second consecutive month of >40% fee decline or verified further share loss to PancakeSwap/Aerodrome would confirm the bearish read and justify moving beyond a lean
Since publication vs BTC · closed horizons are frozen
No price data after the entry date yet.
The full research everything the view rests on
Direct answer to the question asked
Where the edge would come from
What the price assumes
At $7.43 (62x FDV/revenue, 1.12x mcap/TVL, +130% over 6m), the price appears to assume the UNIfication burn narrative continues to compound: sustained or recovering DEX volumes, expanding fee-switch coverage across chains (v4 Part 1 done July 2026, Arc added Oct 5, 2026), and growing institutional access via CME futures. It does not appear to price the current -45 to -49% monthly fee/revenue decline persisting.
Why the market may be wrong
Consensus treats the burn as a one-way ratchet, but it is mechanically fee-linked: burns shrink exactly when activity shrinks. The unresolved contradiction in the data — TVL +9.5%/30d while fees fall -49% — suggests mix shift toward lower-fee pools/v4 or volume migrating to competitors (Uniswap share est. ~29% Aug 2026 vs 45% Jan 2024). If the fee decline is structural share loss rather than seasonal, the burn-yield thesis is worth roughly half what holders assume, and the 100% bullish CoinGecko sentiment plus stale scan momentum is a crowded, lagging positioning signal.
The one thing to watch
The variable to watch is not the burn total — it's the fee trajectory, because the fee switch converted UNI from a pure governance token into a procyclical claim on DEX volume: the buyback-and-burn amplifies both directions, so UNI now behaves like a leveraged bet on Uniswap fee revenue with a ~62x multiple attached. A -49% monthly fee print is therefore not noise around the thesis; it IS the thesis moving against holders.
Key evidence (10)
- Fee switch live since Dec 2025: protocol fees route to TokenJar collectors and fund UNI buyback-and-burn; ~100M UNI one-time treasury burn (late Dec 2025) plus ~6.2M UNI recurring burns (GitHub on-chain analysis [T1], Token Terminal [T3])
- Fees -48.8% and revenue -44.4% (30d vs prior 30d) while TVL +9.5%/30d and +30%/90d (DefiLlama [T3], 2026-10-20)
- 3m return +105% vs BTC +27% / ETH +28%; 60d beta ~1.5 but idiosyncratic share ~70% — move is mostly alpha, not beta (quant analysis, 2026-10-20)
- Relative strength flipped: +61% vs BTC over 3m but -16% over 1m; price -6% below 20d SMA, RSI 46, 1m z-score -0.62 (2026-10-20)
- CME standard + Micro UNI futures live for Oct 19, 2026 trade date (CME announcement Sept 22 [T1]; CoinDesk [T2], 2026-10-19) — argues against thin-liquidity squeeze hypothesis
- Liquidity healthy: $280M 24h volume = 6.0% of $4.63B mcap; rank #25 (CoinGecko, 2026-10-20)
- No unlock overhang: vesting ended 2024, fully unlocked, 2%/yr mint authority never exercised (tokenomics search, [T3]/[T4])
- Governance momentum: v4 protocol fees Part 1 executed July 27, 2026; fee expansion to Arc executed Oct 5, 2026, 46.26M for / 0 against (gov.uniswap.org [T1])
- Burn magnitude uncertain: ~$49.6M/yr annualized per on-chain analysis vs ~$28M to holders in Q3 alone per Token Terminal [T3] — >2x discrepancy, true yield ~1-2.5% of mcap
- Uniswap still #1 DEX (~$87.5-91B 30d volume, ~3x PancakeSwap) but long-term share erosion ~45% (Jan 2024) → ~29% (Aug 2026) (estimates, mostly [T4] — treat as approximate)
Catalysts and risks
Catalysts
- Unichain OP Enterprise mainnet migration — planned late October 2026 (testnet began Oct 13)
- CME UNI futures open interest/volume data in coming weeks — first read on institutional adoption
- Dune burn tracker (marco_v/uniswap-fee-and-uni-burn-tracker) updates — recurring burn totals vs the $49.6M/yr estimate
- Monthly DefiLlama fee prints — whether the -49% 30d decline reverses or confirms a trend
- Further governance votes expanding protocol fees to additional chains (Arc executed Oct 5; more chains likely)
- SMBC Nikko/Nethermind Japan v4 institutional venue milestones (target 2027)
Risks
- Fee decline is structural share loss, not seasonal — directly cuts the burn that underpins valuation
- Burn-yield estimates conflict by >2x across sources; the true accrual may be at the low end (~1%/yr)
- Procyclicality: the fee switch makes UNI a levered claim on DEX volumes into a potential activity downturn
- 93% annualized realized vol and -74.6% 1y max drawdown — position sizing errors are costly
- Sector/share data is mostly [T4]; the competitive-erosion claim is directionally supported but not precisely measured
- Governance could exercise the 2%/yr mint authority, diluting the burn (currently unexercised)
- Beta ~1.5 to BTC means a broad crypto drawdown hits UNI harder regardless of fundamentals
What to watch
- DefiLlama Uniswap fees/revenue 30d-vs-prior-30d change — the single most thesis-relevant series
- Recurring UNI burn totals on the Dune marco_v tracker (token-denominated, network-by-network)
- CME UNI futures open interest and volume post-launch
- Unichain OP Enterprise mainnet migration completion and any fee/sequencer-revenue impact
- Uniswap's share of total DEX spot volume (DefiLlama DEX aggregator) vs PancakeSwap/Aerodrome
- UNI/BTC and UNI/ETH ratios — whether the 1-month relative-strength flip extends
- Uniswap governance forum for v4 fee expansion Part 2 and any use of the 2% mint authority
Market snapshot when the call was made 2026-10-20
Price
| Return 1w | +6.6% |
| Return 1m | -14.2% |
| Return 3m | +104.8% |
| Return 6m | +129.9% |
| Return 1y | +18.7% |
| From 52-week high | -27.3% |
| Realized vol, 20d | 93.3% |
| BTC 3m / 1y | +27.1% / -23.8% |
| ETH 3m / 1y | +28.3% / -38.7% |
| QQQ 3m / 1y | +1.3% / +19.7% |
Technicals
Sources (24 · T1 = primary filings)
- T4https://developers.uniswap.org/docs/ecosystem/governance/faqs
- T4https://startupfortune.com/uniswap-torched-596-million-in-uni-the-same-week-its-fee-switch-passed/
- T4http://www.odaily.news/en/post/5212965
- T3https://tokenterminal.com/resources/newsletter/uniswap-after-unification
- T3https://dune.com/marco_v/uniswap-fee-and-uni-burn-tracker
- T4https://cryptonews.com/news/uniswap-uni-crypto-buybacks-burns-protocol-fees/
- T4https://developers.uniswap.org/docs/ecosystem/governance/uni.md
- T1https://github.com/jaimeberdejo/uniswap-tokenomics-value-capture
- T4https://eco.com/support/en/articles/11827084-best-dexs-in-2026-fees-volume-ranked
- T4https://blockonomi.com/dex-statistics-2026-volume-market-share-and-perp-data/
- T1https://www.dwellir.com/blog/state-of-defi-q3-2026
- T4https://www.onedayadvisor.com/2026/09/best-decentralized-exchanges-dexs.html
- T4https://ground.news/article/uniswap-processes-over-70b-in-monthly-volume-surpassing-next-three-dexs-combined
- T1https://github.com/Ricosworks1/blockchain-payment-flow-analysis/releases/tag/comparative-analysis-dex-market-s…
- T4https://nownodes.io/blog/best-decentralized-exchanges-dexs-in-2026/
- T4https://coinlaw.io/decentralized-exchanges-dex-statistics/
- T4https://www.cmegroup.com/media-room/press-releases/2026/9/22/cme_group_to_expandcryptoderivativessuitewithbitc…
- T4https://blog.uniswap.org/
- T2https://www.coindesk.com/markets/2026/10/19/cme-s-bitcoin-cash-uniswap-futures-global-pmis-crypto-week-ahead
- T4https://blog.uniswap.org/unichain-is-upgrading-to-op-enterprise
- T3https://coinmarketcap.com/cmc-ai/uniswap/latest-updates/
- T4https://crypto-economy.com/uni-futures-go-live-on-cme-group-marking-a-major-milestone-for-defi/
- T4https://cmegroupinc.gcs-web.com/press-releases2
- T4https://crypto.news/uni-futures-have-reached-cme-will-the-new-market-matter-to-uniswap/
Want a fresh look at UNI, or another name?
Queue a new deep-research run. Published to the feed when done.
Automated research opinion, published as-is on Oct 20, 2026. Not personalised advice. Figures use end-of-day closes.