Mostly right direction, wrong magnitude.
Thesis
Bull case
The drop is FX translation and risk-premium noise on a company growing revenue 50% with stable credit metrics. If BRL stabilizes after a credible finance-minister appointment, the 3-4% mechanical revenue hit is small against the ~$7-8B cap loss, and the Nov 4 report (revenue consensus already revised up) re-anchors the market on fundamentals. Consensus targets imply very large upside (~40% on the [T4]-sourced ~$2,250 average), though those targets predate or may not fully reflect the new Brazil risk regime; the stock also trades below its own historical multiple (per [T4] data).
Bear case
Lula's term means structurally higher Brazilian rates and a weaker consumer, which hits MELI through the channel that actually matters: its $16.4B, +75%-growth credit book. Funding costs rise, future vintages sour, and provisions climb — with operating margin already down 550bps on Brazil investment, FY26 EPS estimates (already cut 14%) have further to fall, and 43x forward is no cushion if the E is wrong. BRL at -12% may be the beginning, not the end, of the repricing.
What would change our mind
- Nov 4 report shows Brazil NPLs or charge-offs rising materially by vintage, or provision expense accelerating
- Management tightens credit origination or signals a Brazil demand slowdown on the call
- BRL continues sliding (e.g., another 5-10%) after the finance-minister appointment, implying the market rejects the fiscal plan
- FY27 EPS consensus (~$55.70) is cut more than ~10% post-earnings — confirming the de-rating is fundamental, not multiple noise
Since publication vs SPY · closed horizons are frozen
The full research everything the view rests on
Direct answer to the question asked
Where the edge would come from
What the price assumes
The market is pricing Lula's term as a sustained increase in Brazil's cost of capital: weaker BRL (~11-12% intraday), higher local rates, fiscal slippage, and downstream pressure on Brazilian consumer spending and credit quality. At ~43x forward earnings — reportedly below its historical average (~47.6x four-year average per [T4] sourcing, treat as approximate) — after FY26 EPS estimates were already cut ~14% over three months, the stock now assumes further estimate deterioration rather than stabilization.
Why the market may be wrong
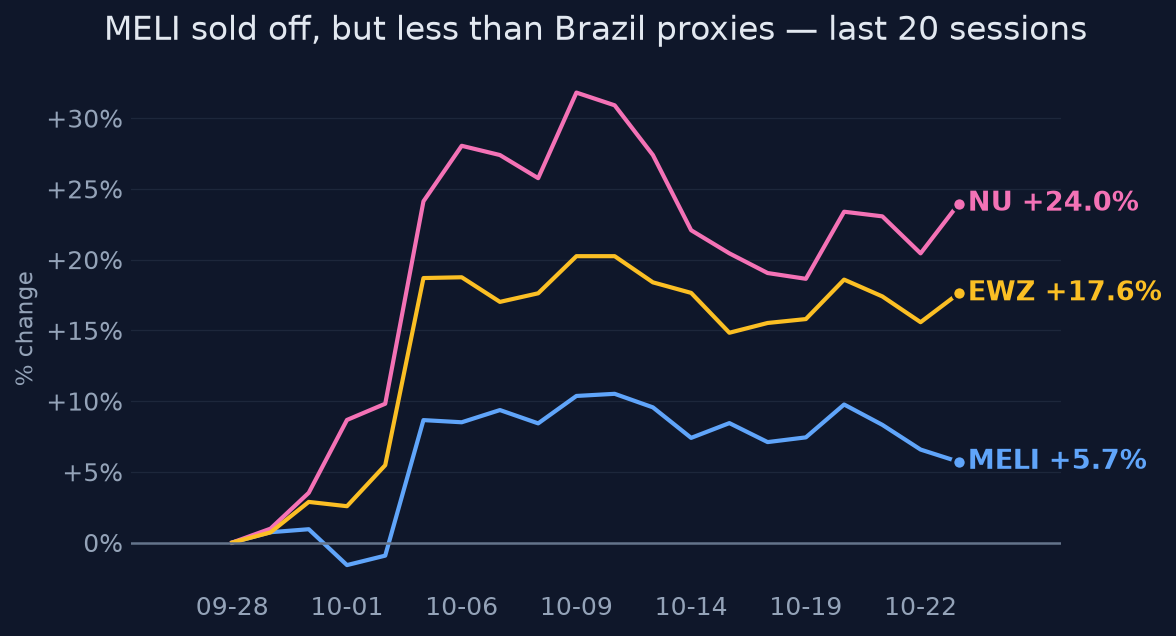
The knee-jerk treats MELI as a levered BRL proxy, but its actual economic sensitivity per 10% BRL move is only ~3-4% of revenue; today's ~$7-8B cap loss (~$12B at the low) still implies something several times worse than the disclosed mechanical impact. MELI also fell less than pure-Brazil peers (NU -25%, Petrobras -21%), reflecting Argentina/Mexico diversification. The bear case requires future credit deterioration that Q2 data explicitly does not show — management reported stable Brazilian NPLs and no slowdown in bookings.
The one thing to watch
Stop watching MELI's stock price as the signal — watch USD/BRL, because today MELI is trading as a levered BRL proxy while its disclosed sensitivity to a 10% real move is only ~3-4% of revenue; the variable that actually converts this macro scare into a thesis break is Brazil NPLs/provisions by vintage on the November 4 report, not the election itself.
Key evidence (8)
- Lula reelected over Flávio Bolsonaro; BRL -11-12% intraday, Ibovespa circuit breaker at -10%, Petrobras -21%, NU -25% (Reuters/Bloomberg [T2], 2026-10-26)
- MELI fell ~15% intraday to ~$1,545, recovered to close -8.8% at ~$1,644.55 — milder than broad Brazil assets; on an ~$83.3B market cap that is roughly $7-8B erased at the close, ~$12B at the intraday low; no company filing or announcement coincided
- MELI 10-Q sensitivity: 10% BRL depreciation ≈ $444M reduction in dollar value of Brazilian net assets (mostly OCI) plus ~$9M FX gain; implies ~3-4% consolidated revenue impact [T1] — small relative to the cap loss, though by a factor of roughly 5-17x, not an order of magnitude
- Q2-26 (reported Aug 5, 2026): revenue $10.17B +50% (+43% FX-neutral), GMV +44%, TPV +56%; operating margin 6.7%, -550bps YoY on deliberate Brazil investment [T1]
- Credit book $16.4B +75% YoY; 15-90d NPLs 7.0% total / 4.6% cards, described by management as near historical lows with stable Brazil trends [T1]
- Consensus: FY26 revenue $41.87B / EPS ~$38.35 (cut ~14% over 3 months); FY27 EPS ~$55.70; ratings ~16 Buy/4 Outperform/6 Hold, avg target ~$2,250-2,290; trims from Citi (~$2,100) and Cantor (~$2,200) [T4, weaker sourcing — targets may lag a genuine change in Brazil's cost of capital]
- Q3-26 earnings provisionally scheduled November 4, 2026 AMC per MELI IR calendar [T1] — this selloff is a pre-earnings event
- Lula's team has floated a 1.3%-of-GDP primary surplus target by 2030; markets focused on finance-minister appointment [T2]
Catalysts and risks
Catalysts
- Q3-26 earnings November 4, 2026 AMC — Brazil NPLs/provisions by vintage, FX-neutral growth, funding costs
- Lula's finance-minister appointment and fiscal-framework details (1.3% primary surplus target by 2030)
- USD/BRL trajectory and Brazilian rate-futures pricing over coming weeks
- Post-earnings analyst estimate revisions for FY26/FY27
- Central Bank of Brazil policy response to FX-driven inflation
Risks
- Sustained BRL depreciation converts translation noise into real estimate cuts
- Higher-for-longer Brazilian rates raise Mercado Pago funding costs and future delinquencies with a 2-4 quarter lag
- Pre-earnings binary event on Nov 4 against already-falling EPS estimates
- Fiscal slippage keeps Brazil risk premium elevated, compressing the multiple regardless of operations
- Argentina/Mexico diversification may not offset if Brazil weakness spills regionally
What to watch
- USD/BRL daily — the single number; stabilization vs. continued slide
- Finance-minister appointment and credibility of the fiscal plan
- Nov 4: Brazil NPLs by vintage, provision coverage, Mercado Pago funding costs/NIM, FX-neutral Brazil growth
- FY26/FY27 EPS revision direction in the two weeks after earnings
- EWZ and NU as Brazil risk-premium gauges — MELI should outperform them if its diversification thesis holds
Market snapshot when the call was made 2026-10-23
Price
| Return 1w | -1.3% |
| Return 1m | +3.2% |
| Return 3m | -0.5% |
| Return 6m | -1.4% |
| Return 1y | -13.6% |
| From 52-week high | -23.3% |
| Realized vol, 20d | 39.7% |
| SPY 3m / 1y | +2.8% / +13.8% |
| QQQ 3m / 1y | +3.3% / +16.3% |
Technicals
MELI technicals as of 2026-10-23: last close $1,810.15; 20d SMA 1,819.66 (bearish); 50d SMA 1,859.33; 12d EMA 1,838.87; 26d EMA 1,837.78; RSI 14 40.9 (balanced); 20d vol 39.9%; volume x0.8 vs 20d avg
Next earnings: 2027-02-22 AMC
Verifier notes REVISE · opinion revised once
Unsupported claims
- 'roughly $15B of market cap erased today' (stated three times: answer, why_market_may_be_wrong, bull_case): the evidence gives a market cap of ~$83.3B at ~$1,643/share. An 8.8% decline erases ~$7.3B; even the ~15% intraday low implies ~$12.5B. $15B appears nowhere in the evidence and follows from no stated arithmetic. This materially weakens the repeated 'order of magnitude smaller' comparison between the FX sensitivity (~$444M OCI / ~3-4% of revenue) and the cap loss — the ratio is ~2x overstated.
- 'At ~43x forward earnings (below its ~47.6x four-year average)': the 47.6x four-year average multiple does not appear in any tool result; it is only in the planner digest, which itself flags it as weakly sourced [T4]. The opinion states it as fact in market_expectation without any sourcing caveat.
Weakly sourced
- Consensus targets ~$2,250-2,290, Citi ~$2,100, Cantor ~$2,200 trims, and the ~47.6x 4-yr average multiple rest on [T4] aggregator sourcing; the opinion does tag them in key_evidence but then uses '~40%+ upside' in the bull_case as if firm.
Corrections applied
- Replace '~$15B of market cap erased' with the correct figure: ~$7-8B at the -8.8% close (≈8.8% × $83.3B market cap), or ~$12B at the intraday low. Adjust the 'order of magnitude smaller' rhetoric accordingly — the disclosed FX sensitivity is still small relative to the cap loss, but the gap is roughly 5-17x, not an order of magnitude against $15B.
- Qualify or drop the '~47.6x four-year average' multiple, or explicitly mark it as weakly sourced (T4) wherever it is used (market_expectation, bull_case).
- In bull_case, soften 'consensus targets imply ~40%+ upside' to acknowledge the target data is T4-sourced and may lag the regime change (the evidence itself warns 'analyst targets may lag a genuine change in Brazil's cost of capital').
Sources (36 · T1 = primary filings)
- T2https://www.bloomberg.com/news/articles/2026-10-26/brazil-markets-brace-for-rout-on-lula-s-improbable-election…
- T4https://finance.yahoo.com/markets/stocks/articles/brazilian-stocks-tumble-lula-wins-132206701.html
- T4https://valorinternational.globo.com/markets/news/2026/10/26/markets-brace-for-turmoil-after-lulas-surprise-re…
- T2https://www.reuters.com/business/analysts-forecast-brazil-market-falls-after-lula-turnaround-win-2026-10-26/
- T4https://www.nytimes.com/2026/10/26/business/brazil-markets-election-lula.html
- T4https://www.kansascity.com/news/nation-world/national/article317777504.html
- T3https://www.cnbc.com/2026/10/26/brazil-lula-win-presidential-election-runoff-vote.html?ref=alphabriefing.com
- T4https://valorinternational.globo.com/google/amp/markets/news/2026/10/26/markets-brace-for-turmoil-after-lulas-…
- T2https://www.reuters.com/business/finance/investors-expect-markets-unwind-brazils-lula-reelected-2026-10-26/
- T4https://www.bradenton.com/news/nation-world/national/article317777504.html
- T4https://tradingeconomics.com/brazil/stock-market/news/594792
- T2http://rmb.reuters.com/rmd/rss/item/tag:reuters.com,2026:newsml_KCN3W60DK?channel=frL012
- T4https://www.france24.com/es/am%C3%A9rica-latina/20261026-el-real-brasile%C3%B1o-se-desploma-y-la-bolsa-cae-tra…
- T4https://www.kentucky.com/news/nation-world/world/article317781742.html
- T2http://rmb.reuters.com/rmd/rss/item/tag:reuters.com,2026:newsml_KCN3W611Q?channel=FBi345
- T4https://companiesmarketcap.com/mercadolibre/sec-reports-10q/0001099590-26-000023/
- T1https://investor.mercadolibre.com/open-file?file=aHR0cHM6Ly9odHRwMi5tbHN0YXRpYy5jb20vc3RvcmFnZS9tbC1jbXMtYmFja…
- T4https://finance.yahoo.com/quote/MELI.VI/earnings/MELI.VI-Q1-2026-earnings_call-566793.html
- T4https://finance.yahoo.com/quote/MELI.BA/earnings/MELI.BA-Q1-2026-earnings_call-566793.html
- T4https://coincentral.com/nu-holdings-and-mercadolibre-stocks-sink-as-lula-wins-what-analysts-say-now/
- T4https://finance.yahoo.com/quote/MELIB.BA/earnings/MELIB.BA-Q2-2026-earnings_call-662711.html
- T4https://www.lanacion.com.ar/economia/la-reaccion-de-las-acciones-de-mercado-libre-tras-la-victoria-de-lula-da-…
- T4https://finance.yahoo.com/quote/1MELI.MI/earnings/1MELI.MI-Q2-2026-earnings_call-662711.html/
- T4https://www.marketbeat.com/stocks/NASDAQ/MELI/earnings/
- T1https://investor.mercadolibre.com/news-and-events
- T4https://public.com/stocks/meli/earnings
- T1https://investor.mercadolibre.com/sec-filings
- T4https://www.marketbeat.com/earnings/reports/2026-11-4-mercadolibre-inc-stock/
- T4https://www.fxempire.com/stocks/meli/earnings
- T1https://investor.mercadolibre.com/news-and-events?page=4
- T4https://www.zacks.com/stock/research/MELI/earnings-calendar
- T4https://www.thestreet.com/investing/stocks/warren-buffetts-former-fintech-investment-plunges-20-nubank-nu
- T4https://finance.yahoo.com/quote/0K0E.L/earnings/0K0E.L-Q2-2026-earnings_call-662711.html
- T4https://www.perplexity.ai/finance/MELI?comparing=MELI,BABA,ABNB,CHWY,PINS,PYPL
- T4https://www.perplexity.ai/finance/MELI?comparing=MELI,WMT,SE,JD,TGT,COST
- T4https://finance.yahoo.com/quote/MELI/
Want a fresh look at MELI, or another name?
Queue a new deep-research run. Published to the feed when done.
Automated research opinion, published as-is on Oct 26, 2026. Not personalised advice. Figures use end-of-day closes.