Good business; murky 3-6 month entry.
Thesis
Bull case
Organic ~23-24% GOV growth with a ~60% US meal-delivery share, a completed GAAP-profitability inflection, $2.1B TTM FCF, upward EPS revisions, and Q3 guidance above consensus — all while the stock trades 37% below its high and ~27% below consensus target. Grocery/retail/international expansion, advertising monetization, and Deliveroo synergies beyond the guided $200M provide upside optionality the current price doesn't pay for. If organic growth holds above 20% through the Deliveroo lap, the multiple re-rates and the stock has 30-50% upside to consensus-type levels.
Bear case
Headline growth is acquisition-flattered; the underlying business is a mid-20s-to-decaying grower whose GAAP earnings are halved in quality terms by $1.3-1.4B of SBC and ongoing dilution. Regulatory costs are structural, not episodic — the NYC settlement is at least the third major labor-cost event, with fee caps and CA/NY/EU classification risk ahead. Serial M&A (Deliveroo £2.9B, SevenRooms ~$1.2B, Symbiosys) consumes cash and management attention with thin demonstrated returns (Deliveroo: ~$200M EBITDA vs. the price paid). Uber, Amazon, and autonomy cap take-rate expansion (aggregator fees already 15-30% of order). At ~42x FY27 GAAP consensus EPS, 'cheap' only exists on adjusted numbers. The low analyst target ($172) is already below the price — the de-rating may have further to run.
What would change our mind
- Ex-Deliveroo organic GOV growth falls below ~18-20% in Q3 or Q4 2026 prints — confirms the de-rating is fundamental, not sentiment
- FY27 EPS consensus stops drifting up and begins meaningful downward revisions while the stock is already de-rated — signals estimate risk, not just multiple risk
- Adjusted EBITDA guidance for Q4 2026 / FY2027 comes in below the implied ~$4B annualized run-rate
- A second major labor settlement or an adverse gig-classification ruling in CA or the EU materially above the NYC precedent in cost terms
- Insider selling accelerates into weakness rather than stabilizing
Since publication vs SPY · closed horizons are frozen
The full research everything the view rests on
Direct answer to the question asked
Where the edge would come from
What the price assumes
At $187 and ~$81.5B market cap, the price appears to assume the organic growth rate decays meaningfully below the current ~23% and that regulatory/labor costs keep rising — i.e., it discounts the adjusted-EBITDA story (~20x EV/EBITDA on the implied ~$4B run-rate) rather than rewarding it. It does not appear to assume Deliveroo synergies beyond the stated ~$200M 2026 contribution, nor any success from grocery/retail/ads expansion. The large gap to the $256 consensus target (low target $172, below the price) signals the market doubts the sell-side's numbers rather than shares them.
Why the market may be wrong
The market is treating reported 36-37% growth as suspect because it's Deliveroo-inflated — but the ex-Deliveroo organic rate of ~23-24% GOV / 21-24% revenue is still elite for an $81B company, and estimates are being revised UP while the stock falls. That combination (rising estimates + falling price) historically resolves in favor of fundamentals unless a thesis-breaking event occurs. Conversely, the sell-side may be wrong in the other direction: $1.3-1.4B of SBC means the 'adjusted' earnings underpinning targets overstate owner earnings, and the market's GAAP-multiple skepticism (~42x FY27 GAAP EPS) is more rational than the targets suggest.
The one thing to watch
The variable that matters is not reported growth but the ex-Deliveroo organic GOV growth rate: headline 'beats' of 36-37% are ~13 points acquisition, so the entire debate reduces to whether organic ~23-24% holds as Deliveroo laps in late 2026. Watch that ex-Deliveroo line in the Q3 print (early November) — if it holds above ~20% while the stock stays ~35% below its high, the selloff is pure multiple compression and the entry is attractive; if organic slips toward the mid-teens, the de-rating is justified and the $172 low target is live.
Key evidence (10)
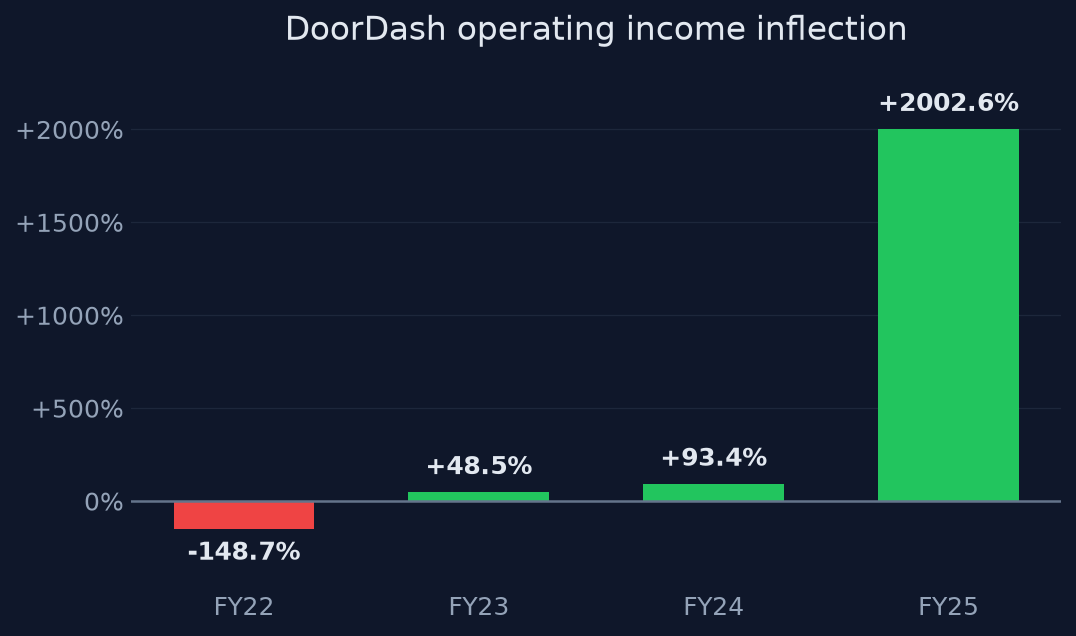
- Revenue $4.9B (2021) -> $13.7B (2025); GAAP net income positive since 2024, $935M in 2025; operating margin -17.1% (2022) -> +5.3% (2025) [T1 SEC XBRL]
- Q2 2026 (reported Aug 5, 2026): revenue $4.45B beat $4.34B est.; GOV $33.1B beat; adj. EBITDA $914M above guide; Q3 guidance (GOV $33-34B, EBITDA $950M-1.1B) above consensus per Reuters [T1/T2]
- Ex-Deliveroo organic growth: Q1 2026 GOV +24% and revenue +21% (vs +37%/+33% reported); Q2 2026 GOV +23% and revenue +24% (vs +36%/+36% reported) — ~13pts of headline growth is inorganic [T1 Q1/Q2 2026 releases]
- TTM free cash flow reached $2.1B by Q2 2026; FY2025 FCF $1.8B flat y/y [T1]
- 2026 SBC guided at $1.3-1.4B (≈ GAAP net income); $1.6B unrecognized RSU expense as of Mar 31, 2026 [T1]
- $131.5M NYC delivery-worker pay settlement, Sept 2026 (~$115M worker relief + $16.7M fine); Reuters noted shares rose slightly on the day — cumulative-cost signal, not a single trigger [T2]
- Stock: -31.9% 1y, -23.1% 1m, -36.7% below 52w high, max drawdown -48%, realized vol ~49%, beta 1.79 — vs SPY +16% and QQQ +24% over 1y [market data]
- FY26 consensus ~$17.8B rev / $2.59-2.62 EPS; FY27 ~$21.5B / $4.48-4.70, revisions drifting upward through Sept 2026 [T4 Yahoo/WSJ — single-source-tier, treat as directional]
- Quoted ~27.8x forward P/E does not reconcile with GAAP consensus ($187/$2.59 ≈ 72x FY26; $187/$4.48 ≈ 42x FY27) — the 27.8x figure likely uses non-GAAP earnings; unresolved in evidence [T4, flagged]
- Consensus target ~$256 (range $172 low to $350 high); Needham $265, Bernstein/Rosenblatt $270, UBS ~$290 [T4 — no T1/T2 corroboration of the full target set]
Catalysts and risks
Catalysts
- Q3 2026 earnings, early November 2026 — ex-Deliveroo organic GOV growth vs. the guided $33-34B GOV / $950M-1.1B EBITDA
- Deliveroo anniversary in Q4 2026 — organic growth becomes the reported number; first clean read on underlying momentum
- Any disclosure of Deliveroo synergy run-rate beyond the ~$200M 2026 EBITDA contribution
- Further regulatory/labor developments: NYC fee-cap litigation, California/EU gig-classification rulings
- Autonomous delivery progress or setbacks (DoorDash Air drone program post-FAA certification; Serve/Coco/Waymo headlines)
- Insider transaction pattern — continued selling vs. cessation would be a sentiment tell
Risks
- Structural labor/regulatory cost escalation (worker pay settlements, fee caps, reclassification) compressing margins faster than operating leverage builds
- Growth-quality disappointment: ex-Deliveroo organic growth decays toward mid-teens as the acquisition laps, validating the de-rating
- SBC/dilution: $1.3-1.4B annual SBC plus Deliveroo RSU replacement ($80M replacement awards) means GAAP and owner earnings lag adjusted figures for years
- M&A execution risk across Deliveroo, SevenRooms, and Symbiosys; FCF already dented by deal costs (Q4 2025 FCF just $254M)
- Competition from Uber Eats, Amazon restaurant delivery, and Instacart capping take rates and grocery/retail ambitions
- Extreme volatility (beta 1.79, ~49% realized vol, -48% max drawdown within a year) — sizing and entry timing dominate returns on a 3-6 month horizon
- Consumer discretionary softness hitting order frequency and average order values
What to watch
- The ex-Deliveroo organic growth lines in every quarterly release — the single most decision-relevant disclosure
- Q3 2026 results vs. the $33-34B GOV / $950M-1.1B EBITDA guide (early November 2026)
- GAAP net income vs. adjusted EBITDA gap trajectory — is the SBC drag shrinking as a % of profit?
- Free cash flow ex-deal-costs normalization after Deliveroo integration spend rolls off
- Consensus FY27 EPS revision direction through Q4 2026
- Analyst target dispersion — does the $172 low target get raised (capitulation of bears) or do high targets get cut (sell-side catching down to the market)?
- Post-Deliveroo balance sheet detail and any buyback authorization — currently unknown from surfaced filings
Market snapshot when the call was made 2026-09-29
Price
| Return 1w | -8.0% |
| Return 1m | -23.1% |
| Return 3m | -3.5% |
| Return 6m | +21.7% |
| Return 1y | -31.9% |
| From 52-week high | -36.7% |
| Realized vol, 20d | 40.3% |
| SPY 3m / 1y | +3.3% / +16.4% |
| QQQ 3m / 1y | +0.2% / +23.8% |
Technicals
DASH technicals as of 2026-09-29: last close $187.10; 20d SMA 199.70 (bearish); 50d SMA 205.44; 12d EMA 192.62; 26d EMA 199.56; RSI 14 40.5 (balanced); 20d vol 44.7%; volume x1.3 vs 20d avg
Verifier notes PASS
Unsupported claims
- Bear case states the NYC settlement 'is at least the third major labor-cost event' — the specific count of three prior major events appears only in the planner digest's own characterization and is not documented anywhere in the tool evidence (which surfaces the NYC settlement, NYC fee caps, and CA/NY/EU classification risk, but no enumerated prior settlement events). The broader claim that regulatory costs are recurring/structural is well supported; the 'third major event' precision is not.
- SBC of $1.3-1.4B 'roughly equals GAAP net income' — 2025 GAAP net income was $935M, so SBC guidance is ~40% above the most recent full-year GAAP net income, not roughly equal (the digest's softer 'comparable in size' is more accurate). The qualitative point stands and 2026 GAAP NI may be higher, but the equality framing slightly overstates.
Weakly sourced
- The ~60% US meal-delivery market share figure rests solely on a Fortune profile tagged [T4] in the industry research call; it is stated as fact in the direct answer and anchors the bull case, unlike other T4-derived figures (consensus estimates, price targets, 27.8x forward P/E) which the opinion explicitly flags as directional/unresolved.
- The ~$256 consensus target, $172 low / $350 high range, and individual bank targets (Needham $265, Bernstein/Rosenblatt $270, UBS $290) are all [T4]-only with no T1/T2 corroboration — the opinion does flag this in key_evidence, so this is noted for completeness rather than as a deficiency.
Corrections applied
- In bear_case, replace 'the NYC settlement is at least the third major labor-cost event' with 'the NYC settlement is the latest in a series of labor-cost pressures (fee caps, classification fights) that recur rather than resolve'.
- Soften 'SBC roughly equals GAAP net income' to 'SBC guidance of $1.3-1.4B exceeds 2025 GAAP net income of $935M' (or 'is comparable to current GAAP earnings power').
- Attribute the ~60% US meal-delivery share as press-reported (single [T4] profile) rather than stated fact, consistent with how the opinion handles other T4 figures.
- Note (optional, minor): the '~20x EV/EBITDA' figure is computed on market cap since post-Deliveroo net cash/debt is unknown from surfaced filings — the opinion already acknowledges this gap in what_to_watch, so labeling it market-cap/EBITDA would be cleaner but is not decision-changing.
Sources (32 · T1 = primary filings)
- T4https://fortune.com/article/doordash-delivery-wars-ceo-tony-xu-fortune-500-grubhub-uber-eats-suburbs-mark-zuck…
- T4https://www.makemyreceipt.com/reports/food-delivery-statistics
- T4https://www.kenresearch.com/industry-reports/usa-online-food-delivery-market
- T4https://dataintelo.com/report/crowdsourced-delivery-platforms-market
- T4https://dataintelo.com/report/on-demand-delivery-market
- T4https://www.imarcgroup.com/united-states-online-food-delivery-market
- T4https://www.investors.com/news/technology/amazon-stock-groceries-walmart-instacart/
- T4https://dataintelo.com/report/hyperlocal-delivery-model-market
- T4https://www.marketbeat.com/instant-alerts/price-doordash-nasdaq-dash-stock-falls-61-heres-why-2026-09-28/
- T4https://www.tikr.com/blog/doordash-stock-is-sliding-so-why-did-the-streets-target-go-up
- T4https://finance.yahoo.com/quote/DASH/
- T4https://www.marketscreener.com/quote/stock/DOORDASH-INC-116169045/consensus/
- T4https://www.marketbeat.com/stocks/NASDAQ/DASH/
- T4https://tickeron.com/blogs/doordash-dash-retreats-18-3-over-30-days-factors-behind-the-pullback-17227/
- T4https://www.marketbeat.com/instant-alerts/filing-24356-doordash-inc-dash-shares-bought-by-envestnet-portfolio-…
- T4https://www.investing.com/news/analyst-ratings/bernstein-reiterates-doordash-stock-rating-on-longterm-growth-o…
- T1https://ir.doordash.com/financials/sec-filings/default.aspx
- T4https://www.stocktitan.net/sec-filings/DASH/
- T2https://www.reuters.com/markets/companies/DASH.O/
- T1https://www.sec.gov/Archives/edgar/data/1792789/000114036126037109/0001140361-26-037109.txt
- T3https://www.nasdaq.com/market-activity/stocks/dash/sec-filings
- T4https://www.stocktitan.net/sec-filings/DASH/144-door-dash-inc-sec-filing-19c02adb87ba.html
- T2https://www.reuters.com/company/doordash-inc/
- T4https://in.marketscreener.com/news/doordash-reaches-131-5-million-settlement-with-nyc-over-delivery-workers-pa…
- T1https://ir.doordash.com/news/news-details/2026/DoorDash-Releases-Second-Quarter-2026-Financial-Results/default…
- T1https://ir.doordash.com/news/news-details/2026/DoorDash-Releases-First-Quarter-2026-Financial-Results/default.…
- T2https://markets.ft.com/data/announce/detail?dockey=600-202602181605BIZWIRE_USPRX____20260218_BW361601-1
- T1https://www.sec.gov/Archives/edgar/data/1792789/000179278926000035/R13.htm
- T4https://www.zacks.com/stock/news/2970325/doordash-q2-earnings-miss-on-higher-rd-costs-revenue-beat
- T4https://www.theglobeandmail.com/investing/markets/stocks/NOW/pressreleases/3816696/doordash-dash-q2-2026-earni…
- T1https://www.sec.gov/Archives/edgar/data/1792789/000179278926000037/dash-20260331.htm
- T4https://quartr.com/events/doordash-inc-dash-q1-2026_3YmdhvWm
Want a fresh look at DASH, or another name?
Queue a new deep-research run. Published to the feed when done.
Automated research opinion, published as-is on Sep 29, 2026. Not personalised advice. Figures use end-of-day closes.