Fundamentals support it — mildly.
Thesis
Bull case
De-rated quality compounder with all three overhangs resolving: Exact dilution is a known, finite quantity that flips to accretion in 2027; CGM grew through a Class I recall, proving franchise durability; litigation caps are set. At a reported ~17.5x forward multiple with FY27 EPS of $6.07, a modest multiple normalization to 19-20x yields $115-121 — consistent with the $120 targets attributed to Barclays/JPM in press commentary (secondary sourcing) — and Abbott continues substantial capital returns ($2.1B in Q2 alone via dividends and buybacks). Positive revision momentum and clearing litigation provide tailwinds into year-end.
Bear case
Price has recovered 15% in 3 months on ~1% estimate upgrades — a valuation-repair trade now needing earnings delivery it may not get. Underlying comparable growth is only 4.8% (reported 13% is Exact consolidation optics), the company carries ~$20B more debt with higher interest expense, Libre recall litigation (deaths-linked) is a live tail risk, and medtech broadly is de-rating (BSX -54%, SYK -22% 1y). An in-line or soft Q3 on Oct 21 against elevated pre-earnings positioning could send it back toward the low $90s.
What would change our mind
- Q3 adj EPS below $1.38 (bottom of guide) or FY26 guidance cut — breaks the delivery thesis
- CGM comparable growth decelerating below ~7% or new Libre safety actions
- FY27 consensus EPS revised below ~$5.90 — signals Exact accretion path slipping
- Stock fails to hold ~$95 (post-Q2 base) after earnings — market rejecting the repair narrative
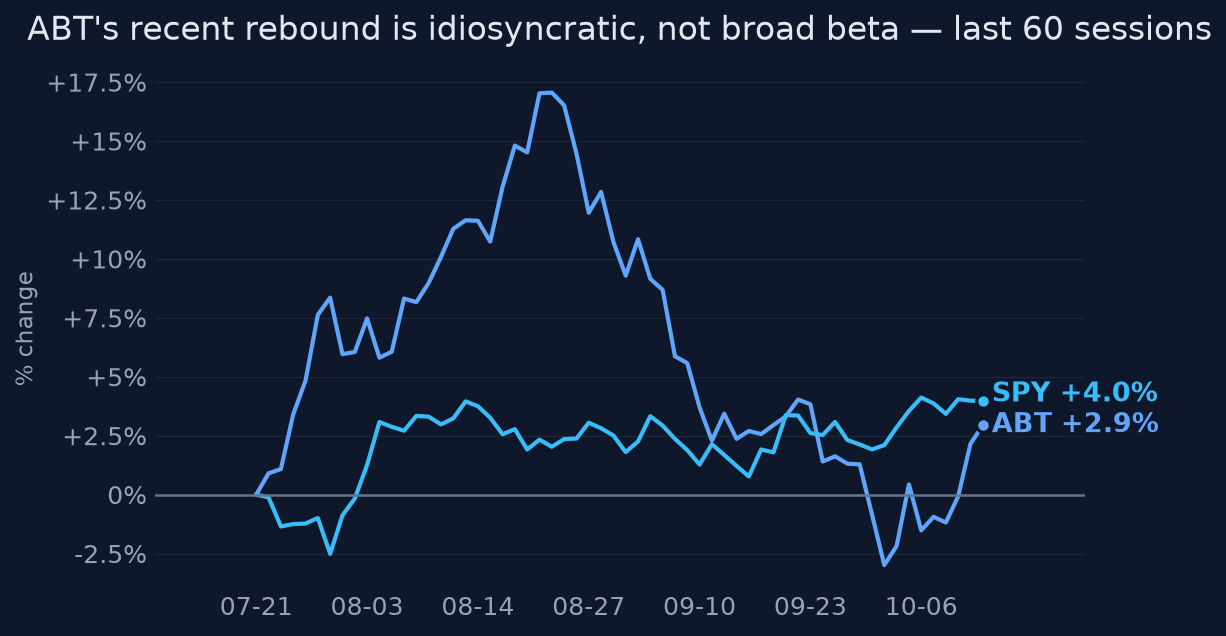
Since publication vs SPY · closed horizons are frozen
The full research everything the view rests on
Direct answer to the question asked
Where the edge would come from
What the price assumes
At ~$102.60 and ~17.5x FY26 consensus EPS of $5.52 (multiple per secondary sources), the price assumes stabilization but not full re-rating: it embeds successful Exact integration without further dilution surprises, CGM growth persisting near 9-10%, and no new Libre litigation shocks. Consensus Q3 is ~$12.9-13.0B revenue and ~$1.42 adj EPS against company guidance of $1.38-1.46 — the bar is set at the middle of the guided range, not above it.
Why the market may be wrong
Two-sided. Bearish surprise risk: the bounce (+15% in 3m) occurred with only ~1% positive EPS revisions, so price has run ahead of fundamentals and a merely in-line Q3 could disappoint pre-earnings positioning. Bullish underappreciation: if Exact's ~$3B of incremental revenue converts to faster deleveraging and 2027 accretion visibility, FY27 EPS of $6.07 at even a 19-20x multiple (still below reported 2025 levels) implies $115-121 — press commentary citing Barclays/JPM $120 targets ([T4] sourcing only) is achievable without heroic assumptions.
The one thing to watch
This is a balance-sheet story masquerading as a product story: the entire de-rating traces to Abbott choosing to pay ~$23B cash (mostly debt) for Exact Sciences, and the re-rating will track deleveraging and accretion math, not Libre headlines — the variable to watch is net debt trajectory and 2027 accretion commentary, not CGM growth which already proved resilient post-recall (7.6% → 9.5% comparable).
Key evidence (9)
- Q2 2026 (Jul 16): sales $12.59B vs $12.52B cons; adj EPS $1.31 vs $1.28; FY26 adj EPS guidance raised to $5.45-5.60, comparable sales growth 6.5-7.5% reaffirmed [T1 SEC exhibit]
- Exact Sciences: $105/share all-cash, ~$21B equity/$23B EV, ~$20B new debt issued Mar 2026, ~$0.20 FY26 EPS dilution; guidance cut $5.55-5.80 → $5.38-5.58 in Q1 [T1/T2 Reuters]
- CGM ~$2.0B+ quarterly; comparable growth 7.6% Q1 → 9.5% Q2 2026 despite Class I Libre 3/3 Plus recall (~3M sensors, 860 serious injuries/7 deaths per FDA-cited data, Reuters 2026-02-04) [T1/T2]
- Forward P/E ~17.1-17.6x vs 22.1x (Dec 2025) and 23.5x (mid-2025) — near low of recent range [T3/T4 only; not confirmed by T1/T2]
- Price: -20.8% 1y, -21% below 52w high, +14.9% 3m; 60d correlation to SPY ~-0.06 — idiosyncratic recovery [computed price data]
- FY26 EPS revisions $5.47 → $5.52 over 3 months; 5 up vs 1 down in last 30 days [T3/T4 MarketWatch]
- Abbott returned $2.1B to shareholders in Q2 2026 via dividends and share repurchases [T1] — no dividend yield figure is established in the evidence
- Sturgis infant-formula: ~$304-385M civil settlements, criminal probe closed [T4 — moderately sourced, not confirmed by T1/T2 in bundle]
- Q3 2026 earnings Oct 21, 2026 pre-market; company guided Q3 adj EPS $1.38-1.46 with ~1% FX headwind [T1 IR]
Catalysts and risks
Catalysts
- Q3 2026 earnings Oct 21, 2026 pre-market — adj EPS vs $1.38-1.46 guide, cons ~$1.42
- Exact Sciences integration and deleveraging updates; first clarity on 2027 accretion
- Any new Libre 3 recall litigation or FDA follow-up headlines
- 2027 guidance initiation (Jan 2027 earnings)
- Potential (unconfirmed) diabetes-business strategic actions — currently rumor only
Risks
- Q3 miss or merely in-line print unwinds pre-earnings positioning
- Libre recall litigation escalates beyond current settlements
- Exact integration stumbles; leverage constrains buybacks and raises rate sensitivity
- Respiratory-testing comps keep pressuring Diagnostics comparables
- Reported-growth optics mask mid-single-digit organic growth insufficient for the new capital structure
What to watch
- Q3 print Oct 21: adj EPS, comparable sales growth vs 6.5-7.5% FY guide, Exact revenue contribution and interest expense
- Net debt / leverage ratio and management deleveraging language
- CGM comparable growth rate and any share commentary vs Dexcom
- FY26/FY27 EPS revision direction after the print
- Any confirmation or denial of diabetes-business separation talk
Verifier notes REVISE · opinion revised once
Unsupported claims
- Bull case cites 'a ~2% dividend' — no dividend yield or dividend-per-share figure appears anywhere in the evidence bundle. The only capital-return data point is '$2.1B returned to shareholders in Q2 via dividends and buybacks,' which does not establish a 2% yield.
Weakly sourced
- 'Matching Barclays/JPM $120 targets' and 'Citi top healthcare pick' rest solely on a single [T4] Perplexity-sourced commentary item; the opinion appropriately hedges the Sturgis settlement ([T4], flagged) but presents the analyst targets as firmer corroboration than the sourcing warrants.
- Forward P/E figures (~17.1–17.6x, 22.1x Dec 2025, 23.5x mid-2025) are tagged [T3/T4] only and underpin the core 'multiple reset' argument; the opinion correctly notes the range, but readers should know no T1/T2 source confirms the multiple history.
Corrections applied
- Remove the '~2% dividend' from the bull case, or replace with the evidence-supported statement that Abbott returned $2.1B to shareholders in Q2 via dividends and repurchases (implying continued, but unquantified, dividend support).
- Soften the analyst-target language to note it comes from secondary commentary rather than confirmed research notes (e.g., 'reported Barclays/JPM $120 targets per press commentary').
Sources (30 · T1 = primary filings)
- T1https://www.abbottinvestor.com/events/event-details/q3-2026-abbott-earnings-conference-call
- T4https://www.tradingview.com/news/tradingview:e8316b139f447:0-abt-q3-26-earnings-revenue-estimate-is-12-99b-usd…
- T4https://www.stocktitan.net/news/ABT/abbott-hosts-conference-call-for-third-quarter-4cw12fwfhw7h.html
- T4https://www.marketbeat.com/earnings/reports/2026-10-21-abbott-laboratories-stock/
- T4https://finance.yahoo.com/healthcare/articles/abbott-hosts-conference-call-third-130000713.html
- T4https://www.perplexity.ai/finance/ABT?comparing=ABT,ANGO,TFX,CNMD,ARAY,OFIX
- T4https://www.perplexity.ai/finance/ABT?comparing=ABT,STE,ZBH,JNJ,GEHC,DXCM
- T4https://au.finance.yahoo.com/news/add-abbott-stock-portfolio-ahead-121200087.html
- T2https://www.reuters.com/business/healthcare-pharmaceuticals/abbott-first-quarter-results-beat-cancer-diagnosti…
- T1https://www.sec.gov/Archives/edgar/data/1800/000162828026028357/R15.htm
- T4https://www.abbott.com/content/dam/corp/abbott/en-us/hub-new/Presentation-Acquisition-of-Exact-Sciences.pdf
- T1https://www.abbottinvestor.com/static-files/040a2210-05dd-4a47-a6a2-3ff50a0690ee
- T4https://www.exactsciences.com/news-events/press-releases/abbott-to-acquire-exact-sciences-a-leader-in-large-an…
- T4https://www.theglobeandmail.com/business/article-abbott-trims-2026-profit-forecast-on-exact-deal-hit-shares-fa…
- T4https://www.zacks.com/stock/news/2940662/how-to-approach-abbott-stock-following-its-sharp-ytd-decline
- T4https://abbott.mediaroom.com/2026-03-20-Abbott-acquisition-of-Exact-Sciences-set-to-close-on-March-23,-2026
- T2https://www.reuters.com/business/healthcare-pharmaceuticals/abbott-recalls-glucose-sensors-after-seven-deaths-…
- T1https://www.fda.gov/medical-devices/medical-device-recalls-and-early-alerts/glucose-monitor-sensor-recall-abbo…
- T1https://www.fda.gov/safety/recalls-market-withdrawals-safety-alerts/abbott-initiates-medical-device-correction…
- T1https://www.fda.gov/medical-devices/medical-device-recalls-and-early-alerts/continuous-glucose-monitoring-cgm-…
- T1https://www.fda.gov/medical-devices/medical-device-recalls-and-early-alerts/abbott-recalls-readers-used-freest…
- T1https://www.fda.gov/safety/recalls-market-withdrawals-safety-alerts/abbott-issues-voluntary-medical-device-cor…
- T2https://www.reuters.com/business/healthcare-pharmaceuticals/abbott-issues-us-device-correction-some-glucose-mo…
- T1https://www.fda.gov/medical-devices/medical-device-safety/medical-device-recalls-and-early-alerts
- T4https://www.abbott.com/en-us/corpnewsroom/strategy-and-strength/q1-progress-positions-Abbott-for-accelerating-…
- T4https://www.abbott.com/content/dam/corp/abbottglobal/en-us/hub-new/26-116361-GMEA-EXT-Q1-2026-Earnings-Infogra…
- T4https://www.abbott.com/en-us/corpnewsroom/strategy-and-strength/abbotts-Q2-2026-earnings-call
- T4https://www.abbott.com/content/dam/corp/abbottglobal/en-us/hub-new/26-117191-GMEA-EXT-Q2-2026-Earnings-Infogra…
- T1https://www.sec.gov/Archives/edgar/data/1800/000162828026048377/abt-2026q2xexhibitx991.htm
- T4https://finance.yahoo.com/healthcare/articles/abbott-laboratories-q2-earnings-call-150448485.html
Want a fresh look at ABT, or another name?
Queue a new deep-research run. Published to the feed when done.
Automated research opinion, published as-is on Oct 14, 2026. Not personalised advice. Figures use end-of-day closes.