Lean bullish into the Q3 print.
Thesis
Bull case
Search proves durable through the AI transition (revenue still +17-19%, AI features claimed incremental to queries), Cloud sustains 50%+ growth with expanding margins as the reported $460B+ backlog converts, and the antitrust tail risk is gone post-Brinkema. If management signals 2027 capex flattening and FCF inflecting positive, the market re-rates the stock from a capex-burdened AI spender to a contracted-revenue AI landlord — T4-sourced consensus targets imply ~21% upside with credible paths to $450+ (Needham) on ~23x clean FY27 EPS.
Bear case
The capex treadmill accelerates: 2027 spending guided above $205B, FCF stays negative through 2027, and depreciation compresses the 36.1% consolidated operating margin just as the 2026 equity marks create brutal 2027 EPS comparisons. Search growth is the bull case's most fragile leg — every supporting data point is self-reported by Google, and no independent source confirms AI chatbots aren't eroding query share; if Search decelerates below low-teens while capex rises, the market applies a lower multiple to lower-quality earnings simultaneously. The search-remedies appeal could also restore harsher data-sharing terms.
What would change our mind
- Q3 shows Search & Other growth decelerating below ~12% while management concedes AI-driven query mix shift is hurting monetization
- 2027 capex commentary implies spending above ~$210B without a commensurate backlog increase — confirming speculative overbuild
- Cloud backlog declining sequentially or recognition timeline pushed out
- Appellate court reinstating structural search remedies (breakup-adjacent)
- FY27 consensus EPS revisions turning negative — would convert this from multiple compression to estimate deterioration
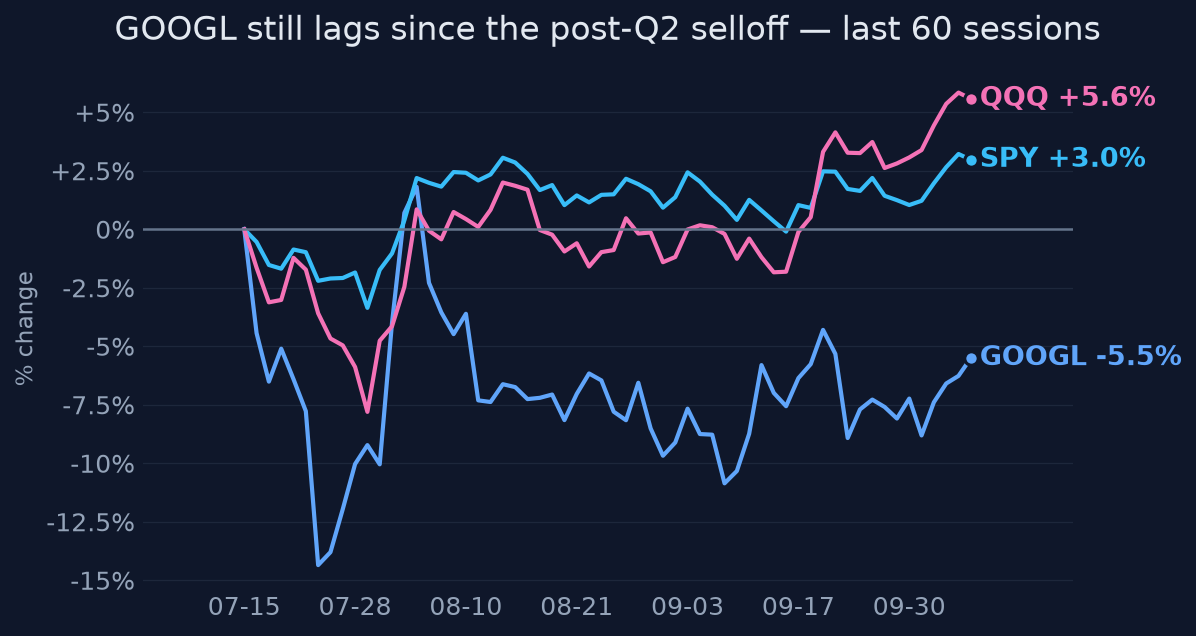
Since publication vs SPY · closed horizons are frozen
The full research everything the view rests on
Direct answer to the question asked
Where the edge would come from
What the price assumes
The price appears to assume continued heavy capex with uncertain returns: the stock has gone sideways for 3 months (-2.3%) despite fundamental acceleration, sitting 13% below its 52-week high after selling off on the Q2 capex raise. Consensus targets of $425-430 imply ~21% upside [T4 only], suggesting the Street is more constructive than the tape. Note that headline 2026 consensus EPS (~$20.6) is meaningless — inflated by a one-time $6.26/share equity gain in Q2 — so any screen-based valuation using 2026 GAAP is distorted.
Why the market may be wrong
The market may be over-weighting the capex/FCF optics and under-weighting that (a) the AI buildout is reportedly backed by signed backlog rather than speculative capacity, in an industry that is capacity-constrained, not oversupplied [T2 Reuters]; and (b) the two structural bear cases have weakened — Search revenue is still growing double-digits with AI features claimed to be incremental to queries, and the September 2026 ad-tech ruling removed the divestiture tail risk. Conversely, bulls may be wrong that the equity marks are stable — the one-time Anthropic/SpaceX gain that inflated Q2 2026 EPS can reverse, similar marks may or may not recur in other quarters, and they will make year-over-year comparisons ugly in 2027.
The one thing to watch
Ignore reported EPS — 2026 GAAP earnings are polluted by a one-time $6.26/share Q2 venture markup (with similar marks possible in other quarters) that can reverse — and instead watch one thing on October 28: any management commentary on 2027 capex plans, expected but not confirmed as formal guidance. The reported Cloud backlog ($462-514B, with management claiming a majority recognizable within 24 months — a T4-sourced figure with internal conflicts) means the current capex may already be substantially sold; the stock re-rates if 2027 capex merely plateaus, and de-rates only if spending rises again without matching backlog growth. The most debated variable — AI chatbot query-share erosion — has so far shown no financial impact in the reported numbers (Search & Other +17% Q2 2026, +19% Q1 2026), though no independent query-share data exists to confirm this, so it remains a live risk rather than a resolved one.
Key evidence (10)
- Q2 2026 (Jul 22, 2026): revenue $119.8B, reported EPS $9.11 — but $6.26 of that was a one-time $99B equity-securities gain (Anthropic/SpaceX markups); core EPS ~$2.85-2.90 [T1 SEC exhibit]
- Search & Other revenue +17% Q2 2026, +19% Q1 2026; ad revenue $81.6B [T1/T2 Reuters]
- Cloud revenue +63%+ to $20B+, Cloud operating margin ~32.9% (vs. 36.1% consolidated); backlog reported at $462-514B with management indicating just over half recognizable within 24 months — sources conflict on exact figures, verify against Q2 10-Q [T1/T4]
- 2026 capex guidance raised to $195-205B (from $180-190B); Q2 capex $44.9B; Q2 FCF negative -$5.9B [T1]
- Ad-tech case: Judge Brinkema rejected AdX divestiture Sept 2026; behavioral remedies + 6-year compliance monitor instead [T2-adjacent]
- Search case: Mehta's Dec 2025 remedies (data-sharing, syndication, distribution limits, no breakup) under appeal by both sides since Jan-Feb 2026 [T4]
- AI adoption self-reported: AI Mode >1B MAU, AI Overviews >2.5B MAU, Gemini app ~950M MAU [T4, company-reported only; no independent confirmation]
- Industry is capacity-constrained, not oversupplied [T2 Reuters, Jul 2026]
- Street: consensus target ~$425-430 across ~55 analysts, high $515, low $310; revisions net upward [T4 only]
- Price context: +40% 1Y vs SPY +16%, but -2.3% 3M and 13% below 52w high; RSI 53, neutral technicals
Catalysts and risks
Catalysts
- Q3 2026 earnings call October 28, 2026 — expected (not confirmed) management commentary on 2027 capex plans, FCF trajectory, backlog conversion
- Q4 2026 earnings February 2, 2027 (consensus EPS est ~$3.46, revenue ~$146B)
- Search-case remedies appeal rulings (timing uncertain)
- EU General Court proceedings on Google's challenge to AI/search access orders (filed Sept 29, 2026)
- Potential marks (up or down) on Anthropic/SpaceX stakes in future quarters
Risks
- 2027 capex commentary above $205B extends negative FCF and triggers another selloff — and the Oct 28 call may not even provide formal 2027 guidance, deferring resolution
- Search deceleration from AI chatbots finally appearing in revenue — currently unverifiable with independent data
- Cloud backlog concentration in a few AI labs (e.g., Anthropic) creates counterparty/circularity risk if AI-lab funding tightens
- Equity marks reversing, creating headline EPS declines that confuse screens; the Q2 gain was one-time and may not repeat
- Appeals restoring harsher search remedies; new Gemini-related securities suit (weakly sourced, T4)
- Evidence gaps: Cloud growth cited as both 63% and 82%; backlog cited as both $462B and $514B; consensus EPS data internally contradictory (FY26 $20.6 vs FY27 $15.1); the 24-month backlog conversion claim is T4-only
What to watch
- Any 2027 capex figure or directional language on the Oct 28 call — plateau vs. increase is the re-rate/de-rate trigger, if offered at all
- FCF trajectory and management's language on capex-to-revenue ratios
- Cloud backlog sequential change and conversion commentary (and reconciliation of the $462B vs $514B discrepancy)
- Search & Other growth rate vs. the 17-19% trend
- Whether equity-security gains/losses swing headline EPS again (affects screens and retail sentiment)
- Any independent third-party search-share data (currently absent from the evidence)
Market snapshot when the call was made 2026-10-07
Price
| Return 1w | +1.9% |
| Return 1m | +3.6% |
| Return 3m | -2.3% |
| Return 6m | +10.5% |
| Return 1y | +40.0% |
| From 52-week high | -12.9% |
| Realized vol, 20d | 24.3% |
| SPY 3m / 1y | +3.4% / +15.7% |
| QQQ 3m / 1y | +4.8% / +24.7% |
Technicals
GOOGL technicals as of 2026-10-07: last close $350.50; 20d SMA 344.48 (neutral); 50d SMA 345.66; 12d EMA 345.10; 26d EMA 344.45; RSI 14 52.9 (balanced); 20d vol 24.2%; volume x0.8 vs 20d avg
Next earnings: 2027-02-02 AMC
Verifier notes REVISE · opinion revised once
Unsupported claims
- most_differentiated_insight: 'Query-share data ... has shown zero financial impact for eight consecutive quarters' — the evidence bundle contains no eight-quarter query-share or search-impact series. The only Search data points are +17% Q2 2026 and +19% Q1 2026 [T1/T2], plus the general statement that no independent query-share data exists at all. The precise 'eight consecutive quarters' figure is fabricated and does material work in the opinion: it is used to dismiss the single most debated bear variable as 'least decision-relevant.'
- Catalysts/answer: the October 28 print delivering 'the first 2027 capex guidance' is asserted as fact. The evidence confirms only the call date (Oct 28, 2026) and frames a 2027 capex guide as something to 'watch,' not a confirmed agenda item. The entire decisive-event framing depends on this unconfirmed assumption.
- most_differentiated_insight: '~$6.26/quarter of venture markups' implies a recurring per-quarter figure; the evidence documents a single one-time $99B gain in Q2 2026 lifting EPS by $6.26. Whether similar marks occurred in other quarters is not in the evidence.
Weakly sourced
- 'Backlog majority recognizable within 24 months' and the $460B+ backlog figure rest on T4 sources (blog.google investor presentation, third-party summaries) with the evidence itself flagging conflicts ($462B vs $514B). The opinion does acknowledge the conflict, but the 'pre-sold capex' thesis leans heavily on this T4-only conversion claim.
- Consensus targets (~$425-430, 55 analysts, high $515/low $310) and 'revisions net upward' are T4-only; acceptable since the opinion tags them, but the 21% upside argument rests entirely on these.
Internal inconsistencies
- Minor: the bear case cites depreciation compressing 'the 36% operating margin' while the thesis cites Cloud at '~33% operating margins' — both are evidence-supported (36.1% consolidated vs 32.9% Cloud), but the juxtaposition without labeling could confuse; not decision-changing.
Corrections applied
- Replace 'eight consecutive quarters' with what the evidence supports, e.g.: 'query-share fears have shown no financial impact in the reported numbers through Q2 2026 (Search & Other +17% Q2, +19% Q1), though no independent query-share data exists to confirm this.'
- Soften the catalyst language to 'potential first 2027 capex guidance on the Oct 28 call' or 'management commentary on 2027 capex plans,' acknowledging the guidance is expected, not confirmed.
- Reword '~$6.26/quarter of venture markups' to 'a one-time $6.26/share Q2 markup (with similar marks possible in other quarters)' to avoid implying a documented recurring quarterly figure.
Sources (35 · T1 = primary filings)
- T4https://abc.xyz/investor/events/event-details/2026/2026-Q2-Earnings-Call-2026-GgTAq7Is0z/default.aspx
- T2https://www.reuters.com/business/google-quarterly-cloud-revenue-growth-beats-expectations-2026-07-22/
- T4https://abc.xyz/investor/events/event-details/2026/2026-Q1-Earnings-Call-2026-nW8kCrBAKS/default.aspx?_sp=5eee…
- T4https://blog.google/company-news/inside-google/message-ceo/alphabet-earnings-q2-2026/
- T4https://www.alphaspread.com/security/nasdaq/googl/investor-relations/earnings-call/q1-2026
- T4https://www.digitalapplied.com/blog/google-ai-search-shift-industry-analysis-may-2026
- T4https://blog.google/company-news/inside-google/message-ceo/alphabet-earnings-q1-2026/
- T4https://finchannel.com/google-at-28-the-search-company-is-becoming-an-ai-company/136517/tech-2/2026/09/
- T4https://www.bamsec.com/companies/1652044/alphabet-inc/transcripts
- T1https://www.sec.gov/Archives/edgar/data/1652044/000165204426000043/googexhibit991q12026.htm
- T4https://abc.xyz/investor/
- T1https://www.sec.gov/Archives/edgar/data/1652044/000165204426000066/googexhibit991q22026.htm
- T4https://www.stocktitan.net/sec-filings/GOOGL/8-k.html
- T2https://www.reuters.com/business/google-challenges-eu-orders-open-up-ai-search-engine-rivals-2026-09-29/
- T1https://www.sec.gov/Archives/edgar/data/1652044/000119312526251733/d160205dfwp.htm
- T4https://www.investing.com/news/transcripts/earnings-call-transcript-alphabet-beats-q2-2026-estimates-shares-fa…
- T4https://ca.investing.com/news/transcripts/earnings-call-transcript-alphabet-beats-q2-2026-estimates-shares-fal…
- T4https://au.investing.com/news/transcripts/earnings-call-transcript-alphabet-beats-q2-2026-estimates-shares-fal…
- T4https://blog.google/alphabet/investor-presentation-june-2026/
- T1https://www.sec.gov/Archives/edgar/data/1652044/000119312526257724/d83560dex991.htm
- T2https://www.reuters.com/business/meta-sell-excess-ai-computing-capacity-via-cloud-business-bloomberg-news-repo…
- T4https://financebuzz.com/news/googl-stock-what-investors-should-know
- T4https://technologychecker.io/blog/google-cloud-statistics-report
- T4https://www.midgardfinance.com/research/cloud/
- T4https://techora.ru/news/google-cloud-vyruchka-vzletela-na-82-2026-09-25
- T4https://www.indmoney.com/blog/us-stocks/gemini-4-argon-vs-openai-anthropic-ai-race
- T4https://www.beri.net/article/google-cloud-82-percent-growth-enterprise-ai-supply-constraints-2026
- T4https://finance.yahoo.com/technology/ai/articles/googles-ai-chips-set-sent-140002514.html
- T4https://www.zacks.com/stock/research/GOOGL/price-target-stock-forecast
- T4https://www.marketbeat.com/stocks/NASDAQ/GOOG/forecast/
- T4https://www.perplexity.ai/finance/GOOGL/analysis
- T4https://www.zacks.com/stock/research/GOOG/price-target-stock-forecast
- T4https://247wallst.com/investing/2026/10/07/wall-street-says-429-for-alphabet-our-model-sees-500/
- T4https://247wallst.com/investing/2026/10/06/alphabet-has-the-biggest-upside-in-the-mag-7-right-now-64/
- T4https://www.investing.com/equities/google-inc-consensus-estimates
Want a fresh look at GOOGL, or another name?
Queue a new deep-research run. Published to the feed when done.
Automated research opinion, published as-is on Oct 8, 2026. Not personalised advice. Figures use end-of-day closes.