Q3 is priced as a formality — 2027 credibility is the real test.
Thesis
Bull case
Q3 MCR ≤89.5-90% on underlying (ex-PYD) basis, FY26 guidance nudged toward $20+, management credibly addresses the stars shortfall with benefit/rate offsets, membership losses at or below the expected ~11%, and Optum Health margin commentary confirms organic repair. Stock closes the gap toward peers' recovery multiples: at 19-20x FY27 $22.61, that's $430-450 (+14-19%).
Bear case
The 'beat' comes only via reserve development again, commercial cost pressure (flagged at Q2) worsens, 2027 membership exits exceed expectations, or DOJ language escalates. FY27 consensus of $22.61 proves 10-15% too high; at 15-16x a $20 FY27 number the stock is $300-320 (-15-20%). The unresolved DOJ criminal inquiry is a fat left tail no multiple argues against.
What would change our mind
- Q3 underlying MCR (ex-PYD) above ~90.5% or guidance reaffirmed only by lowering Q4 quality
- FY27 consensus revisions turning net-negative after the print — would confirm the market's distrust was correct
- Any DOJ charging/settlement news material enough to impair Optum or UHC economics
- Stock failing to rally on a clean print would signal the discount is structural, not informational
Since publication vs SPY · closed horizons are frozen
The full research everything the view rests on
Direct answer to the question asked
Where the edge would come from
What the price assumes
Q3: adj. EPS ~$4.12-4.15 (+41% YoY off a depressed base), revenue ~$111.3-111.4B, MCR ~90.1% — a level that implies the market assumes give-back from Q2's 86.7%, which was reportedly flattered by ~$860M favorable reserve development [T4-only figure]. FY26: $19.87 consensus within the $19.50-20.00 guide, Q3 slightly heavier than Q4 per management. FY27: ~$22.61 (+14%), which the price action suggests the market does not fully believe.
Why the market may be wrong
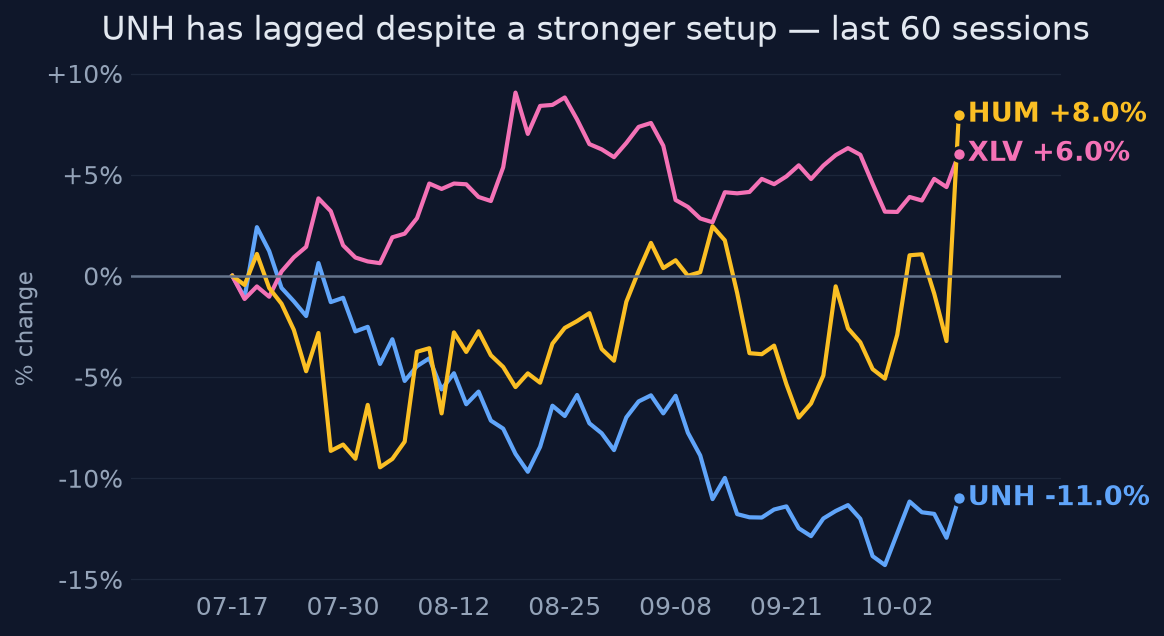
Two directions. Bearish-correct: Q2's beat was contaminated by prior-year development, stars fell to ~67% of members in 4+ star plans (JPM est. vs 81% prior), MA membership expected to shrink ~11%, and DOJ civil/criminal requests remain open — so FY27 $22.61 could be 10%+ too high. Bullish-correct: the stars disappointment and membership exits are already disclosed and arguably in the price (stock fell while estimates rose 11:0), peers (HUM +125% in 6M) show the market pays for credible MA recovery, and UNH's $5B buyback plus ~19x implied FY26 P/E on guidance midpoint leaves little needed for a relief move on mere reaffirmation.
The one thing to watch
The variable to watch is not the Q3 MCR print but its composition: consensus of 90.1% already bakes in give-back, so the stock moves on whether management frames underlying trend (ex-reserve development) as consistent with FY27 consensus of ~$22.61 — a clean 90%+ MCR with credible 2027 offsets beats a sub-90% print achieved via reserve releases.
Key evidence (8)
- Q2 2026 (Jul 16): adj EPS $6.38, op earnings $8.0B (+55% YoY), FY26 guidance raised to $19.50-20.00, buybacks raised to ≥$5B [T1 SEC earnings release]
- Q2 MCR of 86.7% flattered by ~$860M favorable reserve development; Q3 consensus 90.1% implies give-back [T4 aggregators — flag as non-primary]
- FY26 consensus $19.87 / FY27 $22.61 with 11 up / 0 down revisions in the month to Sep 23 (Zacks) [T4]
- 2027 star ratings: ~67% of UHC MA members in ≥4-star plans per JPM estimate vs ~81% prior; industry-wide 37% of MA-PD contracts ≥4 stars vs 44.4% [T4, JPM estimate not company disclosure]
- DOJ civil and criminal requests outstanding, company cooperating (company-confirmed historically); reported Texas AG probe weakly sourced [T4/T5]
- Peers: HUM MBR 91.2% with 7-8% cost trend, ELV +80bps on government business, CI better than expected — sector cost pressure real but within plans [T2/T4]
- Price $377: +47% off 52w low, -13% off high, -11.6% over 3M despite guidance raise; forward P/E 16.6-17.8x vs historical 15.2-22.8x [market data]
- 20-day realized vol at 5th percentile of trailing year — pre-earnings compression [quant analysis]
Catalysts and risks
Catalysts
- Q3 2026 earnings Oct 13, 2026 pre-market (tomorrow)
- 2027 MA rate notice and final star-ratings economics clarity (Q4 2026)
- DOJ investigation developments (timing unknown)
- Q4 2026 report Jan 25, 2027 with initial FY27 guidance
- Peer Q3 prints (ELV, HUM, CI) over coming weeks as sector cost-trend confirmation
Risks
- Reserve-development-dependent beats eroding trust in reported MCR
- 2027 MA stars/membership economics worse than the ~67%/11% already assumed
- DOJ civil/criminal escalation — unquantifiable tail
- Commercial cost pressure persisting beyond expectations
- Optum margin recovery reliant on portfolio shuffling (WellMed stake sale) rather than organic improvement
What to watch
- Q3 MCR split between current-period and prior-period development
- Management's first explicit FY27 framework language (membership, stars offsets, rate adequacy)
- Optum Health operating margin vs the ≥$2.2B segment target trajectory
- FY26/FY27 estimate revision direction in the 2 weeks post-print
- ELV/HUM/CI Q3 MCR prints as sector trend cross-check
- Any DOJ or state AG headlines
Market snapshot when the call was made 2026-10-09
Price
| Return 1w | +2.0% |
| Return 1m | -2.3% |
| Return 3m | -11.6% |
| Return 6m | +25.4% |
| Return 1y | +4.6% |
| From 52-week high | -13.1% |
| Realized vol, 20d | 19.1% |
| SPY 3m / 1y | +3.9% / +15.7% |
| QQQ 3m / 1y | +5.5% / +22.9% |
Technicals
UNH technicals as of 2026-10-09: last close $379.30; 20d SMA 374.92 (bearish); 50d SMA 389.18; 12d EMA 375.31; 26d EMA 379.59; RSI 14 51.6 (balanced); 20d vol 18.6%; volume x1.5 vs 20d avg
Next earnings: 2027-01-25 AMC
Verifier notes REVISE · opinion revised once
Unsupported claims
- market_expectation states consensus MCR of 90.1% is 'explicitly assuming Q2's 86.7% was flattered by ~$860M favorable reserve development' — the evidence frames this as an inference ('Consensus of 90.1% for Q3 *implies* the market already assumes give-back', planner digest), not an explicit assumption by analysts. The word 'explicitly' overstates what the evidence supports; the $860M figure itself is also T4-only (aggregator-sourced), which the opinion correctly flags in key_evidence but presents more assertively in market_expectation.
Weakly sourced
- The ~$860M favorable reserve development figure rests solely on T4 aggregator sourcing. The opinion does flag this in key_evidence, which is adequate, but the answer/market_expectation fields repeat it without the caveat — minor, acceptable if the 'explicitly' wording is fixed.
Corrections applied
- In why_market_may_be_wrong: '19% implied FY26 P/E on guidance midpoint' is a units error — it should read '~19x implied FY26 P/E on guidance midpoint' ($377 / $19.75 midpoint ≈ 19.1x, per the planner digest). As written, '19%' is a nonsensical valuation figure that will confuse readers.
- In market_expectation and answer: change 'explicitly assuming' to 'implying the market assumes' (or similar) for the 90.1% MCR give-back framing, to match the evidence's inferential language rather than asserting analysts explicitly stated the assumption.
Sources (23 · T1 = primary filings)
- T4https://www.tradingview.com/news/gurufocus:ba1276267094b:0-unitedhealth-q3-earnings-preview-what-to-expect-fro…
- T4https://www.zacks.com/stock/news/3003072/unitedhealth-gears-up-for-q3-earnings-should-investors-buy-the-stock
- T4https://tickeron.com/blogs/unitedhealth-group-unh-q3-2026-earnings-what-investors-should-watch-18622/
- T4https://www.marketbeat.com/earnings/reports/2026-10-13-unitedhealth-group-incorporated-stock/
- T4https://www.hudson-labs.com/research/unitedhealth-q3-2026-earnings-preview-unh-guidance-margins
- T4https://www.perplexity.ai/finance/UNH/earnings
- T4https://finance.yahoo.com/quote/UNH/
- T4https://www.tipranks.com/news/unitedhealth-q3-earnings-tomorrow-3-make-or-break-factors-for-unh-stock
- T3https://www.cnbc.com/2026/07/29/humana-hum-earnings-q2-2026.html
- T4https://policy.humana.com/news-and-resources/news-press/2026/humana-reports-second-quarter-2026-financial-resu…
- T1https://www.sec.gov/Archives/edgar/data/49071/000004907126000045/a2q2026humanaincpostedrema.htm
- T4https://finance.yahoo.com/quote/HUM/earnings/HUM-Q2-2026-earnings_call-550046.html
- T1https://s202.q4cdn.com/665319960/files/doc_financials/2026/q2/2Q2026ELVSupplementalEarningsPresentation.pdf
- T4https://www.investing.com/news/transcripts/earnings-call-transcript-humana-beats-estimates-in-q2-2026-shares-f…
- T4https://www.oliverwyman.com/our-expertise/insights/health-insurer-financial-insights.html
- T4https://finance.yahoo.com/quote/0J6Z.L/earnings/0J6Z.L-Q2-2026-earnings_call-550046.html
- T4https://uk.investing.com/news/stock-market-news/unh-earnings-preview-key-metrics-and-estimates-ahead-of-q3-202…
- T4https://finance.yahoo.com/healthcare/articles/unitedhealth-4-star-medicare-enrollment-025506980.html
- T4https://www.hfma.org/payment-reimbursement-and-managed-care/2027-medicare-advantage-star-ratings/
- T4https://www.zacks.com/stock/news/3001305/unitedhealth-q3-coming-up-two-questions-investors-cant-ignore
- T4https://www.healthcaredive.com/news/medicare-advantage-stars-2027-winners-losers/832582/
- T4https://www.tradingkey.com/analysis/stocks/us-stocks/262208384-unitedhealth-unh-stock-forecast-october-9-2026-…
- T4https://www.perplexity.ai/finance/UNH
Want a fresh look at UNH, or another name?
Queue a new deep-research run. Published to the feed when done.
Automated research opinion, published as-is on Oct 12, 2026. Not personalised advice. Figures use end-of-day closes.