Neither — there's no up-move.
Thesis
Bull case
The bear case is fully priced after a 65% drawdown: RSI 33, vol at the 22nd percentile, and price sitting on the 200d SMA is a classic mean-reversion setup. Regulatory overhang is now resolved in XRP's favor — the CFTC chair named it a digital commodity [T1], the SEC case is history, and US spot ETFs exist and hold ~1.19B XRP. If the CFTC ANPRM matures into formal commodity-market rules over 3-6 months, RLUSD issuance keeps compounding (+$765M in Q3), Evernorth's 473M XRP treasury deploys in Q4 as stated, and ETF flows mean-revert even to September's pace, the same 1.67 beta that hurt on the way down amplifies any BTC recovery — and shorts leaning on the escrow overhang get squeezed.
Bear case
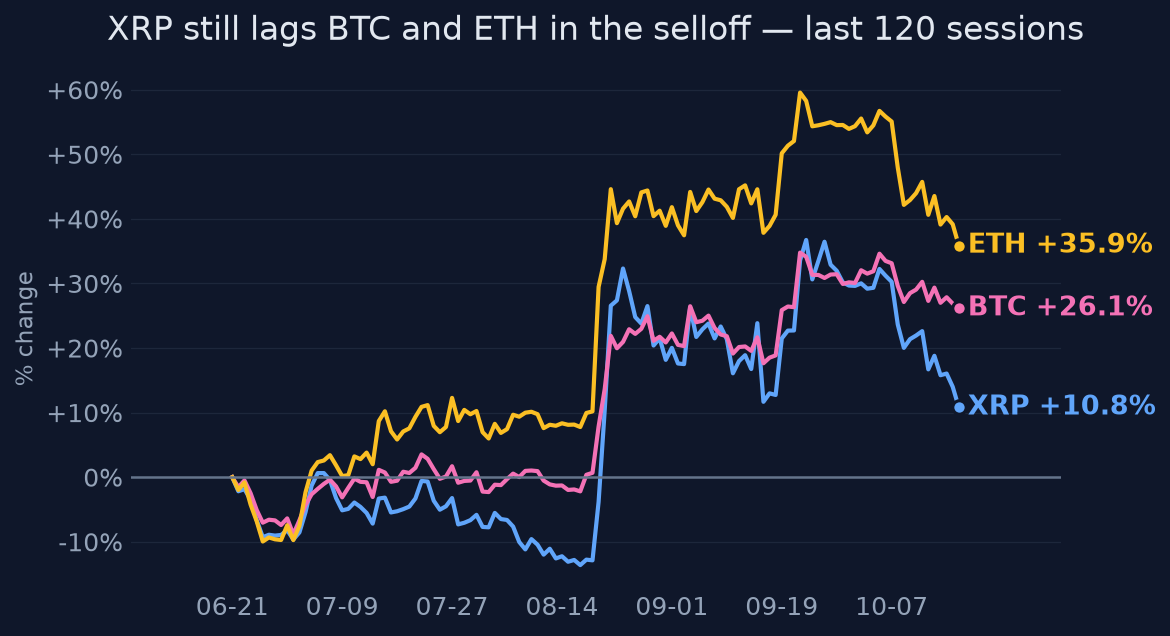
XRP is an $80B market cap supported by ~$286K/year of chain fees with no staking yield, no buyback, and no mechanism linking Ripple's enterprise success or RLUSD growth to token demand — the valuation is a pure monetary-premium bet on continued retail/ETF absorption of Ripple's monthly escrow releases. That absorption is failing: ETF flows down 75% MoM and negative in the last week, whale deposits to Binance at 7-month highs, spot buyer volume reportedly down sharply after the liquidation cascade. FDV is 1.6x market cap with 31.4B XRP still to be distributed; every relief rally since July 2025 has been sold, and the token underperforms BTC, ETH, and SOL on every window. If BTC itself corrects, XRP's 1.67 beta with weak idiosyncratic support means it falls further than the market.
What would change our mind
- Weekly spot ETF net inflows re-accelerate above ~$30M/week for 3+ consecutive weeks — would show the October slump was noise, not trend
- XRPL fee/revenue trend becomes economically material (e.g., 30d fees sustained >$1M) rather than base-effect noise
- RLUSD on-XRPL share rises above 50% with growing active addresses, demonstrating ledger-native demand
- Ripple announces and verifies a structural change to escrow release policy (e.g., burns, longer re-escrow) reducing the net monthly supply
- Price reclaims the 50d SMA with volume expansion — would negate the 'every rally sold' pattern
Since publication vs BTC · closed horizons are frozen
No price data after the entry date yet.
The full research everything the view rests on
Direct answer to the question asked
Where the edge would come from
What the price assumes
At $80B market cap / $127B FDV, the market still prices XRP as a top-5 monetary network whose institutional payment rails and ETF bid will eventually monetize. The price implies continued structural demand absorbing ~200-300M XRP/month of net escrow releases, and treats RLUSD growth as XRPL-native value accrual.
Why the market may be wrong
The marginal buyer that justified the 2025 premium — ETF flows — has slowed ~75% MoM with the last five sessions negative, while the sell-side schedule (1B XRP gross monthly unlocks) is mechanical and known. Meanwhile RLUSD, the headline adoption story, is 58% on Ethereum, only 42% on XRPL, with active addresses reportedly down ~40% over 30 days — growth in Ripple's stablecoin does not require or accrue to XRP. Consensus conflates Ripple/RLUSD headlines with XRP token demand.
The one thing to watch
The scan's premise is inverted — the variable that matters isn't whether this 'move' is real, it's that the one verifiable structural bid (spot ETF flows: $121M in September → ~$13M in October 1-15) is evaporating into a mechanical monthly supply schedule; watch weekly ETF net flows against the Nov 1 unlock, not price momentum.
Key evidence (10)
- Price $1.27: -9.1% 1w, -8.4% 30d, -44.6% 1y, -65.1% below ATH of $3.65 (Jul 17, 2025); 1m z-score 0.1; 20d vol 38.4% at 22nd percentile [CoinGecko, 2026-10-18]
- Below 20d/50d/200d SMAs, RSI 33.1, bottom of 20d range — oversold downtrend, not a breakout [computed, 2026-10-18]
- 60d BTC correlation 0.90, beta 1.67, idiosyncratic share 18%; relative strength vs BTC -17% over 6m [computed from daily closes]
- XRPL TVL $38.3M (-51% 1y) vs $80.35B mcap (~2,100x); fees $502/24h, $34K/30d, $286K/1y; FDV/annualized revenue ~307,000x [DefiLlama, 2026-10-18]
- Spot ETF flows: ~$13M Oct 1-15 vs ~$121M in September (-75%); last five sessions slightly negative; cumulative ~$1.8B, ~1.19B XRP held [T4 reports, unverified against primary flow series]
- Escrow: 1B XRP gross released Oct 1, 2026; next 1B unlock Nov 1, 2026; ~31.4B XRP (31.4% of supply) still in Ripple escrow; net monthly inflation historically ~200-300M XRP [T4 cluster]
- CFTC Chairman Selig explicitly named XRP among 'digital commodities' in Oct 5, 2026 remarks; ANPRM issued but comment-stage only, no binding classification [cftc.gov press release 9307-26, opaselig12 — T1]
- RLUSD ~$2.4B total mcap (+$765M Q3) but 58% on Ethereum / 42% on XRPL; RLUSD active addresses reportedly -40% over 30d [T4 rwa.xyz-derived]
- Week's decline was a leverage flush: $600M+ XRP liquidations from the $1.50-1.60 rejection, long/short ratio ~2.3:1, spot turnover reportedly collapsed afterward [T4 cluster]
- Whale flows contradictory: ~1.67B XRP cumulative deposits to Binance over 30d (7-month high) vs. reports of exchange withdrawals and falling Binance reserves — direction unconfirmed [T4]
Catalysts and risks
Catalysts
- Nov 1, 2026: next scheduled 1B XRP escrow unlock (gross; watch net re-escrow amount)
- XRPL fixCleanup3_4_0 amendment targeted ~Oct 23, 2026 (maintenance; lending/privacy amendments still lack validator support)
- CFTC ANPRM comment period (~60 days from Federal Register publication) and any follow-on rulemaking formalizing digital-commodity treatment
- Q4 2026: Evernorth 473M XRP treasury strategy initial deployment (announced, unconfirmed)
- Weekly spot ETF flow prints — whether October's -75% deceleration reverses or extends
- Ripple enterprise/RLUSD announcements that demonstrably route volume through XRP rather than around it
Risks
- ETF flow deceleration hardens into sustained outflows while monthly unlocks continue
- Whale deposits to Binance (1.67B XRP/30d) convert to actual distribution
- BTC beta: XRP falls ~1.7x any broad crypto drawdown with no fundamental floor beneath it
- Escrow overhang: 31.4B XRP (31.4% of supply) still in Ripple hands; FDV 1.6x mcap
- RLUSD adoption migrates further toward Ethereum, severing the last plausible demand narrative
- Key flow/whale evidence rests on T4 sources and is internally contradictory — the bear tilt could be resting on stale or mislabeled wallet data
What to watch
- Weekly XRP spot ETF net flows vs the Nov 1 escrow release — the core supply/demand balance for the next 90 days
- Net re-escrowed amount from each monthly unlock (gross 1B vs net ~200-300M)
- Binance whale-deposit metric: does the 1.67B XRP inflow turn into falling price on rising exchange balances
- RLUSD supply split XRPL vs Ethereum and active-address trend
- CFTC rulemaking progression past the comment stage
- XRP/BTC ratio — relative strength is the cleanest test of whether an idiosyncratic bid exists at all
Market snapshot when the call was made 2026-10-18
Price
| Return 1w | -9.1% |
| Return 1m | -1.7% |
| Return 3m | +16.6% |
| Return 6m | -11.2% |
| Return 1y | -44.5% |
| From 52-week high | -51.9% |
| Realized vol, 20d | 38.4% |
| BTC 3m / 1y | +25.1% / -23.9% |
| ETH 3m / 1y | +26.9% / -38.4% |
| QQQ 3m / 1y | +2.0% / +17.9% |
Technicals
Verifier notes PASS
Weakly sourced
- ETF flow deceleration (-75%, $121M Sep -> $13M Oct 1-15) and whale/liquidation figures rest on T4 sources and are stated flatly in the direct_answer and bear_case; however, the opinion explicitly flags this in key_evidence, risks ('Key flow/whale evidence rests on T4 sources and is internally contradictory'), and caps conviction at a lean partly for this reason — disclosure is adequate, not a material finding.
Sources (24 · T1 = primary filings)
- T4https://app.rwa.xyz/assets/RLUSD
- T1https://docs.ripple.com/products/payments-odl/introduction/concepts/on-demand-liquidity/onboarding-overview
- T1https://docs.ripple.com/products/payments-odl/introduction/products
- T1https://docs.ripple.com/products/payments-odl/introduction/use-cases
- T1https://docs.ripple.com/products/payments-odl/user-interface/payments/payment-details
- T4https://xrp-insights.com/xrp-radar
- T4https://en.coinotag.com/ripples-rlusd-adds-765-3-million-q3-xrp-ecosystem
- T4https://cryptonews.net/market-cap/ripple-usd/news/
- T4https://247wallst.com/investing/cryptocurrency/2026/10/12/xrp-traders-are-leaning-long-by-two-to-one-and-whale…
- T4https://cryptorank.io/news/feed/144da-xrp-whales-send-167-billion-tokens-to-binance-as-seven-month-high-inflow…
- T4https://finance.yahoo.com/markets/crypto/articles/why-did-xrp-price-drop-213009532.html
- T4https://thecryptobasic.com/tag/ripple/page/395/
- T4https://www.investing.com/analysis/xrp-faces-fresh-liquidation-risk-as-traders-lean-heavily-long-200689522
- T4https://thecryptobasic.com/tag/ripple/page/396/
- T4https://crypto.news/price-prediction/xrp/
- T4https://www.tradingkey.com/news/market-movers/262217639-market-movers-xrpusd-20261015
- T1https://www.cftc.gov/PressRoom/PressReleases/9307-26
- T1https://www.cftc.gov/PressRoom/SpeechesTestimony/opaselig12
- T4https://finance.yahoo.com/markets/crypto/articles/cftc-chairman-michael-selig-says-114000540.html
- T4https://finance.yahoo.com/markets/crypto/articles/cftc-chair-name-drops-6-120241624.html
- T1https://www.cftc.gov/PressRoom/PressReleases
- T4https://finance.yahoo.com/markets/crypto/articles/cftc-chairman-expresses-disappointment-congress-100052588.ht…
- T4https://finance.yahoo.com/markets/crypto/articles/cftc-lists-xrp-stellar-digital-180022199.html
- T4https://www.sidley.com/en/insights/newsupdates/2026/10/cftc-seeks-comment-on-proposed-federal-framework-for-re…
Want a fresh look at XRP, or another name?
Queue a new deep-research run. Published to the feed when done.
Automated research opinion, published as-is on Oct 18, 2026. Not personalised advice. Figures use end-of-day closes.