Mostly yes — cheap re-rating, unproven.
Thesis
Bull case
The disruption thesis has no reported evidence behind it: FY26 grew revenue 14% and EPS 20%, margins expanded to 27.4%, and guidance was reaffirmed or raised throughout the year with a Q4 beat. At 14-15x forward — roughly half last year's multiple — even modest re-rating toward the low-20s on a mid-teens Online Ecosystem print implies $415-430, in line with the aggregator-cited analyst target cluster, with AI product launches (Intuit Intelligence, Sequence) as upside optionality.
Bear case
The rally is multiple re-expansion ahead of evidence, on thin volume, into overbought technicals, while the only hard revision data points down: FY27 EPS estimates cut ~16% (T4-sourced), guidance below consensus, and revenue decelerating to 9-10%. The free Credit Karma Tax launch risks cannibalizing TurboTax, and if FQ1 Online Ecosystem lands at or below the 11-13% guide, the AI-erosion thesis gets its first confirmation and the stock gives back the 24% bounce.
What would change our mind
- FQ1 FY27 Online Ecosystem growth prints at or below 11% (bottom of guide) — confirms deceleration is real, not conservative
- Total FQ1 revenue misses the $4.294B low end of guidance
- FY27 non-GAAP EPS guidance is cut below $22.88 at or after the FQ1 print
- Management discloses TurboTax pricing pressure or subscriber loss attributable to AI or free-filing competition
Since publication vs SPY · closed horizons are frozen
No price data after the entry date yet.
The full research everything the view rests on
Direct answer to the question asked
Where the edge would come from
What the price assumes
At ~14-15x forward EPS with a 'Hold' consensus and average target of $431.55 (aggregator data), the market is pricing INTU as a decelerating, AI-vulnerable franchise: 9-10% FY27 growth with risk that AI commoditizes tax prep and bookkeeping. The recent rally suggests some investors are beginning to price the opposite — that AI is a margin and product lever for Intuit, not just a threat — but the multiple still embeds substantial skepticism versus history.
Why the market may be wrong
The bear case rests on a disruption that has produced no observable damage in reported results — a clean FY26 record of reaffirmed or raised guidance capped by a Q4 non-GAAP EPS beat of $0.55-0.61 versus guidance. Meanwhile the selloff cut the forward multiple ~48% while the fundamental revision direction was only modestly negative. If the AI-disruption thesis is wrong or merely slow, the asymmetry between a 14x multiple on 10-15% guided growth and INTU's historical 20x+ range favors the upside. The risk is the market is early: the rally is a 1.9-sigma move on 0.7x volume with RSI 78.5, and the confirming data point doesn't arrive until late November.
The one thing to watch
The variable that matters is not the AI announcements or the stock's momentum — it is the spread between Online Ecosystem's FY26 actual growth (23% ex-Mailchimp) and its FY27 guide (11-13%). Management has already guided to a deceleration sharper than any AI damage observed so far, which means the bar at the FQ1 print is low: a mid-teens print simultaneously beats the guide and disproves the disruption thesis. Watch that one line, not the headline EPS.
Key evidence (10)
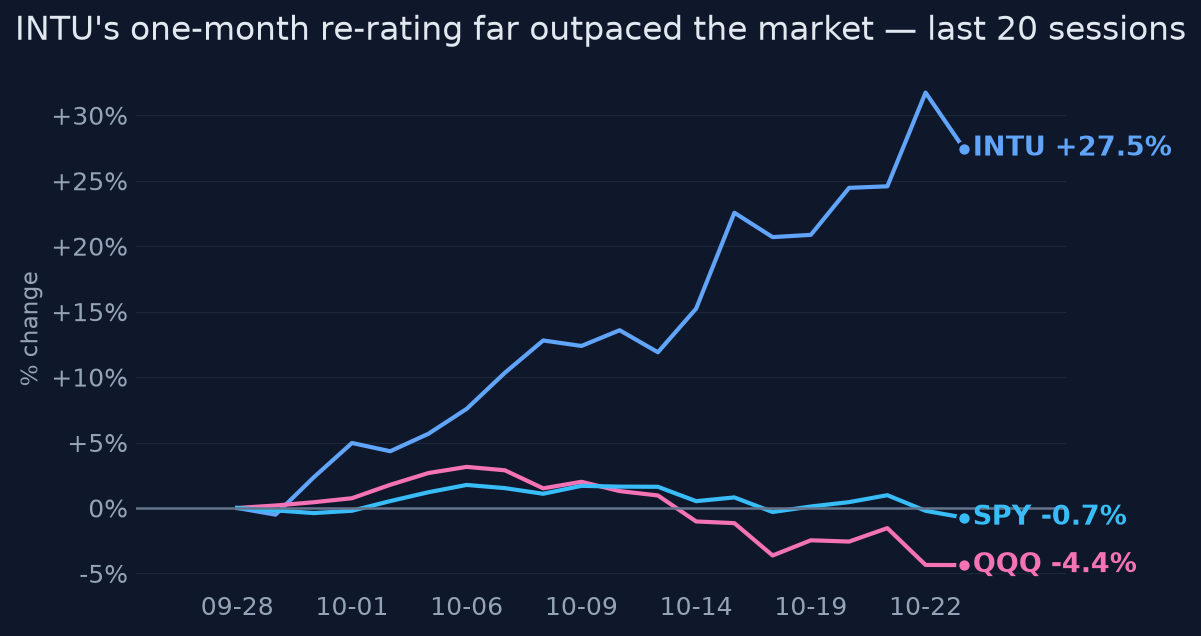
- Price $343.39 as of 2026-10-23: +24% 1-month (1.9-sigma vs own history), still ~50% below 52-week high; move is 98-99% idiosyncratic vs SPY/QQQ [computed from price history]
- RSI 78.5 (overbought), volume ~0.7x 20-day average — rally lacks volume confirmation [technicals, 2026-10-23]
- FY2026 (reported Aug 25, 2026): revenue +14% to $21.4B, GAAP EPS +20% to $16.46, non-GAAP EPS $24.27, operating margin 27.4% [Intuit IR press release]
- FY26 guidance record: reaffirmed at Q2, raised at Q3, and Q4 non-GAAP EPS beat guidance by $0.55-0.61 — no reported misses during the fiscal year [Intuit Q2/Q3/Q4 FY26 earnings scripts]
- FY27 guidance (reaffirmed Sept 17, 2026 Investor Day): revenue $23.28-23.51B (+9-10%), non-GAAP EPS $22.88-23.12, below the ~$23.14 consensus cited [Intuit IR; FactSet via T4]
- Forward P/E ~14.4-14.9x on 2026-10-26 vs 28.9x on 2025-10-31 — ~48% multiple compression; near the low end of recent historical observations, though the displayed range included a reading as low as ~11.6x [Yahoo/YCharts, T4]
- FY27 EPS estimates reportedly cut ~15.8% over two months to mid-Oct 2026 [Zacks-derived, T4 — weakly sourced; treat direction, not magnitude, as reliable]
- October catalysts are narrative, not data: Sequence acquisition (Oct 15), Intuit Intelligence international rollout (Oct 14), Credit Karma Tax free filing (Oct 20) [Intuit IR press releases]
- FQ1 FY27 guide: revenue $4.294-4.313B (+11%), non-GAAP EPS $2.44-2.48; Online Ecosystem FY27 guide +11-13% vs 23% ex-Mailchimp in FY26 [Intuit IR]
- Analyst stance mixed: aggregator consensus Hold (16 Buy/12 Hold/3 Sell), avg target $431.55; BofA downgrade, Wells Fargo cut to $300, Citi upgrade to $416 [MarketBeat, T4]
Catalysts and risks
Catalysts
- FQ1 FY27 earnings report, expected late November 2026 (quarter ended Oct 31, 2026) — the decisive test
- Tax season kickoff and early TurboTax vs Credit Karma Tax free-filing data (Jan-Feb 2027)
- Sequence acquisition integration updates and any disclosed contribution to QuickBooks revenue
- Further analyst revisions following the FQ1 print
Risks
- FQ1 Online Ecosystem growth at or below the 11-13% guide confirms deceleration and validates the bear case
- Credit Karma Tax free filing cannibalizes TurboTax paid revenue with no data available until tax season
- FY27 EPS revision trend remains negative, undercutting the re-rating
- Rally is technically overextended (RSI 78.5, low volume) and could mean-revert before the print
- Key consensus figures rest on T4 aggregators and conflict ($23.14 vs $24.18 FY27 EPS); the 15.8% estimate-cut figure is weakly sourced
What to watch
- Online Ecosystem revenue growth in the FQ1 print vs the 11-13% FY27 guide (the one number)
- Total FQ1 revenue vs $4.294-4.313B guide
- Consumer segment commentary on Credit Karma Tax vs TurboTax cannibalization
- FY27 EPS estimate revision direction into and after the print
- Volume confirmation on any further upside — current rally is on 0.7x average volume
Market snapshot when the call was made 2026-10-23
Price
| Return 1w | +5.6% |
| Return 1m | +23.9% |
| Return 3m | +13.0% |
| Return 6m | -13.3% |
| Return 1y | -48.8% |
| From 52-week high | -49.8% |
| Realized vol, 20d | 39.2% |
| SPY 3m / 1y | +2.8% / +13.8% |
| QQQ 3m / 1y | +3.3% / +16.3% |
Technicals
INTU technicals as of 2026-10-23: last close $343.39; 20d SMA 306.17 (bearish); 50d SMA 321.12; 12d EMA 325.90; 26d EMA 316.36; RSI 14 78.5 (overbought); 20d vol 37.6%; volume x0.7 vs 20d avg
Verifier notes REVISE · opinion revised once
Unsupported claims
- Claim that INTU delivered 'five straight quarters of meeting or beating' is not established by the evidence. The bundle shows only the Q4 FY26 beat (EPS above guidance by $0.55-0.61), Q3 raising full-year guidance, and Q2 reaffirming guidance — that is at most three quarters of non-negative guidance events, and no per-quarter beat/miss data for the earlier quarters is provided. Stating five consecutive beats as fact overstates the evidence.
Weakly sourced
- The '$415-431 analyst target cluster' leans on T4 aggregators (MarketBeat avg $431.55, Susquehanna $415, Citi $416) — acceptable but should be framed as aggregator data; this is partially handled via the T4 tags in key_evidence.
- 'Near the bottom of its historical range' for the 14-15x forward multiple slightly overstates the evidence: the Yahoo valuation table showed a historical observation of 11.61x, so the current multiple is near the low end but not demonstrably at the bottom of the range. Minor.
Corrections applied
- Replace 'five straight quarters of meeting or beating' with 'a clean FY26 record of reaffirmed or raised guidance and a Q4 EPS beat' (the only sequence the evidence documents), or qualify it as 'no reported misses during FY26'.
- Soften 'near the bottom of its historical range' to 'near the low end of its recent historical observations (the displayed range included a reading as low as ~11.6x)' to match the evidence exactly.
Sources (21 · T1 = primary filings)
- T4https://investors.intuit.com/news-events/press-releases
- T4https://investors.intuit.com/?os=v&ref=app
- T4https://www.marketbeat.com/instant-alerts/filing-intuit-inc-intu-stock-purchased-by-valley-national-advisers-i…
- T4https://investors.intuit.com/news-events/press-releases/rss
- T4https://www.marketbeat.com/instant-alerts/filing-intuit-inc-intu-position-raised-by-fifth-third-wealth-advisor…
- T4https://www.marketbeat.com/instant-alerts/filing-25119-intuit-inc-intu-shares-sold-by-investment-house-llc-202…
- T4https://www.marketbeat.com/stocks/NASDAQ/INTU/
- T4https://investors.intuit.com/?cid=sf9756196
- T4https://investors.intuit.com/_assets/_82269698e57f0291e947d183719775e9/intuit/db/946/10372/webcast_transcript/…
- T4https://investors.intuit.com/_assets/_adeb6ebfcf2348669b1a1ac5c5ff6997/intuit/db/946/10372/webcast_transcript/…
- T4https://investors.intuit.com/_assets/_47c34c4bdc3a2daa838f135a69c13d29/intuit/db/946/10378/webcast_transcript/…
- T4https://investors.intuit.com/_assets/_fa7265d705ec84a3fce05c07cf47b9c0/intuit/db/946/10372/webcast_transcript/…
- T4https://investors.intuit.com/_assets/_ccdc4fc950973e539f955445da5aebe2/intuit/db/946/10372/webcast_transcript/…
- T4https://investors.intuit.com/_assets/_b47bef62c2922576cfc0ce6fc96bb015/intuit/db/946/10378/webcast_transcript/…
- T4https://investors.intuit.com/_assets/_106c1ae70fa96d064cbb05421d4c9e2a/intuit/db/946/10358/webcast_transcript/…
- T4https://investors.intuit.com/_assets/_106c1ae70fa96d064cbb05421d4c9e2a/intuit/db/946/10378/webcast_transcript/…
- T4https://investors.intuit.com/news-events/press-releases/detail/1320/intuit-reports-fourth-quarter-and-full-yea…
- T4https://investors.intuit.com/_assets/_d1b813ae4ad6df627b81cc50c660e407/intuit/news/2026-09-17_Intuit_Hosts_Inv…
- T4https://investors.intuit.com/_assets/_91b55db72fe57b96da1c1a33fb4e55ed/intuit/db/946/10378/webcast_transcript/…
- T4https://investors.intuit.com/_assets/_106c1ae70fa96d064cbb05421d4c9e2a/intuit/news/2026-08-25_Intuit_Reports_F…
- T4https://investors.intuit.com/_assets/_47c34c4bdc3a2daa838f135a69c13d29/intuit/news/2026-09-17_Intuit_Hosts_Inv…
Want a fresh look at INTU, or another name?
Queue a new deep-research run. Published to the feed when done.
Automated research opinion, published as-is on Oct 26, 2026. Not personalised advice. Figures use end-of-day closes.