Cheap, but prove it in December.
Thesis
Bull case
The market has priced a permanent impairment from what may be a transition year. EPS of ~$9.60 absorbs peak tariffs, proxy costs, and SG&A deleverage that a new CEO can attack directly; O'Neill's Nike women's-business track record fits LULU's core problem. Inventory is controlled (-7% units), the balance sheet funds ~7% of the market cap in buybacks at these prices, and the single-digit multiple means mere stabilization (comps flattening, FY27 EPS holding ~$10) supports $110-130. Analyst targets at the stock price with an exhausted seller base (vol at 13th percentile) is historically where de-ratings end.
Bear case
The share loss is structural, not cyclical: Alo/Vuori are taking the exact premium customer LULU monetized, China growth decelerated to +4% from prior 20-30%+, and the cost structure was built for 15-20% growth that no longer exists. If FY27 EPS is really $8.42 (the MarketWatch snapshot) rather than $10.95, the stock at $92 is 11x a still-declining number with a fourth guidance cut plausible in December — fair value is the bear-target cluster of $70-82, i.e., another 10-25% down. The Q2 'beat' was tariff-refund-flattered; underlying trends were worse than headlines.
What would change our mind
- Bullish-stabilization view is invalidated if Q3 (Dec) comes in below the -10-11% revenue guide or FY26 EPS is guided below $9.48, or if O'Neill offers no cost-base action — that confirms the broken-growth regime and points to the $70-82 bear cluster
- Bearish view is invalidated if December shows Americas comps inflecting toward flat AND management frames FY27 with margin recovery (tariff mitigation + SG&A leverage), which would put $10-11 FY27 EPS on a 9x stock
Since publication vs SPY · closed horizons are frozen
The full research everything the view rests on
Direct answer to the question asked
Where the edge would come from
What the price assumes
The Street has fully capitulated: 12+ brokerages cut targets after September 3, and post-cut targets ($70-$106, clustered at $82-$95) sit right around the current $92 price — consensus sees neither upside nor downside. FY27 EPS estimates are contradictory across sources ($10.95 vs $8.42, likely GAAP-vs-adjusted), but even the bull-ish snapshot implies the market prices flat-to-modest-recovery earnings, not a return to the $13-14 EPS of FY2024-25.
Why the market may be wrong
Two directions. Bullish: consensus may be extrapolating a tariff-and-transition year as permanent — FY26 EPS of ~$9.60 includes proxy-contest costs, peak SG&A deleverage, and gross tariff headwinds ($380M) that mitigation and pricing could partially recover in FY27; if normalized EPS is $10-11, the stock is at 8-9x with a buyback shrinking the share count. Bearish: consensus may still underestimate structural share loss (the T4-sourced 10pp share decline to Alo/Vuori, if accurate, implies revenue erosion persists into FY27) and the FY27 'recovery' embedded even in the $10.95 snapshot may not materialize, making $8.42 the truer number — in which case the stock is not cheap at all.
The one thing to watch
The headline Q2 'EPS beat' ($2.92 vs $1.79 est.) and the reported ~530bps operating-margin decline both flatter reality: the margin figure includes a 130bps one-time tariff-refund benefit, so underlying margin erosion is ~660bps — the earnings floor is softer than the print suggests. The variable to watch in December is therefore not comps (everyone watches comps) but whether O'Neill announces a structural SG&A reset; if she reframes the cost base while revenue merely stabilizes, FY27 consensus re-rates upward without any demand recovery at all.
Key evidence (9)
- FY26 guidance cut three times: March 17 (below estimates), June 4 (revenue flat to -1%), Sept 3 (revenue -5% to -7%, $10.35-10.5B; EPS $9.48-9.73 from $10.95-11.15) [Reuters, T2]
- Q2 FY26 (Sept 3): revenue $2.42B (-4.3% y/y), Americas comps -12%, China +4%; Q3 guided to revenue -10% to -11% and EPS $0.93-0.98 [Reuters/company, T2/T1]
- FY26 outlook embeds ~530bps operating-margin decline INCLUDING a 130bps one-time tariff-refund benefit; SG&A +450bps; gross margin -80bps; gross US tariff impact ~$380M vs $275M in 2025 [Q2 transcript, T4 relaying company statements]
- SEC XBRL: FY2025 revenue $11.1B, EPS $13.26 (from $14.64 FY2024 peak); operating margin fell 23.7% to 19.9% [T1]
- Balance sheet: ~$1.4B cash, no debt surfaced, $593M revolver capacity, ~$713M buyback remaining; ~2.7M shares repurchased in Q2; FY26 capex guided $680-700M [Q2 supplement/SEC, T1/T4]
- CEO transition: Heidi O'Neill (ex-Nike president of consumer/product/brand) announced April 22, started Sept 8, 2026 — five days after the guidance cut; McDonald exited amid activist/founder (Chip Wilson) pressure [Reuters, T2]
- Share loss data: LULU US athleisure share reportedly fell ~10pp to 43.9% by Aug 2026 with Alo/Vuori gaining — sourced only to T4 outlets, treat as directional, not verified
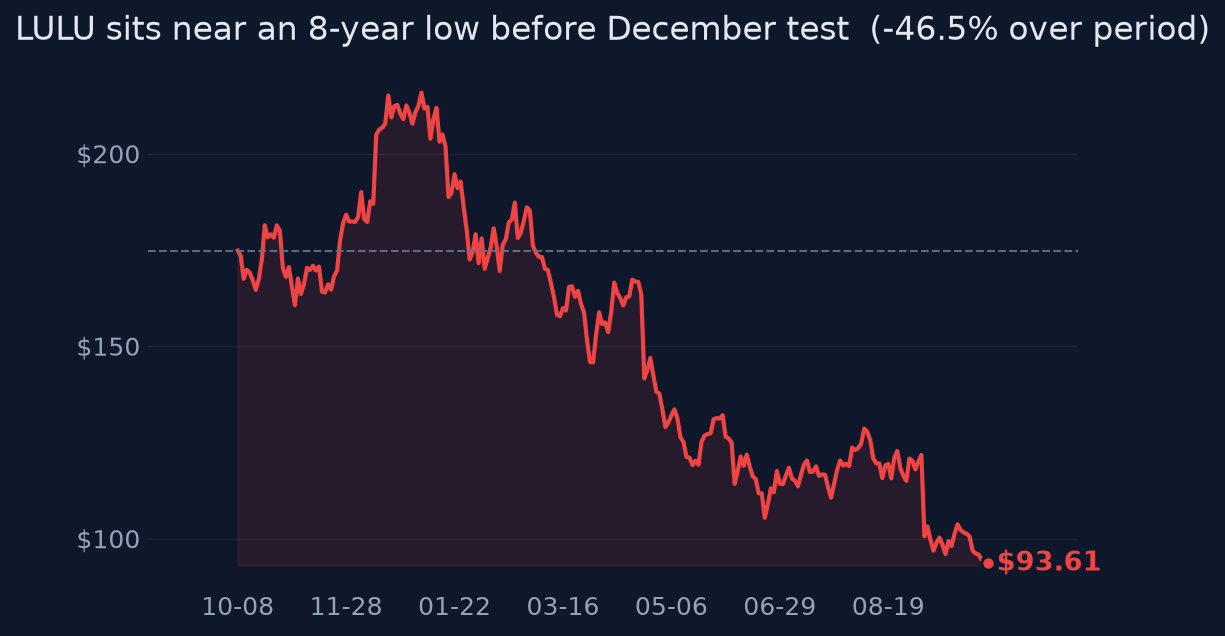
- Price: -47% 1yr, -57% below 52wk high, 0.5% above 52wk low; 20-day realized vol at 13th percentile — quiet grinding de-rating, not active capitulation [market data]
- Post-cut analyst targets: MS $83 UW, BMO $70 Underperform, Truist $82, JPM $95 (from $154), Wells $95, UBS $106 [Investing.com relaying notes, T4]
Catalysts and risks
Catalysts
- Q3 FY2026 earnings (~early-mid December 2026): first full quarter under O'Neill; guided to revenue -10-11%, EPS $0.93-0.98 — a fourth cut vs stabilization is the binary
- O'Neill's initial strategy disclosure: product pipeline, marketing reset, and critically any SG&A restructuring announcement
- Holiday 2026 sell-through and any read on whether the -12% Americas comps inflect
- Tariff policy developments and mitigation/pricing actions affecting the ~$380M gross headwind
- Founder Chip Wilson / activist follow-through post-CEO change — could force larger strategic action (board seats, asset review)
Risks
- Fourth consecutive guidance cut in December, confirming estimates are still too high
- Structural share loss to Alo/Vuori proves durable; the T4-sourced 10pp share decline is directionally confirmed by -12% comps
- FY27 EPS consensus ($10.95 vs $8.42 discrepancy) resolves to the low end, meaning the stock is not actually cheap
- China growth continues decelerating, removing the offset to North America weakness
- O'Neill's Nike pedigree cuts both ways: Nike itself has suffered share/revenue problems; market was unimpressed at appointment
- Tariff escalation beyond the current $380M assumption
What to watch
- December Q3 print vs the $0.93-0.98 EPS and -10-11% revenue guide — the single deciding event in this horizon
- Any SG&A restructuring or cost-out announcement from O'Neill — more important than comps for FY27 EPS trajectory
- Estimate revision momentum: whether FY27 consensus stops falling (currently $10.95, down from $12.28) — the de-rating ends when revisions stop, not when comps improve
- Americas comparable sales trajectory and inventory discipline (currently well-controlled at -7% units)
- China growth rate — watch for stabilization above or breakdown below the +4% Q2 level
- Buyback pace: acceleration at these prices would signal management's own view of value; ~2.7M shares/quarter is the baseline
- Third-party share data (Alo/Vuori gains) from higher-tier sources to confirm or refute the T4-sourced 10pp decline
Market snapshot when the call was made 2026-10-06
Price
| Return 1w | -3.4% |
| Return 1m | -7.0% |
| Return 3m | -17.6% |
| Return 6m | -39.1% |
| Return 1y | -46.7% |
| From 52-week high | -56.6% |
| Realized vol, 20d | 33.3% |
| SPY 3m / 1y | +4.5% / +16.4% |
| QQQ 3m / 1y | +6.8% / +25.9% |
Technicals
LULU technicals as of 2026-10-06: last close $93.61; 20d SMA 98.43 (bearish); 50d SMA 111.03; 12d EMA 97.35; 26d EMA 101.85; RSI 14 44.5 (balanced); 20d vol 31.5%; volume x0.9 vs 20d avg
Verifier notes PASS
Corrections applied
- Minor factual slip in thesis: it says the last guidance cut came with 'a management team with one week of tenure' — the evidence shows the Sept 3 cut actually preceded O'Neill's Sept 8 start by five days (she was CEO-designate, not yet in role). The error arguably strengthens the point rather than weakening it, but should be corrected to 'a CEO who had not even started at the time of the last cut.'
- Minor rounding: 'the $13-14 EPS of FY2024-25' — SEC XBRL shows $14.64 (FY2024) and $13.26 (FY2025); '$13-15' or '$13.26-14.64' would be exact. Not decision-relevant.
- Nuance: thesis states 'no debt' flatly while the evidence only surfaces 'no debt figure' in retrieved materials; the opinion's own key_evidence correctly says 'no debt surfaced' — align the thesis phrasing with that hedge.
Sources (24 · T1 = primary filings)
- T4https://corporate.lululemon.com/~/media/Files/L/Lululemon/investors/results-center/q2-2026-financial-supplemen…
- T2https://www.reuters.com/business/retail-consumer/lululemon-forecast-cut-hits-shares-underscores-challenge-next…
- T1https://www.sec.gov/Archives/edgar/data/1397187/000139718726000020/lulu-20260201.htm
- T4https://corporate.lululemon.com/~/media/Files/L/Lululemon/investors/results-center/q2-2026-earnings-infographi…
- T2https://www.reuters.com/business/retail-consumer/lululemon-cuts-annual-revenue-profit-forecast-2026-09-03/
- T4https://corporate.lululemon.com/newsroom/press-releases/2026/09-03-2026-210528733
- T1https://www.sec.gov/Archives/edgar/data/1397187/000139718726000077/lulu-20260503xex991.htm
- T4https://www.investing.com/news/analyst-ratings/morgan-stanley-cuts-lululemon-stock-price-target-on-guidance-co…
- T4https://www.ringly.io/discover/activewear-market-statistics-2026
- T4https://fortune.com/2026/09/12/lululemon-new-ceo-heidi-oneill-leggings-sales-decline-nike-mess/
- T4https://www.investing.com/news/transcripts/earnings-call-transcript-lululemon-q2-2026-profit-beat-fails-to-cal…
- T4https://www.rte.ie/news/business/2026/0904/1590289-lululemon-cuts-full-year-outlook-again/
- T4https://www.thestreet.com/retail/lululemon-q2-earnings-underperform-stock-rating
- T4https://www.theglobeandmail.com/investing/markets/stocks/LULU/pressreleases/4524338/lululemon-lulu-q2-2026-ear…
- T4https://www.companieshistory.com/lululemon-competitors/
- T4https://www.marketresearchfuture.com/reports/athleisure-market/companies
- T2https://www.reuters.com/sustainability/sustainable-finance-reporting/lululemon-says-it-picks-former-nike-execu…
- T2https://www.reuters.com/sustainability/boards-policy-regulation/lululemon-athletica-founder-chip-wilson-raises…
- T2https://www.reuters.com/business/after-bitter-proxy-fight-lululemon-ceo-could-use-war-chest-revamp-bruised-bra…
- T2https://www.reuters.com/sustainability/boards-policy-regulation/lululemon-shares-drop-new-ceo-appointment-leav…
- T2https://www.reuters.com/sustainability/sustainable-finance-reporting/lululemon-forecasts-annual-revenue-profit…
- T2https://www.reuters.com/business/retail-consumer/lululemon-cuts-annual-revenue-forecast-2026-06-04/
- T4https://fintool.com/app/research/companies/LULU/documents/transcripts/q1-2026
- T4https://corporate.lululemon.com/~/media/Files/L/Lululemon/investors/results-center/q1-2026-financial-supplemen…
Earlier and later calls on LULU
- Oct 28, 2026Mostly no — it's noise.Lean bearishview changed
- Sep 7, 2026Yes — both, hard. Differently priced.Neutralview changed
Want a fresh look at LULU, or another name?
Queue a new deep-research run. Published to the feed when done.
Automated research opinion, published as-is on Oct 7, 2026. Not personalised advice. Figures use end-of-day closes.