Yes fundamentally, but entry is stretched.
Thesis
Bull case
Azure is re-accelerating (43%→45% CC guided) into still-unmet demand with $100B+ annual scale, margins are expanding through the capex cycle (46.8% op margin), and revisions momentum is one-directional. If capacity additions convert backlog into revenue while capex plateaus near $50B/quarter, FCF inflects upward in FY27, FY28 EPS of $23.55 gets revised higher, and even a flat 25x multiple implies ~$590 within 12-18 months — with the Wells Fargo $700 scenario requiring only that the AI run-rate disclosures keep compounding. The Jan/Apr selloffs look, in hindsight, like the market forcing management to prove monetization — which the July print arguably did.
Bear case
The bear case is arithmetic, not narrative: $175-190B annual capex with ~2/3 in short-lived assets means depreciation and FCF compression are locked into FY27-28 regardless of demand quality, and management itself flagged memory-cost margin pressure. Copilot unit economics remain undisclosed and unproven against the spend; the OpenAI relationship is becoming less exclusive; and the two 2026 selloffs prove this shareholder base will re-rate the stock violently on any capex-versus-growth disappointment. Buying at RSI 86 after a 25% monthly ramp, 8% below the high, with the binary Q1 FY27 print ~10 weeks away, is paying full price for unresolved risk. A repeat of the January playbook from this base implies 15-20% downside to the ~$410-445 moving-average zone.
What would change our mind
- Q1 FY27 Azure growth decelerates below ~40% CC while capex exceeds ~$50B — confirms the worst version of the spend-without-acceleration thesis
- Operating cash flow minus capex fails to inflect upward by the Q2 FY27 print (Jan 2027) — the FCF compression is structural, not transitional
- FY27 consensus EPS ($19.70) starts getting revised down — the 43:1 upgrade streak reversing would break the momentum leg of the thesis
- Stock breaks below the 50d SMA (~$411) on an earnings reaction — signals the market re-entering punishment mode; a fundamental holder should reassess, not average blindly
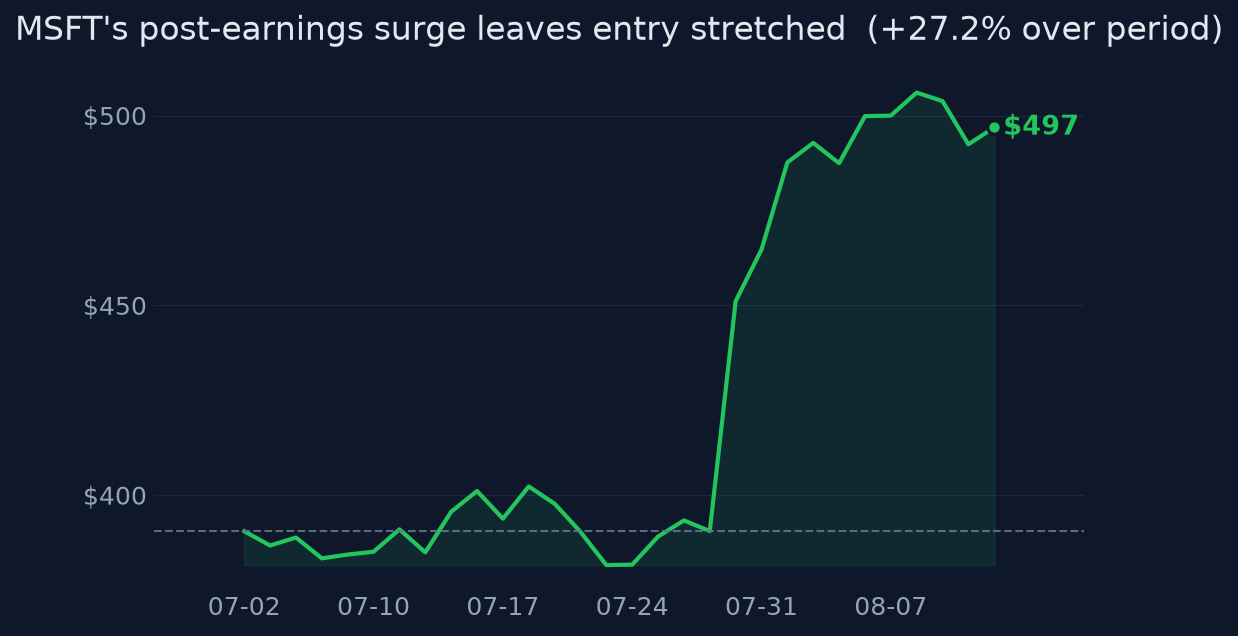
Since publication vs SPY · closed horizons are frozen
The full research everything the view rests on
Direct answer to the question asked
Where the edge would come from
What the price assumes
The price appears to assume the July narrative holds: Azure stays ≥40% CC, capex remains 'elevated but controlled' (~$50B+/quarter), and AI cash flow keeps validating the spend. Consensus target ~$561 (+13%) with 42 Buy / 5 Hold implies the street sees moderate upside, not a re-rating — i.e., the market has already moved from fear to guarded confidence. Notably, the stock is still -6% over 1y vs SPY +21%, so the market has NOT yet forgiven the capex regime; it has only paused the punishment.
Why the market may be wrong
Two-sided. Bearish surprise risk: the market is treating one quarter of 'spending plans unchanged' as resolution, when Q2 FY26 operating cash flow roughly equaled capex ($37.5B) and ~2/3 of capex is short-lived GPUs — the depreciation and FCF compression wave hits FY27-28 reported numbers regardless of demand. If Q1 FY27 (late Oct) shows capex creeping above ~$50B or Azure decelerating even to low-40s, the January/April playbook (punish first, ask later) likely repeats against an RSI-86 starting point. Bullish surprise risk: if Azure capacity additions let growth hold ≥45% while capex plateaus, the FCF inflection arrives earlier than modeled and 25x FY27 proves cheap against upward-revised FY28 numbers.
The one thing to watch
Stop watching Azure growth — it's already good and known. The single variable that now moves this stock is the gap between operating cash flow and capex: the -35% drawdown was caused by that gap narrowing to ~zero in Q2 FY26, and the rally was caused by one quarter of reassurance about it. Every earnings print for the next 3-6 months is a referendum on that spread, not on demand. If OCF minus capex inflects upward, the stock grinds to and through $561; if it widens negatively again, the same investors who fled in January will flee from a higher, more overbought base.
Key evidence (11)
- FY2026 (ended June 30, 2026, SEC XBRL [T1]): revenue $331.8B (+18%), diluted EPS $17.95 (+32%), operating margin 46.8% — margin expansion during peak capex
- Q4 FY26 (July 29, 2026, Microsoft IR/Reuters [T1/T2]): revenue $90.0B (+18%, beat), adj. EPS $4.74 vs $4.24 expected — large beat that drove ~25% one-month rally
- Azure +43% CC in Q4 FY26, surpassed $100B annual revenue; Q1 FY27 guided ~45% CC; demand still exceeds capacity (Microsoft IR [T2])
- Capex: ~$50B+ guided for Q1 FY27, ~$175B calendar 2026 reported, FY27 capex guided higher YoY (Reuters [T2])
- Q2 FY26: operating cash flow ≈ capex ($37.5B), ~2/3 of capex in short-lived GPUs/CPUs; FCF fell sequentially (Microsoft IR/Reuters [T2])
- Jan 2026: shares fell 6.5% post-earnings on record AI spend + slower cloud growth; CFO Hood warned memory costs will pressure cloud margins (Reuters [T2])
- Estimate revisions: 43 EPS upgrades vs 1 downgrade over trailing 3 months (Seeking Alpha [T4] — directionally consistent with beat pattern but single-source)
- Consensus: FY27 ~$391B rev / $19.70 EPS; FY28 ~$468B / $23.55 EPS; price ~$497 implies ~25x FY27 / ~21x FY28 (analyst snapshot Aug 14, 2026 [T4], arithmetic verified)
- Analyst targets: consensus ~$561, Evercore $528 Outperform, Wells Fargo $700 Overweight; Stifel downgraded to Hold Feb 2026 on AI spend/Azure margin compression (CNBC [T3], others [T4])
- Technicals (Aug 13, 2026): RSI-14 86.3 (overbought), +25.6% 1m, -8.3% below 52w high, 20d realized vol ~60%, -34.9% max drawdown over 1y, -6.1% 1y vs SPY +21%
- Peer growth figures (Google Cloud ~63%, AWS ~28% vs Azure ~40-43%) rest entirely on [T4] sources — directional only, not verified
Catalysts and risks
Catalysts
- Q1 FY27 earnings (late October 2026): Azure growth vs ~45% CC guide, capex vs ~$50B guide, and any FCF commentary — the single decisive event in the horizon
- Quarterly AI business run-rate disclosure updates (previously $37B)
- Copilot paid-seat / monetization disclosures at Ignite or FY27 prints
- OpenAI partnership restructuring terms — revenue-share changes and exclusivity scope
- Hyperscaler capex commentary from Alphabet/Amazon earnings (sector-wide read-through on AI spend tolerance)
- Any Azure capacity announcements easing the demand-exceeds-supply constraint
Risks
- Capex-vs-FCF narrative flips negative again at the October print — the proven -30%+ drawdown trigger
- Entry-point risk: RSI 86, +25% in a month, low-volume rally (0.6x avg volume) — stretched technically even if fundamentally sound
- Azure gross-margin compression from GPU depreciation and memory costs (CFO-flagged, Stifel's downgrade thesis)
- Copilot monetization fails to visibly scale, reframing AI spend as cost without revenue
- OpenAI dependence: model access, pricing, or competitive terms shift against Microsoft
- Peer figures suggest Google Cloud growing faster (~63%, [T4] only) — enterprise AI share narrative could erode
- Valuation data conflict: sources cite 19.7x to 28x forward P/E [T4]; verified arithmetic says ~25x FY27 — not cheap if growth disappoints
What to watch
- The OCF-minus-capex spread each quarter — the single most predictive variable for this stock's 2026 behavior
- Azure CC growth vs the 45% guide at the late-October print
- Q1 FY27 capex print vs ~$50B; any FY27 total capex guidance language ('higher' vs 'plateauing')
- Copilot seat/revenue disclosures — first hard evidence on software-layer AI monetization
- Estimate revision direction (currently 43 up / 1 down) — a flip precedes multiple compression
- Technical: $505 resistance / 52w-high retest, and whether volume confirms (rally so far on 0.6x average volume)
- OpenAI relationship announcements and any Stifel-style downgrade follow-through from other brokers
Market snapshot when the call was made 2026-08-13
Price
| Return 1w | -0.6% |
| Return 1m | +25.6% |
| Return 3m | +22.6% |
| Return 6m | +22.9% |
| Return 1y | -6.1% |
| From 52-week high | -8.3% |
| Realized vol, 20d | 58.3% |
| SPY 3m / 1y | +4.8% / +21.0% |
| QQQ 3m / 1y | +2.4% / +26.2% |
Technicals
MSFT technicals as of 2026-08-13: last close $496.88; 20d SMA 445.16 (bullish); 50d SMA 411.41; 12d EMA 477.80; 26d EMA 448.52; RSI 14 86.3 (overbought); 20d vol 60.7%; volume x0.6 vs 20d avg
Sources (37 · T1 = primary filings)
- T2https://www.microsoft.com/en-us/investor/earnings/fy-2026-q4/press-release-webcast
- T4https://www.digitalapplied.com/blog/microsoft-fy26-q4-earnings-copilot-arr
- T2https://www.microsoft.com/en-us/investor/events/fy-2026/earnings-fy-2026-q4
- T4https://www.bitget.com/asia/amp/news/detail/12560605567160
- T4https://windowsforum.com/windows-news.4/azure-capacity-remains-constrained-despite-175b-capex.441750/
- T4https://www.metirai.com/blog/microsoft-q4-fy2026-earnings-azure-reacceleration-ai-capex
- T4https://www.investing.com/news/stock-market-news/microsoft-reports-today-all-eyes-on-azure-growth-and-ai-capex…
- T4https://ca.investing.com/analysis/microsoft-q4-earnings-can-220b-in-ai-investment-cement-azures-cloud-dominanc…
- T2https://www.microsoft.com/en-us/investor/events/fy-2026/earnings-fy-2026-q2
- T4https://finance.yahoo.com/quote/MSFT/earnings/MSFT-Q3-2026-earnings_call-547930.html/
- T3https://www.cnbc.com/amp/2026/04/29/microsoft-msft-q3-earnings-report-2026.html
- T4https://www.globaldatacenterhub.com/p/microsoft-q3-fy2026-the-190b-capex
- T2https://www.reuters.com/business/ai-investment-boom-puts-big-techs-free-cash-flow-under-pressure-2026-07-22/
- T4https://finance.yahoo.com/markets/stocks/articles/microsoft-corp-msft-q4-2026-050436699.html
- T2https://www.microsoft.com/en-us/investor/earnings/fy-2026-q2/performance
- T4https://tech-insider.org/google-cloud-82-percent-growth-aws-earnings-2026/
- T4https://www.mindstudio.ai/blog/google-cloud-vs-aws-vs-azure-q1-2026-ai-infrastructure-race
- T4https://www.artificialintelligence-news.com/news/big-tech-ai-infrastructure-spending-q1-2026-results/
- T4https://www.fool.com/investing/2026/08/06/amazon-alphabet-and-microsoft-all-delivered-soaring-cloud-growth-tha…
- T4https://valueaddvc.com/blog/big-tech-q1-2026-earnings-the-numbers-that-defined-the-ai-investment-cycle
- T4https://www.linkedin.com/pulse/google-cloud-grows-63-ai-spending-explodes-crushes-aws-azure-nwbyc
- T4https://aitoolsrecap.com/Comparisons/azure-vs-google-cloud-vs-aws-q2-2026-earnings
- T4https://x.com/trendforce/status/2051960853608435892
- T2https://www.reuters.com/business/retail-consumer/microsoft-edges-past-cloud-growth-expectations-2026-01-28/
- T3https://www.cnbc.com/2026/07/29/microsofts-ai-spending-guide-is-music-to-our-ears-quieting-the-bears-for-now.h…
- T2https://www.reuters.com/business/autos-transportation/investors-punish-big-tech-ai-spending-that-delivers-slow…
- T4https://fortune.com/2026/04/29/microsoft-meta-google-ai-capex-spending-billions/
- T4https://www.investing.com/news/transcripts/earnings-call-transcript-microsoft-q3-2026-results-exceed-expectati…
- T2https://www.microsoft.com/en-us/investor/events/fy-2026/earnings-fy-2026-q3
- T4https://www.businessinsider.com/big-tech-earnings-microsoft-ai-investment-capex-plan-2026-4
- T2https://www.reuters.com/business/us-stock-futures-steady-microsoft-offsets-fed-concerns-2026-07-30/
- T3https://www.cnbc.com/2026/07/30/analysts-react-to-microsofts-earnings-results-.html
- T3https://www.cnbc.com/2026/07/29/microsoft-msft-q4-earnings-report-2026.html
- T2https://www.reuters.com/business/microsoft-tops-quarterly-cloud-growth-estimates-easing-spending-concerns-2026…
- T4https://tickerdaily.com/earnings/msft-q4-fy2026-earnings-preview
- T4https://www.fxleaders.com/news/2026/08/12/microsofts-28x-p-e-paves-way-as-msft-tests-505-resistance/
- T4https://www.theglobeandmail.com/investing/markets/stocks/MSFT/pressreleases/37334463/microsoft-msft-21-analyst…
Earlier and later calls on MSFT
- Oct 26, 2026Modestly attractive into earnings.Lean bullish
- Oct 5, 2026No evidence — no thesis.No clear edgeview changed
Want a fresh look at MSFT, or another name?
Queue a new deep-research run. Published to the feed when done.
Automated research opinion, published as-is on Aug 14, 2026. Not personalised advice. Figures use end-of-day closes.