No clear edge — it's a levered option.
Thesis
Bull case
If credit conditions stabilize, the setup is asymmetric to the upside: $26.3B FY27 consensus revenue against a ~$37B market cap, 59% EBITDA margins, demonstrated sector-wide GPU pricing power, $104B+ backlog with $25B more signed in early Q3, and a JPMorgan $125 target. Bond-yield compression from 15% toward high-single-digits alone could re-rate the equity 50-100%.
Bear case
The equity is a stub on ~$35B+ of debt that keeps growing (capex raised to $35-39B/yr) while EPS estimates fall and the company sells stock and converts into a falling price. A single OpenAI/Microsoft delay, a failed refinancing at 15%+ yields, or an AI-capex pause could force distressed dilution or restructuring; the 5-year debt vs 3-year contract mismatch makes residual GPU value the real collateral question.
What would change our mind
- For bears: unsecured bond yield compresses below ~9-10% while FY27 revenue estimates hold ≥$25B — that combination signals the credit discount was wrong
- For bulls: any contract renegotiation/cancellation by a top-3 customer, or FY27 revenue consensus cut below ~$21B, or bond yields sustained above ~17-18%
- Share count growth materially outpacing the 35M-share ATM plus convert dilution within two quarters
Since publication vs SPY · closed horizons are frozen
No price data after the entry date yet.
The full research everything the view rests on
Direct answer to the question asked
Where the edge would come from
What the price assumes
At ~$70-78 (45% below 52-week high, ~1.4x FY27 consensus revenue on market cap), the price appears to assume continued successful refinancing, no major contract loss, and partial but not full backlog conversion — while embedding a meaningful probability of credit stress, given the ~15% unsecured yield and falling EPS estimates despite rising revenue estimates.
Why the market may be wrong
Two-sided: bears may be wrong because Nebius just demonstrated 17-21% GPU price increases, backlog grew $25B+ in early Q3, and FY27 consensus of $26.3B revenue against a ~$37B cap is cheap if conversion works — the equity could double on any credit-spread normalization. Bulls may be wrong because the financing mismatch (~5-year debt vs ~3-year contracts), OpenAI counterparty/circular-financing exposure, and serial equity issuance could keep compressing the equity stub even if operations deliver.
The one thing to watch
The variable to watch is not revenue or backlog — it is CoreWeave's unsecured bond yield and the pace of share-count growth: with EV dominated by creditor claims, the equity trades as a credit-spread derivative, and the stock only works if the 15% yield compresses before dilution consumes the operating leverage.
Key evidence (8)
- Q2 2026 results (Aug 11, 2026, [T1] SEC/[T2]): revenue $2.58B +112% YoY, adj EBITDA $1.5B (59% margin), backlog $104.2B +246% YoY, GAAP net loss $626M
- FY26 guidance raised: revenue $12.4-13.2B, adj op income $0.96-1.15B, capex raised to $35-39B, year-end run-rate revenue $18.5-19.5B [T1]
- Debt ~$35.6B at 6/30/26; Q2 interest expense ~$640M, Q3 guided to $860-940M; Q2 FCF roughly -$5.7B [T2/T4]
- Oct 14, 2026: ATM program up to 35M shares plus $3B convertible notes due 2033; unsecured bond yield touched ~15% [T4 — offering terms not verified against SEC filings]
- FY27 consensus revenue $26.3B vs market cap ~$37B; FY27 EPS consensus -$4.33, revised down ~29% in 90 days [T4 aggregator data]
- Customer concentration: OpenAI ~$22.4B total commitments, Meta up to $14.2B, heavy Microsoft exposure; no evidence of cancellations [T2/T3]
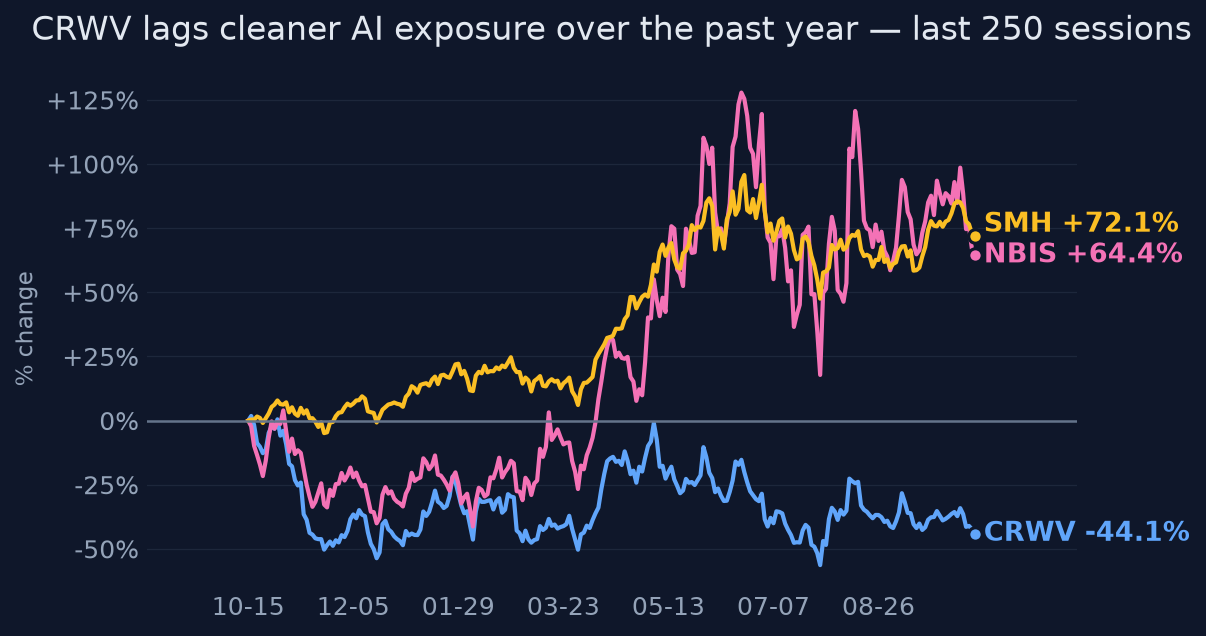
- Nebius raised GPU rates 17-21% Oct 1 and is +60% over 1y vs CRWV -44% despite 0.86 correlation — market pays for pricing power/clean balance sheets, discounts leverage [computed/T3]
- JPMorgan upgraded to Overweight, $125 target (early Oct 2026) citing demand and premium short-contract pricing [T3]
Catalysts and risks
Catalysts
- Q3 2026 earnings (revenue guided $3.45-3.60B; adj op income $200-260M) — likely November 2026
- Pricing/terms achieved on the $3B convertible and execution of the ATM program
- CoreWeave unsecured bond yield trajectory (15% → compression or wider)
- Any OpenAI/Microsoft/Meta contract announcements, delays, or renegotiations
- Year-end milestones: >1.85 GW active power, $18.5-19.5B run-rate revenue
Risks
- Refinancing risk at double-digit yields; interest expense approaching ~$1B/quarter
- Continued equity dilution via ATM and converts
- Customer concentration and OpenAI counterparty credit/circular-financing exposure
- Financing maturity mismatch (~5-yr debt vs ~3-yr contracts) and GPU residual-value risk
- AI-capex cycle cooling or contract delays stranding newly built capacity
- Beta ~4.5 and 93% annualized vol — position sizing risk dominates thesis risk
What to watch
- CRWV unsecured bond yields and CDS — the true pricing mechanism for the equity
- Dilution pace: quarterly share count vs the announced ATM/convert
- Backlog conversion rate: revenue vs. the >50% of backlog already in delivery
- Q3 interest expense vs the $860-940M guide and FCF trajectory
- Nebius/peer GPU pricing — the sector's demand thermometer
- Any SEC filings on the convert terms (coupon, conversion price, capped call)
Market snapshot when the call was made 2026-10-13
Price
| Return 1w | -15.2% |
| Return 1m | -6.2% |
| Return 3m | +0.9% |
| Return 6m | -33.6% |
| Return 1y | -43.8% |
| From 52-week high | -45.1% |
| Realized vol, 20d | 53.5% |
| SPY 3m / 1y | +3.1% / +19.1% |
| QQQ 3m / 1y | +3.6% / +26.1% |
Technicals
CRWV technicals as of 2026-10-13: last close $77.81; 20d SMA 85.35 (bearish); 50d SMA 88.44; 12d EMA 84.16; 26d EMA 85.64; RSI 14 36.8 (balanced); 20d vol 51.8%; volume x1.1 vs 20d avg
Verifier notes PASS
Weakly sourced
- The ~5-year debt vs ~3-year contract maturity mismatch (stated as fact in the thesis and bear case) rests only on T4 reporting that the evidence digest itself flagged as 'weakly sourced — verify against filings.' The opinion repeats it without any caveat. Not verdict-changing since the core thesis (leverage, dilution, credit-spread repricing) is independently supported, but it should carry a hedge or verification note.
- The $3B convertible and 35M-share ATM program terms are T4-only; the opinion does flag this in key_evidence, which is adequate, but the bear case leans on 'serial equity issuance... into a falling price' without reiterating that offering terms are unverified against SEC filings.
Corrections applied
- Add a '(reported, unverified against filings)' qualifier to the 5-year-debt vs 3-year-contract mismatch claim where it appears in the thesis and bear case.
Sources (29 · T1 = primary filings)
- T4https://rollingout.com/2026/10/13/coreweave-stock-gap-down-backlog-debt/
- T4https://247wallst.com/investing/2026/10/13/coreweave-imploded-20-over-6-months-this-analyst-predicts-it-will-t…
- T4https://finance.yahoo.com/markets/stocks/articles/coreweaves-backlog-huge-heres-risk-193500716.html
- T4https://www.marketbeat.com/stocks/NASDAQ/CRWV/news/
- T4https://finance.yahoo.com/technology/ai/articles/coreweave-crwv-104b-backlog-balance-123602262.html
- T4https://www.marketbeat.com/instant-alerts/price-coreweave-nasdaq-crwv-shares-gap-down-whats-next-2026-10-13/
- T4https://finance.yahoo.com/markets/stocks/articles/coreweave-debt-substantiated-clear-demand-164510001.html
- T4https://stockanalysis.com/stocks/crwv/transcripts/662772-q2-2026/
- T4https://247wallst.com/investing/2026/10/14/coreweave-falls-10-as-bond-yield-touches-15-and-elon-musk-says-yike…
- T4https://www.timothysykes.com/news/coreweave-inc-crwv-news-2026_10_14-2/
- T4https://stockanalysis.com/quote/tsx/CRWV/
- T4https://ground.news/article/coreweave-launches-3-billion-convertible-debt-sale_6c0bda
- T4https://www.tradingview.com/news/benzinga:b9255c233094b:0-coreweave-stock-dips-what-s-going-on/
- T4https://ground.news/article/coreweave-nasdaq-crwv-shares-gap-up-heres-why_1c534c
- T4https://stockanalysis.com/stocks/crwv/
- T4https://ground.news/article/nebius-is-still-down-21-in-a-month-did-today-just-mark-the-bottom_c2ea5d
- T4https://finance.yahoo.com/markets/stocks/articles/iren-climbs-6-nebius-jumps-131142481.html
- T2https://www.reuters.com/business/media-telecom/nvidia-invest-15-billion-sb-energy-under-openai-data-center-dea…
- T4https://markets.businessinsider.com/news/stocks/nebius-initiated-with-a-buy-at-rosenblatt-1036607217
- T4https://www.zacks.com/stock/news/2809691/coreweave-vs-nebius-which-ai-infrastructure-stock-is-the-better-buy
- T4https://markets.businessinsider.com/news/stocks/why-coreweave-nebius-and-iren-stocks-are-bouncing-back-today-a…
- T4https://finance.yahoo.com/markets/stocks/articles/nbis-stock-rallies-neocloud-operator-031055938.html
- T4https://markets.businessinsider.com/news/stocks/coreweave-and-nebius-stocks-fall-while-iren-rises-in-premarket…
- T4https://stockstotrade.com/news/coreweave-inc-crwv-news-2026_10_14/
- T4https://stockstotrade.com/news/coreweave-inc-crwv-news-2026_10_14-2/
- T4https://www.useluminix.com/reports/industry-analysis/who-is-financing-the-ai-buildout/source/4
- T4https://stockstotrade.com/news/coreweave-inc-crwv-news-2026_10_14-3/
- T3https://www.cnbc.com/2026/10/04/top-analysts-are-upbeat-about-the-prospects-for-these-3-stocks.html
- T4https://investors.coreweave.com/news/default.aspx
Want a fresh look at CRWV, or another name?
Queue a new deep-research run. Published to the feed when done.
Automated research opinion, published as-is on Oct 14, 2026. Not personalised advice. Figures use end-of-day closes.