Supported, but the easy move is done.
Thesis
Bull case
Agentforce ARR has crossed $1.5B with usage metrics accelerating (+97% q/q Work Units), cRPO +14% leads revenue, management explicitly guides to organic 2H reacceleration and has now raised FY27 guidance, the sector tailwind is real (sector 2026 EPS-growth expectations revised up from 13.8% to 20.6% since end of March, ~+49%), BofA's PT move to $285 and consensus ~$285 imply ~18% upside, and margins (34% non-GAAP op-margin target) plus buybacks underpin valuation. If Q3 confirms organic acceleration, estimates re-rate and the upper end of the $475 target range opens.
Bear case
Headline double-digit growth is manufactured by acquisitions while organic growth sits near single digits; the EPS guide jump leaned on investment gains; Agentforce ARR may partially cannibalize seat-based revenue rather than be incremental; at 16.5x forward the stock has already re-rated — after a 48.7% run, vol compression sets up a 'sell the news' reaction to a strong-but-not-blowout Q3. Wells Fargo-type skeptics see structural AI seat compression; the $165 low target implies ~30% downside.
What would change our mind
- Q3 FY27 organic constant-currency growth ex-Informatica shows no acceleration vs Q2 while guidance merely relies on acquired revenue
- cRPO growth decelerates below ~12% y/y
- Agentforce ARR growth stalls or the company signals pricing/monetization problems with 'headless'/consumption models
- Evidence emerges of material seat-count compression among large customer cohorts
- Stock breaks down through the 50d SMA (~$232) on an earnings reaction, invalidating the consolidation
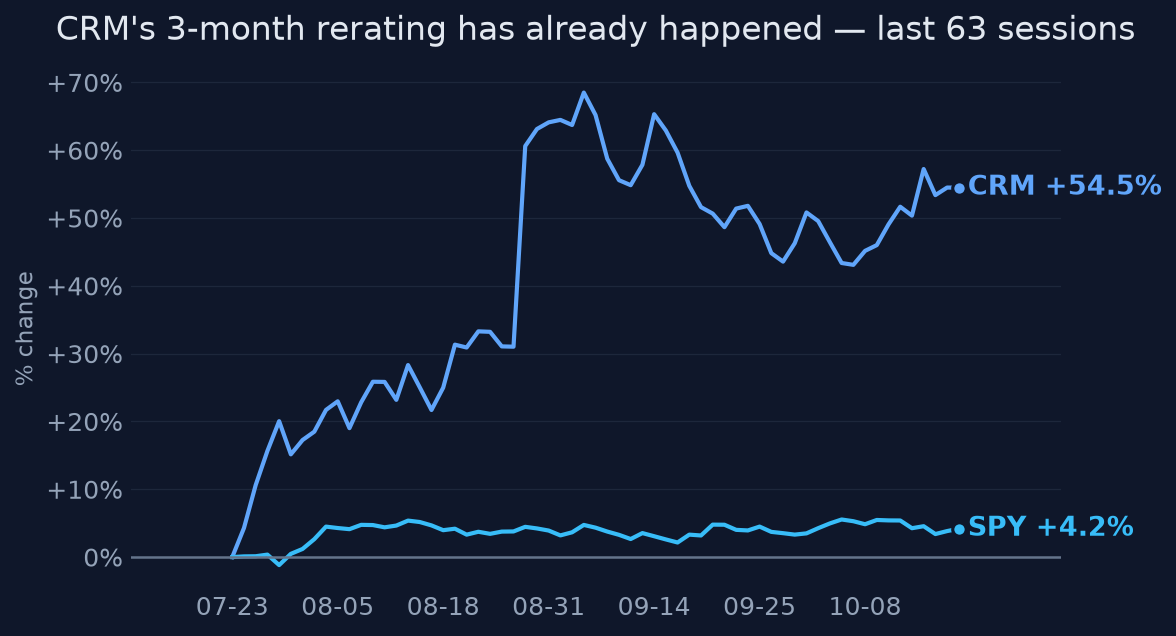
Since publication vs SPY · closed horizons are frozen
The full research everything the view rests on
Direct answer to the question asked
Where the edge would come from
What the price assumes
At ~16-16.5x forward EPS and ~15-18% consensus-implied upside ($278-286 vs $242), the market prices in a successful, but not spectacular, AI monetization ramp: continued double-digit reported growth, organic reacceleration materializing in 2H FY27, and no seat-compression damage to the core model. The market has already paid for the narrative shift from 'AI disrupts Salesforce' to 'Salesforce leads agentic AI.'
Why the market may be wrong
Both directions are live. Bearish side: underlying organic growth is plausibly ~high-single-digits once Informatica/Contentful/Fin are stripped out, and the 'reaccelerating' headline is manufactured by M&A plus investment-gain-flattered EPS. Bullish side: if cRPO +14% and 3.2B Agentic Work Units (+97% q/q) convert to organic revenue in H2, organic estimates are too low and the re-rating continues toward the top half of the $165-475 target range. Consensus modest revisions (6-8 raisers in 30 days) suggest estimates haven't yet caught up to the ARR trajectory.
The one thing to watch
The single variable that will settle the bull/bear debate is not Agentforce ARR — it's organic constant-currency revenue growth ex-acquisitions in the Q3 print (guide implies ~11-12% reported but only ~7-8% ex-Informatica). The scan is signaling the end of the beta leg; from here the stock trades on whether organic growth accelerates toward management's promised 2H reacceleration or reveals that double-digit growth is now a function of buying revenue.
Key evidence (10)
- CRM +48.7% 3m vs SPY +2.9%, but -0.3% over 1y and -8.9% below 52w high; max drawdown -43.6% within the year [quant, 2026-10-21]
- 20d realized vol 31.5% at the 10th percentile of its own year; 1m z-score +0.15 — compression after the impulse [quant]
- Q2 FY27 (Aug 26, 2026): revenue $11.35B +11% y/y, beat; cRPO +14% y/y; FY27 revenue guide raised to $46.1-46.4B [T1 IR]
- Guidance raise decomposition: only ~$100M of the ~$300M cc raise was organic; ~$200M from pending Contentful/Fin deals; Q2 already included ~$456M of acquired Informatica revenue and Q3 guided growth includes ~4pts from Informatica [T1/T3]
- Q2 non-GAAP EPS $5.90 (+103% y/y) and the FY27 EPS guide jump from ~$14.09 to ~$16.69 included investment gains — not purely operational [T3 CNBC]
- Agentforce ARR >$1.5B (from ~$800M at FY26-end); Agentforce+Data 360 ~$3.9B combined, +210% y/y; 3.2B Agentic Work Units, +97% q/q [T1]
- Forward P/E ~16-16.5x, upper end of the recent October range [T4]
- Consensus targets $278-286 (+15-18%) but dispersion $165-475; one 'strong sell' rating; BofA double-upgrade U->Buy, PT $160->$285 on Oct 12 [T4, weakly sourced — flag]
- Sector context: software recovery since late June is broader than CRM; Reuters cited sector 2026 EPS-growth expectations revised from 13.8% to 20.6% (~+49%) since end of March; ServiceNow +24.5% subscription growth is the peer proof point [T2/T1]
- Operating margin expanded from 2.1% (FY21) to 20.1% (FY25) — the structural margin story is real SEC-filed fact [T1 XBRL]
Catalysts and risks
Catalysts
- Q3 FY27 earnings, expected late Nov / early Dec 2026 — the test of management's organic 2H reacceleration claim
- Contentful and Fin acquisition closes and their reported contribution to guidance
- Post-Dreamforce commercialization of Agentforce Coworker and NVIDIA Koa reasoning model
- Further analyst revisions; net FY28 EPS revision direction
- Software-sector earnings season tone (ServiceNow, Microsoft) as read-through
Risks
- Estimated Q3 earnings within the 3-6m horizon raises binary event risk into a compressed-vol setup
- Organic growth miss would unmask M&A dependence and likely compress the multiple
- Agentforce seat-cannibalization evidence emerging in disclosed metrics
- Acquisition integration risk (Informatica, Contentful, Fin)
- If the AI-disruption fear narrative returns sector-wide, CRM's 60d correlation to NOW is high (0.76) — downside could be shared
What to watch
- Q3 print: organic cc growth ex-acquisitions vs the ~9-10% baseline
- cRPO y/y growth — the forward indicator that led this rally
- Agentforce ARR trajectory ($1.5B -> $2B+ pace) and Agentic Work Units growth
- FY28 consensus EPS revisions (currently $16.02, suspiciously below FY27 $16.76 — watch for normalization)
- 20d realized vol expansion from the 10th percentile — signal of the next directional move
- CRM/NOW and CRM/IGV relative strength holding after earnings
Market snapshot when the call was made 2026-10-20
Price
| Return 1w | +1.9% |
| Return 1m | +2.5% |
| Return 3m | +48.7% |
| Return 6m | +29.6% |
| Return 1y | -0.3% |
| From 52-week high | -8.9% |
| Realized vol, 20d | 31.5% |
| SPY 3m / 1y | +2.9% / +15.8% |
| QQQ 3m / 1y | +1.7% / +18.8% |
Technicals
CRM technicals as of 2026-10-20: last close $242.43; 20d SMA 233.99 (neutral); 50d SMA 232.01; 12d EMA 237.74; 26d EMA 235.16; RSI 14 62.1 (balanced); 20d vol 31.0%; volume x1.0 vs 20d avg
Verifier notes REVISE · opinion revised once
Unsupported claims
- Bull case: 'the sector tailwind is real (eps-growth expectations nearly doubled since March)' — the evidence shows sector 2026 EPS-growth expectations revised from 13.8% to 20.6%, which is a ~49% increase, not 'nearly doubled.' This overstates the magnitude of the sector tailwind cited as a bull pillar.
Internal inconsistencies
- Minor: risks section cites '60d idiosyncratic correlation to NOW is high (0.76)' — 0.76 is the plain 60d correlation; the idiosyncratic share vs NOW is 42%. The substantive point (shared downside) still holds, but the label is technically wrong. Not material on its own.
- Minor: thesis states 'much of the raise is M&A (Informatica ~$456M in Q2, ~$200M pending Contentful/Fin)' — the $456M Informatica figure is Q2 revenue contribution, not part of the ~$300M guidance-raise decomposition ($100M organic + $200M Contentful/Fin). The conflation is mildly misleading but the broader growth-quality claim is supported.
Corrections applied
- In bull_case, replace 'eps-growth expectations nearly doubled since March' with 'sector 2026 EPS-growth expectations revised up from 13.8% to 20.6% since end of March (~+49%)'.
- In risks, change '60d idiosyncratic correlation to NOW is high (0.76)' to '60d correlation to NOW is high (0.76)'.
- Optionally, in thesis, separate the two facts: 'the ~$300M raise was only ~$100M organic (~$200M from pending Contentful/Fin), and Q2 already included ~$456M of acquired Informatica revenue.'
Sources (31 · T1 = primary filings)
- T1https://investor.salesforce.com/news/news/details/2026/Salesforce-Delivers-Record-Fourth-Quarter-Fiscal-2026-R…
- T1https://investor.salesforce.com/news/news-details/2026/Salesforce-Delivers-Record-First-Quarter-Fiscal-2027-Re…
- T1https://investor.salesforce.com/news/news-details/2026/Salesforce-Provides-Fiscal-2027-Disaggregated-Revenue-R…
- T1https://investor.salesforce.com/news/news-details/2026/Salesforce-Delivers-Record-Second-Quarter-Fiscal-2027-R…
- T4https://www.theglobeandmail.com/investing/markets/stocks/CRM/pressreleases/4322594/salesforce-q2-earnings-call…
- T4https://finance.yahoo.com/markets/stocks/articles/salesforce-inc-crm-q2-2027-050132389.html?fr=sycsrp_catchall
- T4https://www.theglobeandmail.com/investing/markets/stocks/CRM-N/pressreleases/4322596/salesforce-q2-earnings-ca…
- T4https://www.zacks.com/commentary/2926523/salesforce-heads-into-earnings-with-everything-to-prove---and-everyth…
- T2https://www.reuters.com/company/salesforce-inc/
- T2https://www.reuters.com/business/us-software-stocks-scale-fresh-2026-highs-ai-disruption-worries-fade-2026-10-…
- T1https://investor.servicenow.com/news/news-details/2026/ServiceNow-Reports-Second-Quarter-2026-Financial-Result…
- T2https://www.reuters.com/commentary/breakingviews/softwares-ai-trade-moves-fear-opportunity-2026-09-01/
- T2https://www.reuters.com/business/us-software-stocks-attempt-rebound-investors-reassess-ai-risks-2026-05-19/
- T1https://investor.servicenow.com/news/news-details/2026/ServiceNow-Reports-First-Quarter-2026-Financial-Results…
- T4https://www.calcalistech.com/ctechnews/article/lbovgj3wu
- T4https://www.investors.com/news/technology/salesforce-climbs-bank-of-america-double-upgrade-buy-improved-ai-tre…
- T4https://www.marketbeat.com/instant-alerts/analyst-salesforce-nyse-crm-given-overweight-rating-at-cantor-fitzge…
- T4https://www.theglobeandmail.com/investing/markets/stocks/CRM/pressreleases/4223323/salesforce-q2-earnings-beat…
- T4https://fortune.com/company/salesforce-com/earnings/q2-2027/
- T4https://www.zacks.com/stock/research/CRM/price-target-stock-forecast
- T3https://www.morningstar.com/stocks/xwbo/crm/earnings
- T4https://247wallst.com/cards/salesforce-q2-2027-earnings-crm-01m0zv1m3t5bsp563b34aazca6
- T4https://news.futunn.com/en/notice/308005462/salesforce-10-q-q2-2027-earnings-report
- T4https://finance.yahoo.com/markets/stocks/articles/salesforce-scores-double-upgrade-bofa-205033368.html
- T4https://www.salesforce.com/blog/dreamforce-2026-announcements/?bc=OTH
- T4https://ground.news/article/salesforce-deepens-its-integrations-with-aws-and-google-cloud-to-support-ai-agents
- T4https://www.marketbeat.com/instant-alerts/price-salesforce-nyse-crm-shares-up-2-on-analyst-upgrade-2026-10-12/
- T4https://www.marketbeat.com/instant-alerts/price-salesforce-nyse-crm-shares-gap-up-after-analyst-upgrade-2026-1…
- T4https://markets.businessinsider.com/news/stocks/salesforce-upgraded-to-buy-from-underperform-at-bofa-103661738…
- T4https://news.ssbcrack.com/salesforce-stock-rises-after-bank-of-america-double-upgrade-on-ai-monetization-trend…
- T4https://finance.yahoo.com/technology/ai/articles/salesforce-gets-rare-bofa-double-042511253.html
Earlier and later calls on CRM
- Sep 9, 2026Qualified yes — scale in, don't chase.Lean bullish
Want a fresh look at CRM, or another name?
Queue a new deep-research run. Published to the feed when done.
Automated research opinion, published as-is on Oct 21, 2026. Not personalised advice. Figures use end-of-day closes.