Qualified yes — scale in, don't chase.
Thesis
Bull case
The core bear objection from early 2026 — that AI destroys Salesforce's model — is being answered with hard numbers: bookings (cRPO +14% cc) lead revenue, Agentforce is past $1.5B ARR, margins are still expanding, and estimate revisions are moving up. At ~14.6x forward non-GAAP EPS the market is paying a historically depressed multiple for a company guiding to double-digit growth with a raised FY30 target; if H2 organic reacceleration prints in December, both EPS and the multiple have room to rise toward the $300+ targets already set by four post-earnings firms.
Bear case
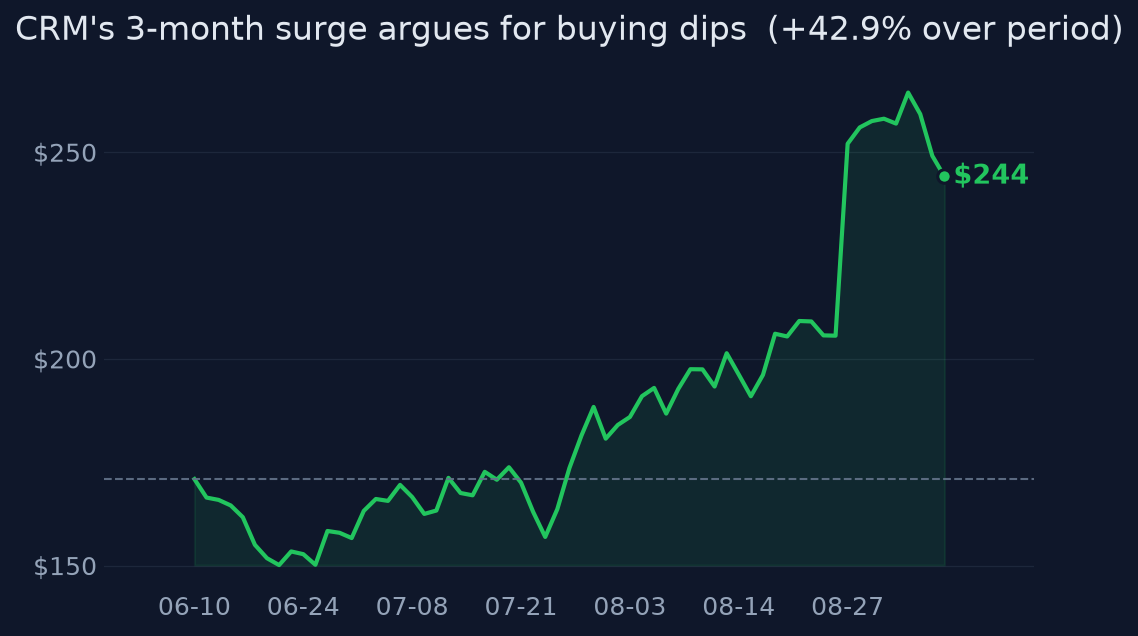
The rally has front-run the proof: the stock is +39% in 3 months, overbought, and ~8% above its 20-day SMA, while the underlying organic business raised guidance by only $100M — Informatica and other M&A did the heavy lifting. Agentforce ARR may be inflated by consumption-credit 'refills' rather than durable new demand, licensed revenue remains volatile, and the structural AI-vs-seats question is unresolved — the industry is in pricing-transition limbo. If December shows organic growth stuck at ~9-10% while reported growth flatters via M&A, the stock gives back the repair rally toward $200-210, and Morgan Stanley's $185 target frames the tail.
What would change our mind
- Q3 FY27 (Dec 1) shows organic constant-currency growth below ~9% or management walks back the H2 reacceleration claim
- cRPO growth decelerates meaningfully below +14% cc, breaking the bookings-leads-revenue argument
- Agentforce/AI ARR growth collapses or disclosures reveal heavy credit-refill dilution
- FY27 EPS guidance is cut or held while the stock stays >15% above pre-earnings levels — that would signal multiple expansion without fundamental support
Since publication vs SPY · closed horizons are frozen
The full research everything the view rests on
Direct answer to the question asked
Where the edge would come from
What the price assumes
At ~14.6x forward non-GAAP earnings and still -3.2% over 1Y vs SPY +17.5%, the market has acknowledged the Q2 inflection but refuses to fully re-rate the stock — it is pricing roughly 10-11% reported growth with lingering skepticism that (a) Agentforce consumption-credit revenue is durable, (b) growth is organic rather than Informatica-driven, and (c) seat-based pricing survives the AI transition. Consensus PT ~$275 implies only ~13% upside, and Morgan Stanley's July 2026 downgrade to Equal Weight/$185 shows the Street is genuinely split.
Why the market may be wrong
The consensus may be anchoring on the early-2026 'AI kills seats' derating while the forward indicator that best predicts SaaS revenue — cRPO — accelerated to +14% cc, the bookings acceleration bulls had been waiting for (note: the evidence contains no historical cRPO series, so how this ranks versus prior years is unverified). Conversely, bulls may be wrong in the other direction: the headline +10-11% growth and raised guidance mask only $100M of organic raise versus $200M from acquisitions, so reported numbers overstate underlying momentum. The market is pricing a blended view that could be wrong on both sides depending on what organic growth prints in December.
The one thing to watch
Stop watching Agentforce ARR headlines and start watching the organic/inorganic split: only $100M of the $300M cc FY27 guidance raise was organic, so the entire bull case now reduces to one falsifiable claim — management's promise of H2 FY27 organic reacceleration, testable at the Dec 1 print against Q3 consensus revenue of ~$11.55B. At 14.6x forward earnings the multiple already embeds partial disruption, which means the December organic-growth number, not AI narrative, is the variable that moves the stock.
Key evidence (9)
- Q2 FY27 (Aug 26, 2026): revenue $10.25B, +10% YoY; non-GAAP op margin 34.3%, +60bps [T1 Salesforce IR press release]
- Agentforce ARR >$1.5B (+240% YoY); AI+Data ARR ~$3.9B (+210%); cRPO $33.5B, +14% cc [T1 press release, T4 transcript summaries]
- FY27 guidance raised to $46.1-46.4B revenue and $16.67-16.71 non-GAAP EPS; the $300M cc raise split $100M organic / $200M acquisitions; Informatica contributed $456M of Q2 revenue [T1/T4 call coverage]
- Q3 FY27 guide: revenue $11.42-11.50B (11-12% growth), non-GAAP EPS $3.42-3.44; next report Dec 1, 2026 with consensus revenue ~$11.55B [T3/T4]
- Price action: +39.2% 3m, +23.6% 1m, -5.4% 1w; RSI 71 (overbought); 20d realized vol ~81%; -8.3% below 52w high after -43.6% max drawdown in past year [computed price history]
- FY27 EPS consensus revised up from ~$14.03 to ~$16.2 over 3 months; median analyst PT ~$275 (range $160-400); post-earnings raises to $300-315 (Cantor, Truist, TD Cowen, Citizens) vs Morgan Stanley downgrade to EW/$185 in July 2026 [T3/T4 aggregators]
- Margin trajectory from SEC XBRL: GAAP operating margin 2.1% (FY21) → 20.1% (FY25); FY25 revenue $41.5B, GAAP EPS $7.80 [T1 SEC companyfacts]
- FY30 revenue target raised to $63B (~11% CAGR FY26-30), embedding sustained reacceleration [T1 filing summaries]
- Caveat: the widely-cited '22.8x forward P/E' figure is stale (implies ~$367/share); current forward non-GAAP P/E at $244.16 on guidance is ~14.6x
Catalysts and risks
Catalysts
- Q3 FY27 earnings Dec 1, 2026 (AMC) — the organic reacceleration test; consensus revenue ~$11.55B, EPS ~$3.44
- Potential Dreamforce product/pricing announcements — no confirmed Dreamforce 2026 date appears in the evidence; timing unverified
- Informatica integration milestones and any updated synergy/contribution disclosures
- Further analyst target revisions as FY28 estimates (currently ~$50.8B revenue / ~$16.2 EPS — note: FY28 EPS consensus near FY27 levels is a data inconsistency worth monitoring) get rebuilt
- Sector-level AI-pricing news from MSFT/NOW that resets the software multiple
Risks
- Organic growth fails to reaccelerate in H2 FY27, exposing the M&A-dependent raise
- Agentforce consumption-credit revenue proves non-durable or gets repriced lower
- Renewed software-wide AI derating compresses the multiple regardless of execution
- Entry-point risk: RSI 71, 81% annualized 20d vol, and profit-taking already underway (-5.4% this week)
- FY30 $63B target sets a high bar that invites disappointment if growth stays ~10%
- Key analyst-target and consensus data rest on T3/T4 aggregators, some with internal inconsistencies
What to watch
- Organic vs inorganic split of Q3 revenue growth (Informatica contribution disclosure)
- cRPO growth rate in cc at the December print
- Agentforce ARR trajectory and any pricing-model disclosure (seat vs consumption mix)
- FY28 consensus EPS revisions — currently suspiciously flat vs FY27; direction of revisions is the tell
- Whether the stock holds the ~$225-230 zone (20-day SMA/post-earnings breakout) on the current pullback
Market snapshot when the call was made 2026-09-09
Price
| Return 1w | -5.4% |
| Return 1m | +23.6% |
| Return 3m | +39.2% |
| Return 6m | +25.3% |
| Return 1y | -3.2% |
| From 52-week high | -8.3% |
| Realized vol, 20d | 81.4% |
| SPY 3m / 1y | +3.4% / +17.5% |
| QQQ 3m / 1y | +1.2% / +23.7% |
Technicals
CRM technicals as of 2026-09-09: last close $244.16; 20d SMA 225.83 (bullish); 50d SMA 195.19; 12d EMA 242.42; 26d EMA 223.99; RSI 14 71.3 (overbought); 20d vol 87.6%; volume x0.7 vs 20d avg
Next earnings: 2026-12-01 AMC
Verifier notes REVISE · opinion revised once
Unsupported claims
- Claim in why_market_may_be_wrong: cRPO accelerating to +14% cc is 'the strongest bookings signal in years.' The evidence bundle contains no historical cRPO series or any source characterizing this print as a multi-year high — the digest only calls it 'the bookings acceleration bulls were waiting for.' This is a fabricated comparative superlative on the central bull metric and overstates what the evidence shows.
- Catalyst listing 'Dreamforce 2026 (typically Sept-Oct)' has no support anywhere in the evidence bundle; no Dreamforce date or timing was surfaced by any tool call. It is hedged with 'typically,' but it presents an unverified event window as a catalyst.
Corrections applied
- Soften the cRPO superlative to what the evidence supports, e.g.: 'cRPO accelerated to +14% cc — the bookings acceleration bulls had been waiting for' — or delete the 'strongest in years' characterization unless a historical cRPO series is sourced.
- Either remove the Dreamforce catalyst or rephrase to note that no confirmed Dreamforce 2026 date appears in the evidence (e.g., 'potential Dreamforce product/pricing announcements — timing not confirmed in evidence').
Sources (24 · T1 = primary filings)
- T1https://investor.salesforce.com/news/news-details/2026/Salesforce-Delivers-Record-Second-Quarter-Fiscal-2027-R…
- T4https://www.fool.com/earnings/call-transcripts/2026/08/31/salesforce-crm-q2-2027-earnings-call-transcript/
- T4https://quartr.com/events/salesforce-inc-crm-q2-2027_3YM54irs
- T1https://investor.salesforce.com/news/news-details/2026/Salesforce-Delivers-Record-First-Quarter-Fiscal-2027-Re…
- T4https://seekingalpha.com/article/4940570-salesforce-inc-crm-q2-2027-earnings-call-transcript
- T4https://finance.yahoo.com/markets/stocks/articles/salesforce-inc-crm-q2-2027-050132389.html
- T4https://www.investing.com/news/transcripts/earnings-call-transcript-salesforce-tops-q2-2026-profit-forecasts-s…
- T4https://qz.com/salesforce-earnings-revenue-forecast-ai-agentforce-082626
- T4https://www.theregister.com/software/2025/12/12/salesforce-opts-for-seat-based-ai-licensing/1997517
- T4https://markets.financialcontent.com/stocks/article/marketminute-2026-2-6-the-great-software-de-rating-ai-fear…
- T4https://www.investing.com/news/transcripts/salesforce-at-deutsche-bank-2026-technology-conference-ai-push-lift…
- T4https://markets.financialcontent.com/wral/article/marketminute-2026-2-6-the-great-software-de-rating-ai-fears-…
- T4https://finance.yahoo.com/news/salesforce-says-per-user-pricing-172500699.html
- T4https://markets.financialcontent.com/postgazette/article/marketminute-2026-2-6-the-great-software-de-rating-ai…
- T4https://markets.financialcontent.com/clarkebroadcasting.mycentraloregon/article/marketminute-2026-2-6-the-grea…
- T4https://www.dench.com/blog/salesforce-einstein-review
- T4https://www.benzinga.com/analyst-stock-ratings/price-target/25/09/47507173/salesforce-analysts-cut-their-forec…
- T4https://www.investing.com/news/transcripts/earnings-call-transcript-salesforce-q4-2026-earnings-beat-expectati…
- T4https://marketchameleon.com/articles/b/2026/2/26/salesforce-targets-63b-fy30-revenue-agentic-ai-subscription-g…
- T4https://talkmarkets.com/article/salesforce-stock-drops-25-but-its-ai-numbers-tell-a-different-story-1772992213
- T4https://www.investing.com/news/analyst-ratings/cantor-fitzgerald-raises-salesforce-stock-price-target-on-ai-mo…
- T4https://finance.yahoo.com/news/salesforce-thinks-bigger-ai-133617818.html
- T4https://www.quantumrun.com/consulting/salesforce-statistics/
- T4https://finance.yahoo.com/markets/stocks/articles/morgan-stanley-slashes-salesforce-price-101500010.html
Earlier and later calls on CRM
- Oct 21, 2026Supported, but the easy move is done.Lean bullish
Want a fresh look at CRM, or another name?
Queue a new deep-research run. Published to the feed when done.
Automated research opinion, published as-is on Sep 9, 2026. Not personalised advice. Figures use end-of-day closes.