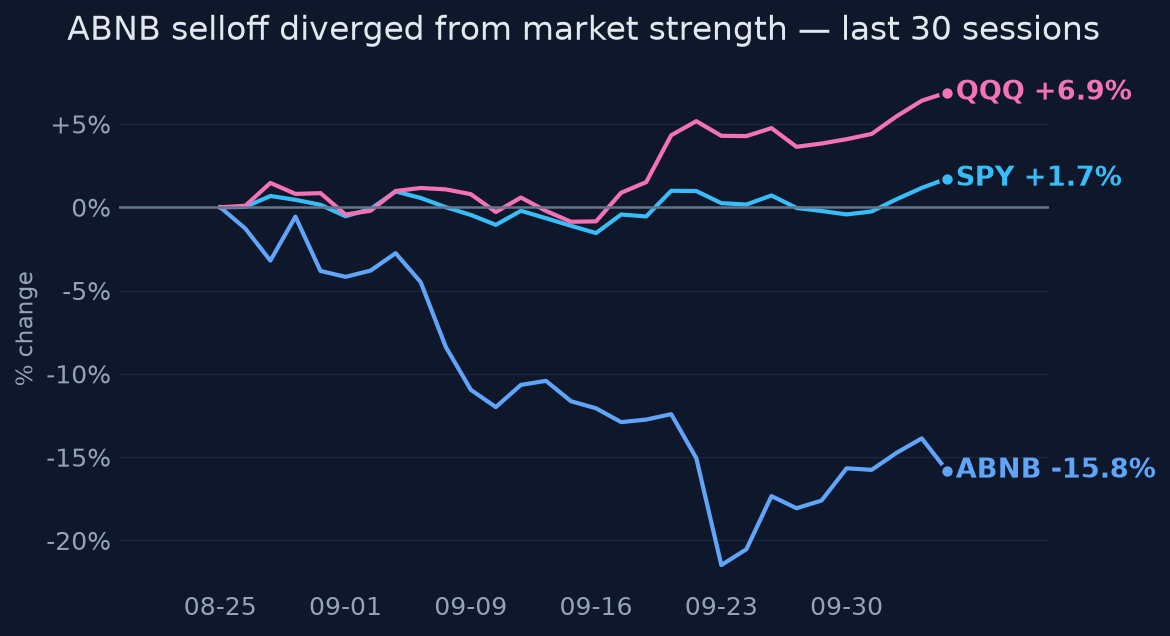
Pullback looks sentiment-driven, not fundamental.
Thesis
Bull case
The pullback is a technical/sentiment event on a fundamentally accelerating business. Q3 prints at or above the guided 15–17%, FY26 margin guidance is met or raised again, and any quantified Services/hotels disclosure converts narrative into a new revenue layer. With ~$4.5–5B/yr of buybacks (≈5% of market cap) and the stock already 10% below the Street target, the path back to the 52w high (~$190) is ~18% with the buyback as a floor. Share gains vs Booking's alt-accommodations (+4% vs Airbnb nights +10%) support durability.
Bear case
The Street's Hold-heavy posture is right: ~30x forward — near the high end of its recent range — for a company whose take rate is reportedly guided flat means the acceleration is low-quality volume growth, and Services/hotels are reinvestment sinks that will cap the 35%+ margin trajectory and eventually compete with buybacks. Insiders selling into the re-rating (with 10b5-1 status unconfirmed), 20d realized vol at the 80th percentile, and a price still below the falling 20d/50d SMAs suggest distribution, not a finished correction. If Q3 merely meets guidance, a Hold-heavy Street has no reason to lift targets; if inbound-US travel weakness or a consumer slowdown hits forward bookings, 30x forward compresses fast.
What would change our mind
- Q3 2026 revenue below the $4.69B guidance low end, or FY26 margin guidance cut below 35.5% — proves the September selloff was information, not noise
- Confirmed disclosure that Services/hotels are generating material losses or that take rate is declining rather than flat
- Buyback pace falling well below the ~$1B/quarter run-rate without a cash-flow explanation
- Major-bank downgrades with estimate cuts taking FY27 EPS below ~$6.00
- Form 4 confirmations that September sales were discretionary and clustered — would upgrade insider selling from ambiguous to a genuine negative signal
- A major-wire (Reuters/Bloomberg/WSJ) report of demand weakness or regulatory shock (e.g., NYC/Europe STR rules expanding) that the T4 aggregation missed
Since publication vs SPY · closed horizons are frozen
The full research everything the view rests on
Direct answer to the question asked
Where the edge would come from
What the price assumes
The Street never fully endorsed the 2026 re-rating: 14 Buy / 25 Hold / 6 Sell with an average target of ~$176.76. At ~30x FY26 EPS (~$5.30) and ~26x FY27 (~$6.25) — near the high end of its recent forward range — the price assumes mid-teens growth persists and margins hold ≥35%, but the Hold-dominated distribution and reportedly flat-take-rate guidance suggest consensus is skeptical that Services/hotels add monetization rather than just reinvestment drag.
Why the market may be wrong
Two ways. Bullish: consensus may be anchoring on 2025's ~10% growth and treating the Q2 acceleration as noise — but nights booked accelerated sequentially, Experiences supply grew ~80% y/y, and Booking's alt-accommodation room nights grew only ~4%, implying Airbnb is gaining share, not riding a category tailwind. Bearish: the acceleration could be volume/ADR-driven with flat take rate, meaning the new initiatives are not yet monetizing — if reinvestment in Services/hotels caps margin expansion, the 35%+ EBITDA trajectory and the buyback pace both come into question. The unverified nature of the September insider sales cuts both ways: if they prove discretionary rather than scheduled, the 'no fundamental catalyst' read weakens.
The one thing to watch
The variable to watch is not revenue growth — it's the implied take rate. Management reportedly guided FY26 take rate to flat (T4 research note, not verified against the primary transcript); if accurate, all of the 2026 acceleration is volume and ADR, and the entire Services/hotels thesis is currently narrative with zero disclosed revenue contribution. If Q3 discloses even modest Services/hotels monetization or take-rate inflection, the stock re-rates on a new revenue layer; if take rate stays flat with rising reinvestment spend, the growth is lower-quality than the 17% headline suggests. Verify the flat-take-rate guidance against the Q2 transcript before treating this as settled.
Key evidence (10)
- Q2 2026 (reported 2026-08-06): revenue $3.6B +17% y/y, GBV $27.2B +16%, nights/seats +10% accelerating vs Q1, EPS $1.37 vs $1.26 est., adj EBITDA margin 35% (company release/news.airbnb.com)
- Guidance: Q3 2026 revenue $4.69–4.77B (+15–17%); FY26 adj EBITDA margin raised to ≥35.5% from 35% (Q2 release)
- Price action: -11.8% 1M (z-score -1.37) while SPY +1.2% and QQQ +5.7%; 20d vol at 80th percentile; -15.8% below 52w high (market data, 2026-10-07)
- No confirmed fundamental catalyst for the selloff surfaced; documented items are insider Form 4 sales (CSO Blecharczyk 13,615 sh 9/28; CAO Bernstein 1,489 sh 9/15) — whether these were pre-scheduled 10b5-1 plans is unverified, and the 'no catalyst' conclusion rests on T4 aggregation, absence of evidence not definitive
- Consensus (41 analysts, updated 2026-09-29): FY26 rev $14.18B / EPS $5.30; FY27 $15.83B / $6.25; revisions mildly positive; ratings 14 Buy / 25 Hold / 6 Sell, avg target ~$176.76
- Valuation: forward P/E ~30.4x as of 2026-10-07, with the evidence bundle's valuation search explicitly concluding the stock is trading near the high end of its current forward range rather than at a discount
- Cash return: TTM FCF ~$4.8B (37% margin); H1 2026 buybacks $2.14B (16M shares); $3.4B authorization remaining; S&P [T3] projects $4.5–5.0B/yr repurchases 2026–27; diluted shares 634M, -2.8% y/y, ~10% below Q3 2022
- Bear datapoint: August 2026 research note cites management guiding FY26 implied take rate to flat, not rising [T4 — not verified against primary transcript]
- Macro: Marriott and Hilton raised 2026 US RevPAR outlooks to 3–3.5% [T2 Reuters, Jul–Aug 2026]; international inbound US travel is the one declining demand pillar
- Competition: Booking alt-accommodation room nights +~4% y/y in Q2 2026, slower than its core business; Airbnb Experiences supply +~80% y/y (company/IR materials)
Catalysts and risks
Catalysts
- Q3 2026 earnings (expected early November 2026): revenue vs $4.69–4.77B guide, FY margin reiteration, any Services/hotels revenue disclosure
- Any update to the buyback authorization or pace ($3.4B remaining as of 6/30/26)
- Potential take-rate commentary — confirmation or reversal of the reported 'flat FY26' guidance
- Further insider Form 4 filings in Oct–Nov — confirmation of whether Sept sales were 10b5-1-scheduled
- US inbound travel data and holiday booking commentary (key macro swing factor)
- Analyst target revisions post-Q3 from the 25-analyst Hold bloc
Risks
- Q3 in-line print with no new disclosure fails to move a skeptical Street — dead money at 30x
- Services/hotels reinvestment pressures margins below the ≥35.5% guided floor
- September insider sales turn out to be discretionary rather than 10b5-1-scheduled, or selling accelerates
- International inbound US travel decline broadens into domestic leisure weakness
- AI-driven travel discovery shifts (zero-click, agent booking) are an unmeasured risk — absence of evidence in surfaced sources is not evidence of absence
- High beta (1.24) and elevated vol mean a market-wide drawdown hits ABNB disproportionately
What to watch
- Implied take rate in Q3 materials — the single most informative number for growth quality (and verify the 'flat FY26' claim against the primary Q2 transcript)
- Nights/seats booked growth vs Q2's +10% — does acceleration hold?
- Any first-time revenue or GBV disclosure for Services/Experiences/hotels
- Buyback dollars in Q3 vs the $1.07B Q2 pace and any new authorization
- Form 4 filings through October — pattern vs one-off, and any 10b5-1 plan notations
- Booking/Expedia Q3 prints (late Oct/early Nov) as category read-through
- US inbound travel data and holiday-season booking commentary
Market snapshot when the call was made 2026-10-07
Price
| Return 1w | +2.2% |
| Return 1m | -11.8% |
| Return 3m | +12.2% |
| Return 6m | +28.3% |
| Return 1y | +33.4% |
| From 52-week high | -15.8% |
| Realized vol, 20d | 38.8% |
| SPY 3m / 1y | +4.5% / +16.4% |
| QQQ 3m / 1y | +6.8% / +25.9% |
Technicals
ABNB technicals as of 2026-10-07: last close $160.63; 20d SMA 162.26 (bearish); 50d SMA 170.56; 12d EMA 161.35; 26d EMA 164.46; RSI 14 43.3 (balanced); 20d vol 36.9%; volume x0.5 vs 20d avg
Verifier notes REVISE · opinion revised once
Unsupported claims
- why_this_matters claims ABNB at 26x next-year earnings is 'cheap relative to its own history' — the evidence bundle's valuation search explicitly concludes the opposite: the stock is 'trading near the high end of its current forward range rather than at a discount to it' (get_company_fundamentals consensus_and_valuation_search, citing forward P/E ~30.4x on 2026-10-07). No historical multiple series anywhere in the bundle supports 'cheap relative to its own history,' and the one comparative statement that exists contradicts it.
- answer and thesis characterize the September Form 4 sales as 'routine insider sales' — the evidence documents the sales (Blecharczyk 13,615 sh 9/28; Bernstein 1,489 sh 9/15) but explicitly does NOT establish they were routine; the planner digest lists 'whether September insider sales were pre-scheduled 10b5-1 plans' as an open unknown. The 'routine' label does analytical work in the sentiment-driven thesis and is unverified.
Weakly sourced
- most_differentiated_insight states 'Management guided FY26 take rate to flat' as flat fact and builds the entire watch-variable framework on it; the only source is an August 2026 research note tagged [T4] and expressly 'not verified against primary transcript' (a caveat the opinion includes in key_evidence but drops in the differentiated-insight section, where the claim is most load-bearing).
Corrections applied
- why_this_matters: delete or rephrase 'cheap relative to its own history' — e.g., 'trading near the high end of its recent forward range, so the multiple only holds IF the growth is durable.' This also removes the tension with the evidence's explicit 'high end of its forward range' conclusion.
- answer/thesis: replace 'routine insider sales' with 'documented insider Form 4 sales (10b5-1 status unverified)' to match the evidence, which confirms the sales occurred but not that they were routine.
- most_differentiated_insight: carry the T4 caveat into the claim — e.g., 'Management reportedly guided FY26 take rate to flat (T4, unverified against the primary transcript)' — since the central monitoring variable rests entirely on this single unverified note.
Sources (32 · T1 = primary filings)
- T4https://www.stocktitan.net/sec-filings/ABNB/
- T4https://www.stocktitan.net/sec-filings/ABNB/form-4-airbnb-inc-insider-trading-activity-2e5c9429e9c2.html
- T4https://www.stocktitan.net/sec-filings/ABNB/144-airbnb-inc-sec-filing-e97af6e083af.html
- T4https://www.marketbeat.com/instant-alerts/insider-insider-selling-airbnb-nasdaq-abnb-insider-sells-213510430-i…
- T4https://www.marketbeat.com/instant-alerts/filing-58621-airbnb-inc-abnb-shares-sold-by-cx-institutional-2026-10…
- T4https://www.marketbeat.com/stocks/NASDAQ/ABNB/sec-filings/
- T4https://www.stocktitan.net/sec-filings/ABNB/form-4-airbnb-inc-insider-trading-activity-3eb4f105d9e4.html
- T4https://www.investing.com/news/stock-market-news/why-is-airbnb-stock-sliding-today-93CH-4913614
- T4https://news.airbnb.com/airbnb-q2-2026-financial-results
- T4https://www.theglobeandmail.com/investing/markets/stocks/BKNG/pressreleases/293292/booking-holdings-bkng-earni…
- T4https://www.investing.com/news/company-news/booking-holdings-q2-2026-slides-steady-growth-record-capital-retur…
- T1https://ir.bookingholdings.com/overview/default.aspx
- T4https://news.airbnb.com/airbnb-q1-2026-financial-results
- T4https://www.roic.ai/quote/PCE1.DE/transcripts/2026-year/2-quarter
- T4https://finance.yahoo.com/quote/PCE1.DE/earnings/PCE1.DE-Q2-2026-earnings_call-656434.html
- T4https://finance.yahoo.com/quote/BKNG.SN/earnings/BKNG.SN-Q2-2026-earnings_call-656434.html
- T2https://www.reuters.com/business/marriott-raises-annual-room-revenue-growth-forecast-2026-08-03/
- T2https://www.reuters.com/business/hilton-raises-annual-room-revenue-growth-forecast-strong-luxury-hotel-demand-…
- T2https://www.reuters.com/business/retail-consumer/hilton-raises-annual-room-revenue-growth-forecast-strong-trav…
- T2https://www.reuters.com/business/resilient-tourists-help-us-travel-firms-absorb-middle-east-shock-2026-07-28/
- T2https://www.reuters.com/business/retail-consumer/marriott-raises-annual-room-revenue-growth-forecast-2026-05-0…
- T4https://www.ustravel.org/research/travel-recovery-insights-dashboard
- T4https://www.travelandtourworld.com/news/article/wl7fdjwvtk22/
- T4https://www.hospitalitynet.org/markets-performance/pr
- T4https://note.com/ny_bird/n/n79e7d6075630?hl=en
- T4https://www.stocktitan.net/sec-filings/ABNB/8-k-airbnb-inc-reports-material-event-522d8547b0cc.html
- T4https://www.theglobeandmail.com/investing/markets/stocks/ABNB/pressreleases/1789295/airbnb-abnb-q1-2026-earnin…
- T3https://www.spglobal.com/ratings/en/regulatory/article/-/view/sourceId/101673626
- T4https://www.stocktitan.net/sec-filings/ABNB/10-q-airbnb-inc-quarterly-earnings-report-7a08f0751b32.html
- T4https://simplywall.st/stocks/us/consumer-services/nasdaq-abnb/airbnb
- T4https://www.stocktitan.net/sec-filings/ABNB/8-k-airbnb-inc-reports-material-event-fa489e87ecd6.html
- T4https://www.stocktitan.net/sec-filings/ABNB/10-q.html
Want a fresh look at ABNB, or another name?
Queue a new deep-research run. Published to the feed when done.
Automated research opinion, published as-is on Oct 8, 2026. Not personalised advice. Figures use end-of-day closes.