Lean bullish — sentiment reset, not fundamentals.
Thesis
Bull case
The de-rating reflects a one-time Platinum investment cycle, not structural margin decay. Fee growth of +17% proves customers are absorbing $895; credit is at cyclically strong levels; the adjusted guidance floor was raised to $17.60 (eliminating the low-end miss scenario) while GAAP guidance of $18.30-18.60 exceeds the reported-EPS consensus; and layoffs demonstrate cost discipline that protects 2027 EPS. If Q4 engagement-cost growth moderates as guided, the flat 2027 consensus (~$20.12) likely drifts up and the multiple re-rates toward 18-19x — implying high-$300s. Compressed 20d vol (14th percentile) means the market is underpricing the resolution move.
Bear case
The layoffs are the tell: a company announcing 5% workforce cuts alongside a beat-and-raise sees cost pressure its guidance doesn't admit — and note the adjusted guidance 'raise' only lifted the floor to meet consensus, not exceed it, which is consistent with management protecting optics rather than expressing upside confidence. Card-member-services +36% may be the new run-rate as refreshed benefits get used (breakage assumptions fail), competitors undercut by $100-300 on price, and Q3's revenue actually missed consensus while the GAAP beat was flattered by a reserve release and one-offs — adjusted EPS growth of 13% is the real number. If the affluent consumer cracks or 2027 estimates get cut, 16x on $17.90 has no floor until ~14x ($250).
What would change our mind
- Q4'26 card-member-services expense growth stays at or re-accelerates above ~30% YoY, contradicting the moderation claim
- Delinquency rate breaks materially above the ~1.3% level held for 15 quarters, or net write-offs rise above ~2.0%
- 2027 consensus EPS is cut below ~$19.50 after the Q4 print, signaling the refresh economics don't support current growth expectations
- Revenue growth guidance for 2027 is set below ~8%, breaking the 10% algorithm
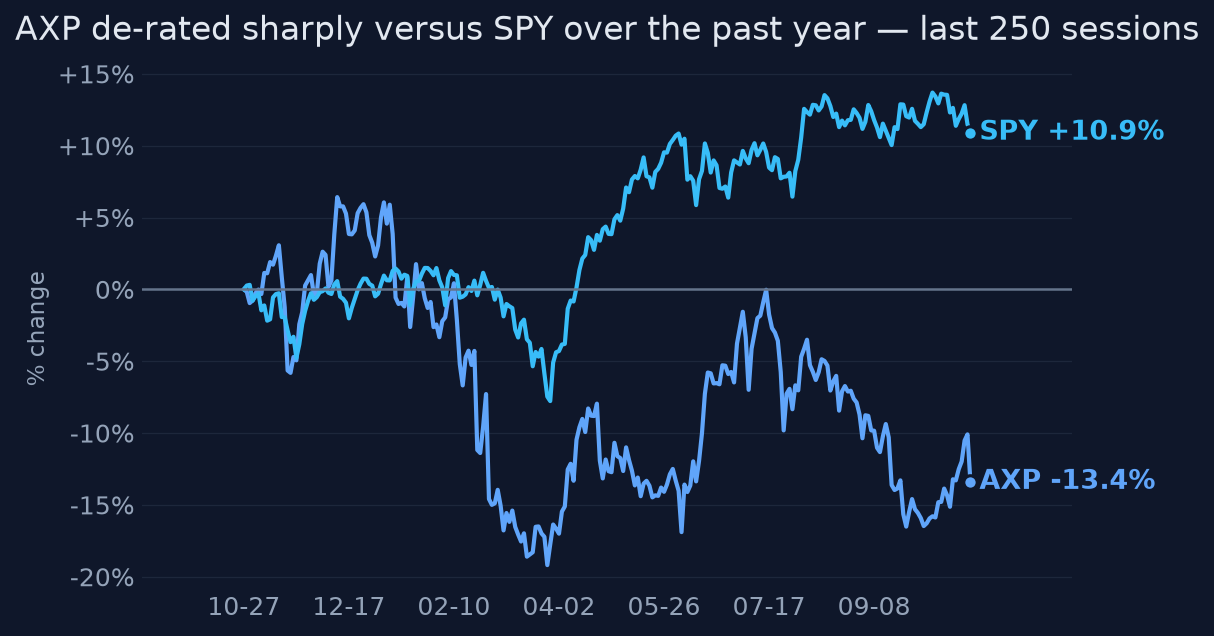
Since publication vs SPY · closed horizons are frozen
The full research everything the view rests on
Direct answer to the question asked
Where the edge would come from
What the price assumes
At ~16.2x forward P/E, the market is pricing AXP closer to a normalizing consumer lender than a premium compounder: it implicitly assumes Platinum refresh costs are at least partially structural, that the Q3 GAAP EPS beat was flattered by one-offs (reserve release), and that the ~3,500 layoffs signal margin pressure management's guidance doesn't fully admit. The guidance mechanics support the skepticism reading too: the adjusted EPS raise lifted only the bottom of the range ($17.30 -> $17.60) while the top stayed at $17.90 — exactly at consensus — so management de-risked the low end rather than guiding above the Street. Notably, 2027 EPS revisions were flat (6 up, 6 down) even after the beat-and-raise, meaning the Street has not underwritten even the in-line adjusted guidance.
Why the market may be wrong
The evidence for deterioration is thinner than the price action implies: net write-offs fell to 1.8% from 1.9%, delinquencies have been stable for 15 consecutive quarters, write-off dollars grew 3% against 8% balance growth, and fee growth accelerated rather than decelerated after the refresh. The layoffs can be read bullishly — as proactive cost control that funds the refresh without margin erosion — and the 17% card-fee growth is direct evidence the $895 price point is being absorbed. While the adjusted guidance raise was only a floor-lift, the GAAP range ($18.30-18.60) above the reported consensus signals management sees earnings quality beyond the one-off-adjusted number, and if engagement costs were a one-time launch step-up (management's explicit claim), the bear narrative collapses on a single data point.
The one thing to watch
The entire AXP debate has collapsed into one line item: Q4 card-member-services expense growth (it was +36% to ~$2B in Q3). Management explicitly guided that this growth moderates in Q4 as it laps the refresh — so the January print either confirms a temporary investment cycle (re-rating) or proves the costs are structural (thesis dead). Watching credit headlines, consumer-spend data, or competitor fee moves is noise relative to this single falsifiable number.
Key evidence (8)
- Q3'26 (reported 2026-10-23): record revenue $20.06B, +9% YoY (~10% ex small-business co-brand exits); GAAP EPS $5.42 (+31%), adjusted EPS $4.68 (+13%, beat ~$0.17) [Q3'26 earnings release, T1; Reuters, T2]
- 2026 adjusted EPS guidance raised to $17.60-17.90 (from $17.30-17.90) — a floor-lift whose top end equals the ~$17.90 consensus, i.e., downside de-risked rather than guided above the Street; separately, GAAP guidance of $18.30-18.60 sits above the reported-EPS consensus; 10% revenue growth reaffirmed [Reuters 2026-10-23, T2]
- Net card fees +17% YoY (FX-adjusted), attributed substantially to the U.S. Platinum refresh; renewals at $895 phase in from Jan 2, 2026 [Q3'26 transcript, T4 corroborated]
- Credit: net write-off rate 1.8% vs 1.9% prior year; delinquencies ~1.2-1.3%, stable 15 consecutive quarters; provisions $985M, -23% YoY aided by a reserve release [Q3'26 exhibit, T1]
- Cost concern: card-member-services expense +36% to ~$2B in Q3 tied to Platinum benefits usage; total expenses +9% to $14.5B; ~3,500 layoffs (~5% of workforce) announced alongside the beat-and-raise [Reuters, T2; Q3'26 release, T1]
- Price/vol: -11.0% 1yr, -18.6% below 52w high, -24% max drawdown; 82% idiosyncratic share vs SPY; 20d realized vol at 14th percentile of its own year — compressed [computed from daily price history]
- Valuation: forward P/E ~16.2x vs trailing ~17.7x; 2026E consensus EPS ~$17.90, 2027E ~$20.12 (~+12%); 2027 revisions flat (6 up/6 down) post-print [T4 aggregators — no verified historical P/E distribution]
- Competitive: Platinum $895 vs Chase Sapphire Reserve $795 and Citi Strata Elite $595; no direct evidence of premium share loss found, but competitors undercut on price [T4-only sourcing — treat as directional]
Catalysts and risks
Catalysts
- Q4'26 earnings (~late January 2027): the decisive test of management's claim that engagement-cost growth moderates as the company laps the Platinum refresh
- Platinum renewal/attrition data through 2026 as existing cardmembers cycle onto the $895 fee (repricing began Jan 2, 2026)
- 2027 consensus estimate revisions — currently flat; a drift up confirms the guidance raise is being underwritten
- Any regulatory/CFPB developments on swipe fees or late fees affecting card economics
Risks
- Q4 engagement costs fail to moderate, confirming structural margin erosion from the refresh — the core bear leg
- Q3 revenue missed consensus (~$20.06B vs ~$20.12B expected): top-line momentum is slightly softer than the EPS beat suggests
- The adjusted guidance raise lifted only the floor to the consensus level ($17.90 top of range = consensus) — less bullish signal than a clean above-Street guide
- Reserve release flattered Q3 provision optics; credit normalization from unusually strong levels would compress the multiple regardless of spend strength
- Competitive pressure from Sapphire Reserve ($795) and Strata Elite ($595) could pressure new-account acquisition even as fee revenue holds
- Platinum attrition at $895 is undisclosed — retention risk is real but unquantified in the evidence
- Competitive-landscape and refresh-reception evidence rests largely on T4 sources; the strongest claims (17% fee growth, cost moderation) rely on management assertion pending Q4 verification
What to watch
- Q4'26 card-member-services expense YoY growth — the single decisive number (Q3 was +36%; moderation = thesis confirmed)
- Net card-fee growth trajectory as the $895 renewal cohort fully laps (17% in Q3)
- Delinquency and net write-off rates in the monthly/Q4 credit disclosures vs the 1.2-1.3% / 1.8% baselines
- 2027 EPS revision direction post-Q4 print (flat today — a turn up is the re-rating trigger)
- Any disclosure on Platinum retention/attrition at the new $895 price point
- Whether revenue growth ex small-business exits holds ~10%
Market snapshot when the call was made 2026-10-23
Price
| Return 1w | -0.1% |
| Return 1m | +2.5% |
| Return 3m | -6.6% |
| Return 6m | -0.3% |
| Return 1y | -11.0% |
| From 52-week high | -18.6% |
| Realized vol, 20d | 19.5% |
| SPY 3m / 1y | +2.8% / +13.8% |
| QQQ 3m / 1y | +3.3% / +16.3% |
Technicals
AXP technicals as of 2026-10-23: last close $313.22; 20d SMA 310.12 (bearish); 50d SMA 319.19; 12d EMA 315.03; 26d EMA 314.42; RSI 14 60.6 (balanced); 20d vol 19.1%; volume x1.3 vs 20d avg
Verifier notes REVISE · opinion revised once
Unsupported claims
- Claim (in thesis, market_expectation, bull_case, and key_evidence item 2) that the raised adjusted EPS guidance of $17.60-17.90 'sits above the un-updated consensus' / 'was raised above consensus.' The evidence shows 2026E consensus EPS is ~$17.90, which equals the TOP of the raised adjusted range; the raise lifted only the bottom end ($17.30 -> $17.60). The guidance figure that the evidence describes as above consensus is the GAAP range ($18.30-18.60) vs the $17.90 reported-EPS consensus — a different comparison. Stating the adjusted range sits above consensus is arithmetically wrong on the evidence's own numbers.
Corrections applied
- Rewrite the guidance-vs-consensus framing wherever it appears (thesis, market_expectation, bull_case, key_evidence): the 2026 adjusted EPS guidance raise narrowed/raised the bottom of the range to $17.60-17.90, with the top of the range equal to the ~$17.90 consensus — i.e., management de-risked the low end rather than guiding above the Street. The bullish point can be preserved accurately by noting the GAAP guidance ($18.30-18.60) sits above the reported-EPS consensus, and that the raised adjusted floor plus flat 2027 revisions still leaves room for upward drift if Q4 cost moderation confirms.
Sources (15 · T1 = primary filings)
- T4https://www.stocktitan.net/articles/american-express-q3-2026-earnings-card-fees
- T4https://www.cnn.com/cnn-underscored/money/best-premium-credit-cards
- T4https://corporateinsight.com/premium-card-digital-experiences-which-mobile-reward-platform-is-best/
- T4https://thepointsguy.com/credit-cards/tpg-awards-2026-premium-card-of-the-year/
- T4https://thepointsguy.com/credit-cards/best-premium-travel-rewards-cards/
- T4https://money.usnews.com/credit-cards/articles/how-amex-platinum-measures-up-against-sapphire-reserve-and-stra…
- T4https://www.theglobeandmail.com/investing/markets/stocks/AXP/pressreleases/37343649/american-express-earnings-…
- T4https://stockanalysis.com/stocks/axp/transcripts/655622-q3-2026/
- T4https://finance.yahoo.com/markets/stocks/articles/american-express-raises-profit-outlook-070502797.html
- T4https://finance.yahoo.com/markets/stocks/articles/american-express-q2-2026-earnings-115108680.html
- T2https://www.reuters.com/business/american-express-raises-2026-profit-forecast-affluent-customers-keep-spending…
- T4https://www.stocktitan.net/sec-filings/AXP/
- T1https://www.sec.gov/Archives/edgar/data/4962/000000496226000405/q326exhibit991.htm
- T4https://www.tradingview.com/news/zacks:7acf988f8094b:0-american-express-q3-earnings-beat-estimates-on-strong-c…
- T4https://finance.yahoo.com/m/4dc327ec-3457-3d78-985c-52b10fac88c0/american-express-q2-2026.html
Earlier and later calls on AXP
- Oct 6, 2026Pullback looks overdone — lean bullish.Lean bullish
Want a fresh look at AXP, or another name?
Queue a new deep-research run. Published to the feed when done.
Automated research opinion, published as-is on Oct 26, 2026. Not personalised advice. Figures use end-of-day closes.