Pullback looks overdone — lean bullish.
Thesis
Bull case
The de-rating is macro mechanical, not fundamental. AXP's affluent cardmember base is demonstrably decoupled from the aggregate consumer (+11% US consumer spend vs ~1.3% aggregate spending growth), credit is stable-to-improving with reserves being released, and FY26 EPS estimates have risen through the selloff. At ~15x FY27 EPS of ~$20, even a partial multiple re-rating to 18-19x FY27 implies $360-380, or +18-25% from $304, within the 3-6 month horizon — and that arithmetic stands on consensus estimates alone, without needing the unverified 'low-20s forward P/E earlier this year' commentary to be accurate. Q3 on Oct 23 confirming 2.0% write-offs and ≥9% billed business is the trigger.
Bear case
The market may be correctly front-running the affluent consumer's eventual crack: credit metrics are lagging indicators, and the macro backdrop (12.5-year-low confidence, tariff drag, a Fed that is HIKING) has historically preceded credit normalization with a delay. Management's refusal to raise EPS guidance while raising revenue guidance is a tell that expense growth (+12%) is structurally outpacing revenue (+10%) — Platinum engagement costs are sticky, and if billing growth decelerates to 6-7%, operating leverage goes negative fast. A second Fed hike extends the lender de-rating regardless of AXP's print. And while the stock is only ~5% above its 52-week low with RSI at 26, oversold conditions can persist for months in a hiking cycle — there is no mechanical floor here.
What would change our mind
- Q3 2026 net write-off rate rises above ~2.2% or 30-day delinquencies break above ~1.4% — would validate the market's front-running of credit deterioration
- Q3 billed business growth decelerates below ~7% FX-adjusted, breaking the affluent-decoupling thesis
- Management cuts or narrows FY26 EPS guidance below $17.30 on Oct 23
- A reserve BUILD in Q3 after two quarters of releases — the clearest forward-looking credit signal management controls
Since publication vs SPY · closed horizons are frozen
The full research everything the view rests on
Direct answer to the question asked
Where the edge would come from
What the price assumes
At ~17x FY26 consensus EPS of $17.64, the market is pricing meaningful risk that AXP's premium cohort eventually follows the aggregate consumer down — i.e., that current credit metrics are a lagging indicator. The post-Q2 reaction (stock -6% despite a beat and raised revenue guidance) shows investors also doubt management's reinvestment will convert to future EPS, treating the unchanged $17.30-$17.90 EPS guide as a ceiling rather than a choice.
Why the market may be wrong
Three pieces of hard data argue the selloff front-runs a deterioration that hasn't arrived: (1) AXP released reserves in both Q1 ($24M) and Q2 ($191M) — companies building toward a credit problem don't release; (2) FY26 consensus EPS rose from $17.41 (Jan) to $17.64 (Oct) while the stock fell 13%, meaning the drawdown is pure multiple compression; (3) AXP's affluent-skewed US consumer spend grew +11% in Q2 against aggregate consumer spending of ~1.3% annualized — the decoupling is the business model, not a coincidence.
The one thing to watch
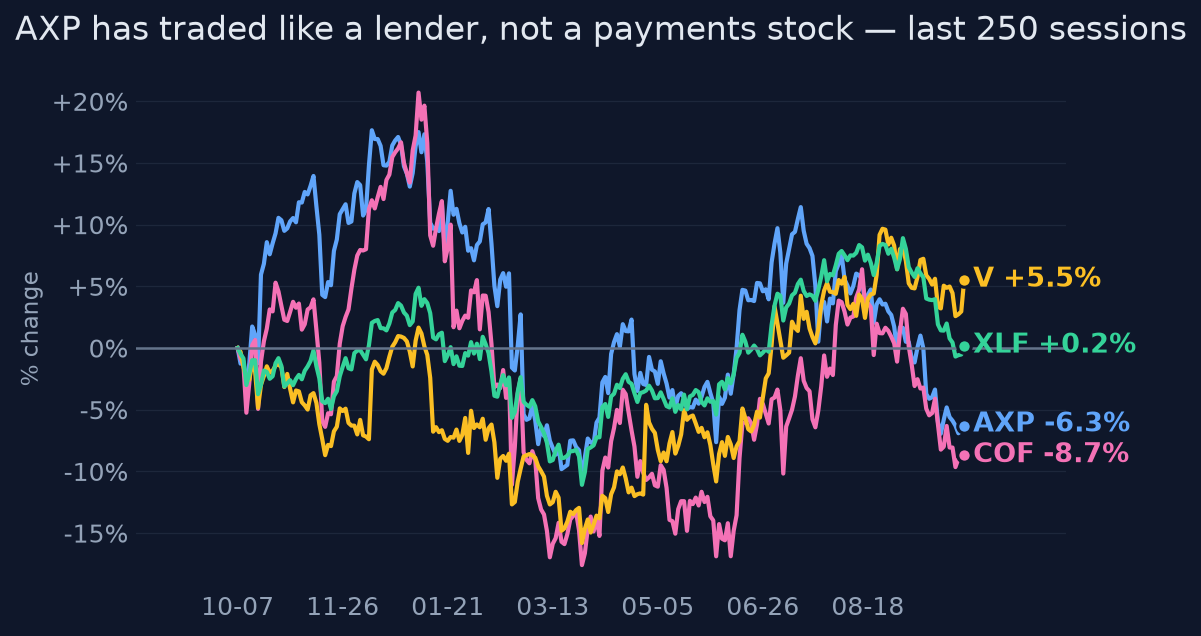
The single most useful reframe: AXP is currently being priced as a subprime-adjacent lender (1y return ≈ COF's -8.7%, correlation with XLF 0.74) while its own credit book behaves like a payments franchise (delinquencies below pre-COVID, reserve releases). The variable to watch is not billed business — it's whether Q3 net write-offs stay pinned at ~2.0%. If they do, the stock is misclassified and the lender-multiple discount is misapplied; that misclassification, not spend growth, is the trade.
Key evidence (9)
- Q2 2026 (Jul 24): adjusted EPS $4.53 vs ~$4.41 consensus; revenue $19.64B +10% y/y; FY26 revenue guidance raised to 10% growth, EPS guide reaffirmed $17.30-$17.90 [T1 8-K exhibit; T2 Reuters]
- Credit: net write-offs 2.0% in both Q1 and Q2 2026 (Q1 vs 2.1% a year earlier; Q2 flat versus the prior-year period per the 8-K exhibit); 30-day delinquencies 1.2-1.3%, below 2019 levels; reserve releases of $24M (Q1) and $191M (Q2) [T1 SEC exhibits]
- FY26 consensus EPS rose from $17.41 (Jan 30, LSEG via Reuters) to $17.64 (Oct 6) while the stock fell ~13% over 3 months [T2 Reuters, Oct 6, 2026]
- Billed business +9% FX-adjusted in both Q1 and Q2 2026; US consumer services +10% Q1, +11% Q2; Platinum refresh driving retention and acquisition [T1]
- Sector context: 1m returns AXP -7.8%, XLF -8.0%, COF -11.5%, V -2.4%; AXP 1y return -7.0% ≈ COF -8.7% vs Visa +7.5% — lender de-rating, not payments de-rating [computed from price history]
- Macro drivers: Fed hiked mid-September 2026 [T2 Reuters]; consumer confidence at ~12.5-year low in September [T2]; Fed July MPR: consumer spending growth slowed to ~1.3% annualized, tariffs cited [T1 Federal Reserve]
- Valuation: ~17x FY26 consensus EPS and ~15x FY27 (~$20); commentary earlier in 2026 had forward P/E in the low-20s [T4 commentary — no primary-source P/E series verified]
- Q2 expenses +12% vs revenue +10%, driven by engagement costs and Platinum benefit usage; management explicitly chose to reinvest upside rather than raise EPS guidance [T1/T2]
- Q3 2026 earnings call scheduled Friday, Oct 23, 2026, 8:30am ET [T1 IR]
Catalysts and risks
Catalysts
- Q3 2026 earnings, Friday Oct 23, 2026 8:30am ET — billed business trend, credit metrics, and any EPS guidance raise [T1 IR]
- Q4 2026 earnings Jan 28, 2027 — first look at FY27 guidance vs ~$20 consensus
- Fed policy path — whether the September 2026 hike is followed by another in Q4
- Monthly consumer data (confidence, retail spending, delinquency aggregates) that either confirms or refutes the affluent-cohort decoupling
- Potential analyst re-rating cycle if Q3 confirms stable credit
Risks
- Aggregate consumer deterioration finally reaching the affluent cohort — delinquencies/write-offs inflecting above 2.2-2.3%
- Negative operating leverage: expenses +12% vs revenue +10% persists and compresses margins into 2027
- Further Fed tightening extending the consumer-finance multiple de-rating independent of AXP's fundamentals
- Platinum refresh economics disappointing — elevated acquisition/engagement costs without commensurate spend lift
- Regulatory/competitive overhang (Credit Card Competition Act, DOJ case, Chase/Capital One premium competition) was not deeply verified in this research round
What to watch
- Q3 net write-off rate vs the 2.0% level reported in both Q1 and Q2 2026 — the single most important number
- Q3 billed business growth (≥9% FX-adj confirms thesis; <7% breaks it)
- Whether FY26 EPS guidance ($17.30-$17.90) finally gets raised — a raise after Q2's reinvestment choice would be a strong signal
- Expense growth vs revenue growth spread (12% vs 10% in Q2)
- AXP's performance relative to COF vs Visa — if it starts trading with V instead of COF, the misclassification is correcting
- Fed communications into year-end and monthly consumer confidence/spending prints
- Any reserve build/release direction in the Q3 8-K exhibit
Market snapshot when the call was made 2026-10-05
Price
| Return 1w | -0.8% |
| Return 1m | -7.8% |
| Return 3m | -13.0% |
| Return 6m | -0.3% |
| Return 1y | -7.0% |
| From 52-week high | -20.4% |
| Realized vol, 20d | 20.1% |
| SPY 3m / 1y | +3.6% / +15.8% |
| QQQ 3m / 1y | +6.6% / +24.8% |
Technicals
AXP technicals as of 2026-10-05: last close $304.02; 20d SMA 312.03 (bearish); 50d SMA 327.01; 12d EMA 307.21; 26d EMA 314.51; RSI 14 26.3 (oversold); 20d vol 19.9%; volume x0.8 vs 20d avg
Next earnings: 2027-01-28 AMC
Verifier notes REVISE · opinion revised once
Unsupported claims
- what_to_watch claims 'the 2.0% [net write-off] level held for four straight quarters' — the evidence supports only two quarters at 2.0% (Q1 and Q2 2026). No Q3/Q4 2025 write-off data appears anywhere in the bundle, so 'four straight quarters' is a fabricated specific that overstates the stability track record.
- bear_case claims 'the stock already trades above pre-2026 levels on a multi-year view' — the bundle contains no multi-year price history beyond the trailing 1 year, and the 1y return is -7.0% (i.e., the stock is BELOW its October 2025 level). This claim is unverifiable from the evidence and plausibly wrong.
- key_evidence states net write-offs were '2.0% in both Q1 and Q2 2026 (vs 2.1% prior year)' — the '2.1% prior year' comparison is sourced only for Q1; the Q2 evidence says 2.0% was 'flat versus the prior quarter / prior-year period,' implying Q2 2025 was also ~2.0%. Minor but the parenthetical overgeneralizes the prior-year comparison.
Weakly sourced
- The thesis asserts the multiple 'should recover toward the low-20s forward P/E it carried earlier in 2026' — the low-20s forward P/E is T4 commentary only, with the evidence explicitly noting no primary-source P/E series was verified. The opinion does flag this in key_evidence, which mitigates it, but the thesis and bull case state it as established fact and the re-rating argument leans on it materially.
Corrections applied
- Change 'the 2.0% level held for four straight quarters' to 'the 2.0% level held in both reported quarters of 2026 (Q1 and Q2)' unless Q3/Q4 2025 write-off data is sourced.
- Remove or rewrite 'the stock already trades above pre-2026 levels on a multi-year view' in the bear_case — e.g., replace with the verifiable point that the stock is only ~5% above its 52-week low and oversold conditions can persist, or source actual multi-year price data.
- In key_evidence, scope the prior-year comparison: 'net write-offs 2.0% in both Q1 and Q2 2026 (Q1 vs 2.1% a year earlier; Q2 flat y/y per the 8-K exhibit)'.
- In the thesis, attribute the low-20s historical forward P/E explicitly as unverified commentary (as already done in key_evidence) rather than stating it as fact, or drop the specific 'low-20s' anchor and frame the re-rating case on the 17x→18-19x arithmetic alone.
Sources (25 · T1 = primary filings)
- T4https://uk.investing.com/news/transcripts/earnings-call-transcript-american-express-beats-q2-2026-eps-shares-f…
- T1https://www.sec.gov/Archives/edgar/data/4962/000000496226000318/q226exhibit991.htm
- T4https://www.investing.com/news/transcripts/earnings-call-transcript-american-express-beats-q2-2026-eps-shares-…
- T4https://finance.yahoo.com/quote/AXP/earnings/AXP-Q2-2026-earnings_call-546571.html
- T4https://finance.yahoo.com/quote/AEC1.SG/earnings/AEC1.SG-Q2-2026-earnings_call-546571.html
- T4https://finance.yahoo.com/quote/AXP.SW/earnings/AXP.SW-Q2-2026-earnings_call-546571.html
- T4https://fortune.com/company-assets/1678/quartr/earnings-release-8-k-d7c58-2026-04-23-11-21-01.pdf
- T4https://www.investing.com/news/transcripts/earnings-call-transcript-american-express-q1-2026-beats-expectation…
- T4https://finance.yahoo.com/quote/AEC1.DU/earnings/AEC1.DU-Q2-2026-earnings_call-546571.html/
- T4https://finance.yahoo.com/markets/stocks/articles/american-express-q2-2026-earnings-115108680.html
- T2https://www.reuters.com/markets/companies/AXP.N/
- T4https://ng.investing.com/news/transcripts/earnings-call-transcript-american-express-beats-q2-2026-eps-shares-f…
- T1https://ir.americanexpress.com/news/investor-relations-news/investor-relations-news-details/2026/American-Expr…
- T1https://ir.americanexpress.com/events/event-details/2026/Q3-2026-American-Express-Earnings-Conference-Call/def…
- T4https://fortune.com/company/american-express/earnings/q1-2026/
- T4https://www.marketbeat.com/earnings/reports/2026-4-23-american-express-stock/
- T4https://www.stocktitan.net/sec-filings/AXP/10-q-american-express-co-quarterly-earnings-report-cff34d50d2b7.htm…
- T1https://www.federalreserve.gov/monetarypolicy/files/20260710_mprfullreport.pdf
- T2https://www.reuters.com/markets/global-markets-technicals-2026-10-02/
- T2https://www.reuters.com/business/us-stock-futures-flat-tech-bounce-meets-crude-driven-caution-2026-09-29/
- T2https://deloitte.wsj.com/cfo/2026-u-s-economic-outlook-3e1d6fd8
- T4https://ceritypartners.com/insights/q1-2026-review-and-q2-2026-economic-and-market-outlook/
- T4https://www.deloitte.com/us/en/insights/topics/economy/us-economic-forecast/2026-q1.html
- T4https://www.cbia.com/news/economy/2026-economic-outlook/
- T2https://www.reuters.com/business/retail-consumer/what-do-higher-rates-mean-borrowers-savers-2026-09-16/
Earlier and later calls on AXP
- Oct 26, 2026Lean bullish — sentiment reset, not fundamentals.Lean bullish
Want a fresh look at AXP, or another name?
Queue a new deep-research run. Published to the feed when done.
Automated research opinion, published as-is on Oct 6, 2026. Not personalised advice. Figures use end-of-day closes.