Lean bullish — but less cheap than flagged.
Thesis
Bull case
TSMC reports in-line-or-better margins on Oct 15, guides Q4 to continued sequential growth, and validates the FY27 consensus of ~35% revenue growth — at which point a stock at ~20.6x FY27 earnings, below its own ~29.3x three-year trailing average, with 40%+ current growth and a $164B committed capex/Arizona program, reprices toward its historical multiple. Even a partial normalization to 22-25x FY27 EPS of $22.05 implies $485-551, roughly +7-22% over 6-12 months — attractive but not the dramatic discount the aggregator data suggested. TSMC remains one of the few AI-exposed large caps trading below its own historical valuation average, with the most pricing power (3-10% advanced-node price increases for 2026) and the deepest moat (neither Samsung nor Intel Foundry displaces it in 2026-27). Hyperscaler capex revisions are still upward, and no customer has cut a single order.
Bear case
The FY27 consensus that makes TSM look reasonably priced is built on an AI financing chain that cracked publicly on Oct 8-9: OpenAI's real revenue (~$50B annualized) cannot obviously service the compute commitments that flow through NVIDIA/Broadcom/AMD into TSMC's order book, and vendor-financed demand is reflexive — when the financing stops, so does the demand. TSMC's revenue concentration in ≤7nm/HPC (~77% of wafers) means a 2027 capex digestion hits it directly, and at ~26.7x FY26 earnings there is no deep-value cushion in the near term. Meanwhile margin structure is deteriorating by design (2nm drag, US manufacturing costs 20-50% higher, construction 4-5x), Section 232 phase 2 could remove the data-center exemption and tax AI infrastructure demand, the Dec 31 China-fab licensing cliff adds friction, and a 1.85-beta stock at record market cap ($2.35T) offers no protection in a risk-off tape. An 'in-line' Oct 15 guide could itself be a sell-the-news event given the stock is 6.7% off highs with calm implied conditions.
What would change our mind
- Oct 15 Q4 guidance implies sequential decline or management declines to endorse anything close to FY27 consensus growth — thesis shifts from 'fairly priced growth' to 'full multiple on peak estimates'
- Any confirmed hyperscaler 2026/2027 capex cut or TSMC order deferral (vs the current zero-cut, upward-revision evidence)
- FY27 EPS consensus cuts begin (the 9-up/0-down streak reversing) — the below-average-multiple argument depends on $22 FY27 EPS being real
- Q3 gross margin lands below 65% (bottom of guide), signaling overseas/2nm dilution is worse than quantified
- Section 232 phase 2 removes the data-center exemption AND extends to servers — converts a scenario risk into a direct demand tax
- Evidence emerges of actual OpenAI-linked order cancellations or vendor-financing withdrawal (not just revenue-miss headlines)
Since publication vs SPY · closed horizons are frozen
The full research everything the view rests on
Direct answer to the question asked
Where the edge would come from
What the price assumes
At $453, the market prices TSMC as a SOXX proxy with a haircut: ~20.6x FY27 earnings against ~35% expected growth implies investors either doubt FY27 consensus or are applying a persistent geopolitical/China-exposure discount. The calm 20-day realized vol (24th percentile of its own year) heading into earnings suggests the market expects a solid-but-not-explosive report — the bar for Oct 15 is Q4 guidance and 2027 color, not Q3, which is already known to have beaten.
Why the market may be wrong
The discount may be over-applied: TSMC's reported revenue is booked and real (+50% YoY), hyperscaler 2026 capex of $700-750B is still being revised upward with zero cuts, Broadcom's AI revenue grew 221% YoY with reaffirmed guidance, and US officials reportedly assess pre-2028 invasion risk as low. Alternatively, the market may be under-pricing the circularity risk in the other direction: OpenAI's annualized revenue (~$50B per FT reporting vs ~$68-70B previously circulated) sits underneath a financing chain (NVIDIA's $100B investment, Broadcom's ~$50B arrangement, AMD warrants) that funds a large share of the AI demand TSMC's FY27 consensus assumes. The market is treating this as a sentiment wobble; it could be the first real crack in the demand assumption.
The one thing to watch
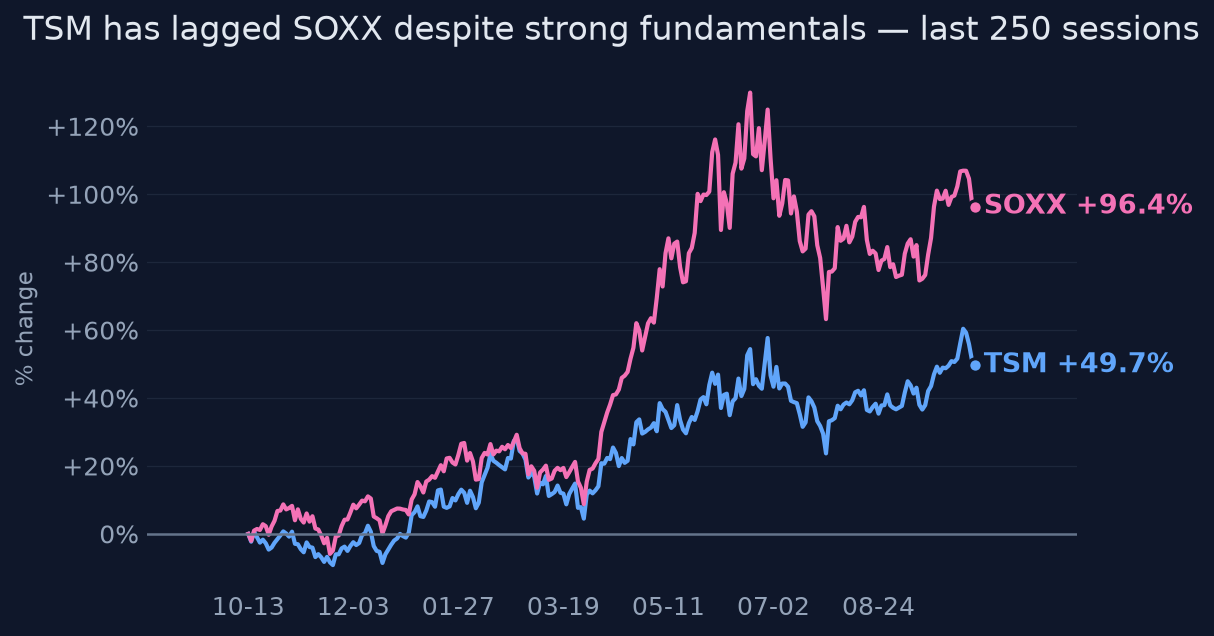
The variable to watch is not TSMC's quarter — it is whether OpenAI-tier revenue reality can service the financing circularity that underwrites FY27 consensus; TSMC at 0.89 SOXX correlation and 43 points of underperformance means you are holding the one company in the basket whose revenue is already booked, at a FY27 multiple below its own historical average, while the downside scenario (a 2027 AI capex digestion) would hit every higher-multiple alternative in the basket harder. Watch OpenAI revenue disclosures and any first order-deferral headline, not the Q3 print.
Key evidence (12)
- Q3 2026 revenue NT$1.49T / ~US$46.7B, +50% YoY, above the US$44.6-45.8B guidance ceiling (Reuters, Oct 8, 2026) [T2]
- FY26 revenue growth guided to slightly above 40% YoY in USD; capex raised to $60-64B plus an additional $100B Arizona commitment (Q2 2026 earnings call, July 2026) [T4 transcript / T2 Reuters]
- Valuation recomputed from stated inputs: $453.31 / $16.96 FY26 consensus EPS = ~26.7x; $453.31 / $22.05 FY27 consensus EPS = ~20.6x; trailing P/E 32.7x vs 3-year average 29.3x. NOTE: T4 aggregators quoted 20.3x/15.6x, which is arithmetically irreconcilable with the consensus EPS they cite (likely a different NTM-blended EPS basis) — all multiple data here is T4-sourced and requires primary verification
- Estimate revisions 9 raises / 0 cuts to FY26 EPS in the 30 days to Oct 5, 2026 (T4 aggregator — directional only)
- Stock +48.9% 1y but SOXX +91.9% over the same period; 0.89 correlation with SOXX; beta 1.85 to SPY; 20d vol 29.8% (24th percentile) — calm tape into earnings
- Q2 gross margin 67.7% (above guide); Q3 guided 65-67% embedding a 3-4pt 2nm ramp drag plus overseas-fab dilution of 2-3pts initially, up to 3-4pts at scale (Q2 call) [T4, partially primary-sourced]
- FT-reported OpenAI annualized revenue ~$50B vs ~$68-70B previously circulated triggered the Oct 8-9 semi selloff (SOX -3.4%); NVIDIA's $100B OpenAI investment, AMD warrants, and Broadcom's ~$50B financing arrangement raised circularity concerns [T2/T4 mix]
- Hyperscaler 2026 capex estimates $700-750B (up to ~$940B incl. Oracle), still being revised upward; Broadcom Q3 AI revenue +221% YoY with reaffirmed guidance [T3/T4]
- TSMC's validated end-user exemption for US tool shipments to China fabs expires Dec 31, 2026 — a dated operational/licensing risk [T4, weakly sourced]
- Section 232: 25% tariff on certain advanced chips since Jan 2026 with US data-center exemption; phase-2 broadening unresolved [T4, flag as weakly sourced]
- US officials reportedly see pre-2028 Chinese invasion risk as low; persistent gray-zone pressure continues (Reuters, Oct 2026) [T2]
- Musk confirmed preliminary 'Terafab' talks with TSMC on Oct 5, driving a record high; explicitly 'just discussions' [T4]
Catalysts and risks
Catalysts
- Oct 15, 2026: full Q3 report — gross margin vs 65-67% guide, Q4 revenue guidance, first FY27 commentary, capex update (the decisive near-term event)
- Monthly revenue releases (Nov 10, Dec 10) — September beat already confirmed the trajectory; any deceleration below ~30% YoY would pressure FY27 consensus
- Dec 31, 2026: expiry of TSMC's validated end-user exemption for US tool shipments to China fabs — licensing terms announced before or after
- Section 232 phase-2 decision: retention or removal of the US data-center tariff exemption, possible extension to servers/downstream products
- Hyperscaler Q3 earnings (late Oct-Nov): 2026/2027 capex guidance — any first cut would be the bubble-confirmation signal
- Further OpenAI revenue disclosures and any evidence of order deferrals or deployment delays from power bottlenecks
- January 2027 earnings: formal FY27 guidance and 2nm (N2P) ramp economics
Risks
- AI capex digestion in 2027: FY27 consensus (+35% revenue) assumes the OpenAI-linked financing chain holds; a circularity unwind would hit both earnings estimates and the multiple simultaneously
- Sell-the-news on Oct 15: Q3 beat is already public, so an in-line Q4 guide or cautious 2027 tone could trigger downside despite good numbers
- Structural margin erosion: overseas fabs (US costs 20-50% higher, construction 4-5x) could prove permanently dilutive rather than transitional
- Section 232 phase 2 removes the data-center exemption, raising AI infrastructure costs and dampening US demand
- China-fab licensing friction after Dec 31, 2026 expiry of the validated end-user exemption
- Taiwan escalation: low probability per US officials, but a 1.85-beta stock with concentrated Taiwan manufacturing has extreme tail exposure
- Customer concentration: NVIDIA/Apple/AMD demand is the growth story — any single customer's inventory correction is material
- Evidence fragility: all consensus/valuation aggregates in this bundle are T4 sources, and the aggregator forward multiples (20.3x/15.6x) are demonstrably inconsistent with the cited consensus EPS — the corrected multiples (~26.7x/~20.6x) are themselves computed from unverified T4 EPS figures
What to watch
- Oct 15: Q4 guidance midpoint vs ~US$46.7B Q3 actual, and whether management frames FY27 at, above, or below the ~35% growth consensus
- Oct 15: reported Q3 gross margin vs 65-67% — a print at/above 67% would signal the 2nm drag is being absorbed faster than guided
- Primary-source verification of consensus EPS and forward multiples — the T4 aggregator figures (20.3x/15.6x) are internally inconsistent, and the entire valuation framing depends on which basis is real
- Monthly revenue: November and December prints — watch for YoY growth dropping below ~30%
- FY27 EPS revision direction over the next 30 days — continuation of the raise streak vs first cuts
- Hyperscaler capex language in late-October earnings (Microsoft, Alphabet, Amazon, Meta) — any shift from 'constrained by supply' to 'digesting capacity'
- OpenAI revenue run-rate updates and any news on the NVIDIA/Broadcom/AMD financing structures being resized
- Dec 31 China-fab licensing outcome and Section 232 phase-2 scope
- TSM/SOXX relative strength — whether the 43-point gap closes (thesis working) or widens (structural discount deepening)
Market snapshot when the call was made 2026-10-09
Price
| Return 1w | -4.1% |
| Return 1m | +5.9% |
| Return 3m | +7.5% |
| Return 6m | +22.3% |
| Return 1y | +48.9% |
| From 52-week high | -6.7% |
| Realized vol, 20d | 29.8% |
| SPY 3m / 1y | +3.9% / +15.7% |
| QQQ 3m / 1y | +5.5% / +22.9% |
Technicals
TSM technicals as of 2026-10-09: last close $453.31; 20d SMA 450.47 (bullish); 50d SMA 432.47; 12d EMA 460.46; 26d EMA 449.72; RSI 14 54.7 (balanced); 20d vol 26.2%; volume x0.9 vs 20d avg
Verifier notes REVISE · opinion revised once
Unsupported claims
- Central valuation claim — '~20x FY26 and ~15.6x FY27 consensus EPS' at $453 — fails arithmetic on the opinion's own stated inputs: $453.31 / $16.96 FY26 consensus EPS ≈ 26.7x, and $453.31 / $22.05 FY27 consensus EPS ≈ 20.6x. The 20.3x/15.6x figures appear verbatim in the T4 aggregator evidence, but the evidence's own derivation ('Using the 2026 consensus EPS of US$16.96, the implied forward valuation is approximately 20.3x') is arithmetically wrong, and the opinion propagates it. This is not cosmetic: the 'cheap for its growth' framing in direct_answer, thesis, market_expectation, why_this_matters, and the bull case's 22-25x re-rating target all rest on these multiples. If the true multiples are ~27x/~21x, the stock still screens below its 29.3x 3-yr trailing average on FY27 but NOT at the dramatic discount claimed on FY26, and the bull-case upside to $485-550 shrinks accordingly (from ~20.6x, 22-25x implies only ~7-21% upside, not ~41-60%).
- Bull-case superlative: 'the only AI-exposed large cap trading below its own historical valuation average' — the bundle contains no comparative valuation-vs-history data for any other AI large cap (NVDA, AVGO, etc.), so 'the only' is unsupported.
Weakly sourced
- The forward multiples (20.3x/15.6x) and trailing-average P/E (29.3x) are T4 aggregator data that the opinion itself flags as unverified in key_evidence, yet they are stated as settled fact in the direct_answer and thesis, which is where a reader's trust is formed. The discrepancy with the arithmetic (point 1 above) makes the unverified-T4 caveat load-bearing rather than a footnote.
Corrections applied
- Recompute and restate the valuation: at $453.31 with consensus EPS of $16.96 (FY26) and $22.05 (FY27), the multiples are ~26.7x and ~20.6x respectively. Either (a) use these recomputed figures throughout and re-frame the thesis as 'below its 3-yr trailing average on FY27 earnings with ~35% growth,' or (b) if the aggregator multiples are retained, explicitly caveat that they imply a different (likely NTM-blended) EPS basis irreconcilable with the cited consensus EPS and require primary verification. Adjust the bull-case re-rating math to start from the corrected current multiple.
- Soften the bull-case claim to 'one of the few AI-exposed large caps trading below its own historical valuation average' or delete the superlative, since no peer valuation-vs-history comparison exists in the evidence.
- Minor numeric fix: the thesis states overseas-fab dilution of '2-4pts'; the evidence says 2-3pts initially, rising to 3-4pts at scale — restate as '2-3pts initial, up to 3-4pts at scale' to match the sourced range.
Sources (32 · T1 = primary filings)
- T2https://www.reuters.com/5f374b32b07b/world/china/taiwan-cherishes-peace-will-not-give-up-its-freedom-president…
- T4https://economictimes.indiatimes.com/tech/technology/tsmc-gets-pulled-into-taiwan-election-fray-at-vp-debate/p…
- T2https://www.reuters.com/5f374b32b07b/world/china/eswatini-king-pledges-strengthen-enduring-friendship-with-tai…
- T1https://un.china-mission.gov.cn/eng/fyrth/202610/t20261006_12035790.htm
- T4https://theprint.in/world/us-says-chinese-actions-off-taiwan-are-deeply-destabilising/3067327/?amp
- T4https://economictimes.indiatimes.com/news/international/business/samsung-wins-us-nod-to-ship-chipmaking-tools-…
- T4https://cranberryjournal.com/ai/the-exemption-under-the-buildout/
- T4https://www.timeslive.co.za/news/world/2026-10-10-taiwan-cherishes-peace-but-will-not-give-up-freedom-presiden…
- T4https://finance.yahoo.com/markets/stocks/articles/tsmc-reports-oct-15-best-075802191.html
- T4https://ground.news/article/tsmc-stock-hits-record-high-as-ai-chip-demand-lifts-taiwan-market
- T4https://finance.yahoo.com/markets/stocks/article/tsmc-stock-hits-all-time-high-after-elon-musk-confirms-early-…
- T4https://ground.news/article/tsmc-shares-close-at-record-48595-as-terafab-talks-draw-attention_97febb
- T4https://www.stocktitan.net/articles/tsmc-samsung-ai-chip-numbers-volume-or-price
- T4https://www.thefly.com/tsm/transcripts?storyid=4408563
- T4https://finance.yahoo.com/markets/stocks/articles/m-loading-taiwan-semiconductor-ahead-111529120.html
- T4https://primexbt.com/news/tsmc-stock-closes-at-record-high-as-ai-chip-demand-lifts-taiwan-market/
- T2http://rmb.reuters.com/rmd/rss/item/tag:reuters.com,2026:newsml_KBN3VL1LD?channel=frL012
- T4https://startupfortune.com/chip-stocks-sink-into-a-correction-even-as-samsung-posts-record-profit/
- T4https://finance.yahoo.com/markets/articles/morning-bid-sovereign-bonds-shouldered-043756336.html
- T4https://www.home.saxo/content/articles/macro/market-quick-take---ai-revenue-doubts-hit-chipmakers-oil-and-yiel…
- T4https://gpusmith.com/articles/en/hyperscaler-ai-capex-2026
- T4https://techblog.comsoc.org/
- T4https://www.ubs.com/us/en/assetmanagement/insights/investment-outlook/the-red-thread/trt-end-year-2026/article…
- T4https://www.perplexity.ai/finance/SMH
- T4https://tech-insider.org/tsmc-earnings-capex-arizona-2026/
- T4https://finance.yahoo.com/quote/TSMC.BA/earnings/TSMC.BA-Q2-2026-earnings_call-649922.html
- T4https://note.com/goldriver2023/n/nf88ef36199cb?hl=en
- T4https://www.ventureatlas.org/company/tsmc
- T4https://startupfortune.com/tsmc-beat-every-earnings-record-and-wall-street-sold-the-stock-anyway/
- T4https://axis-intelligence.com/wp-content/dashboard/tsmc-statistics-dashboard.html
- T4https://invezz.com/news/2026/10/05/tsmc-hits-another-record-but-nvidia-and-apple-demand-may-become-its-next-pr…
- T4https://www.gate.com/blog/tsm-stock-2026-upside-2nm-mass-production-ai-demand-60-billion-capex-new-highs
Want a fresh look at TSM, or another name?
Queue a new deep-research run. Published to the feed when done.
Automated research opinion, published as-is on Oct 11, 2026. Not personalised advice. Figures use end-of-day closes.