Fundamentals lag the price.
Thesis
Bull case
CF franchise keeps compounding (~12% revenue CAGR 2021-25), guidance was raised, and the diversification story is real: povetacicept approval plus a clean label could re-rate the renal franchise toward the $3B peak-sales end, Journavx/Casgevy beat the $500M floor, and Q3 shows Crinetics accretion math better than feared. If estimates start revising up into 2027 ($20-21 EPS consensus), 25x on $21 supports $525+ and a multiple re-rating toward the $667 high target is plausible.
Bear case
EPS estimates are drifting down, the deal is dilutive through 2028, and the stock is 6% off highs with only ~8% sell-side upside. Povetacicept approval is largely anticipated; a narrow label, confirmatory-trial burden, or slow launch against entrenched IgAN competitors triggers sell-the-news. The $350 low target (-35%) reflects a real scenario where the diversification premium deflates and the stock re-rates as a single-franchise CF company at a lower multiple.
What would change our mind
- If Q3 shows net upward EPS revisions resuming and 2027 consensus holds ~$21 while the stock stays near $525, the bearish divergence thesis is wrong and the move has fundamental support
- A broad, clean povetacicept label with no burdensome REMS and early payer wins would invalidate the sell-the-news framing
- Journavx/Casgevy tracking materially above the $500M non-CF floor would confirm the diversification re-rate
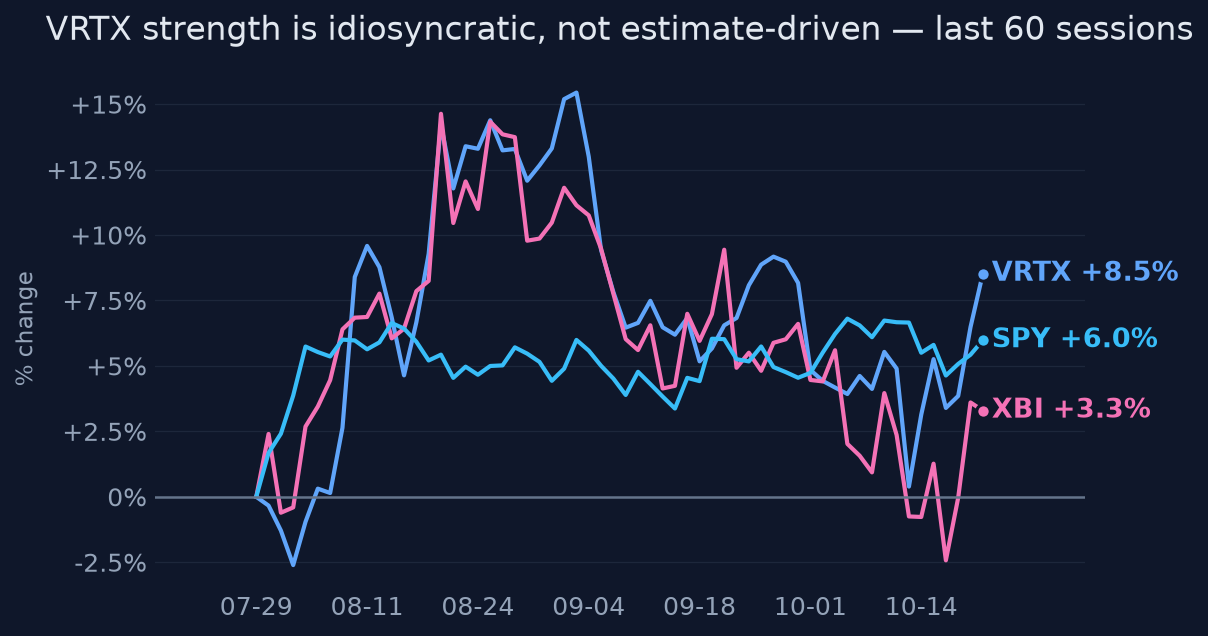
Since publication vs SPY · closed horizons are frozen
The full research everything the view rests on
Direct answer to the question asked
Where the edge would come from
What the price assumes
At ~25.5x NTM EPS and ~$535, the market prices in continued mid-to-high single-digit CF growth plus successful execution on the second wave: povetacicept approval and meaningful IgAN uptake, Journavx/Casgevy ramping past the ~$500M non-CF 2026 target, and Crinetics pipeline optionality. It does not price in a fully realized povetacicept blockbuster, but it clearly prices in approval and a credible launch.
Why the market may be wrong
Consensus may be wrong on the reaction function, not the facts: the PDUFA date, Priority Review Voucher, and positive interim RAINIER data are all public, so approval itself is a known-quantity event. In a crowded IgAN market (current branded US market only ~$600-700M with Filspari, Tarpeyo, Vanrafia, Fabhalta entrenched), a narrow label, REMS burden, or slow payer access could turn approval into a sell-the-news event. Meanwhile the Crinetics deal is dilutive to operating income through 2028, which is why EPS estimates have been drifting down even as the stock rises.
The one thing to watch
The scan rank is misleading: this is not a momentum trend with estimate support, it is a binary-ish catalyst trade wearing a momentum costume — the variable to watch is not price relative strength but whether Q3 (Nov 2) shows upward EPS revisions resuming; if estimates keep drifting down while the stock holds 6% off highs, the divergence resolves lower after the PDUFA, regardless of the approval outcome.
Key evidence (6)
- Q2 2026 revenue $3.33B, +12% y/y, beat ~$3.22B; FY26 revenue guidance raised to $13.1-13.2B [T1 SEC 8-K, Aug 3, 2026]
- 2026 EPS consensus $18.71 vs $19.09 three months ago (-2.0%); only one upward revision in last 7 days [T4 MarketWatch/Yahoo, Oct 2026]
- Povetacicept IgAN PDUFA Nov 30, 2026, with Priority Review Voucher; analyst peak sales estimates ~$1.5B-$3B; current US branded IgAN market only ~$600-700M [T3/T4]
- Crinetics closed Sep 1, 2026: $10B all-cash ($8.8B net), cash + $4.5B bridge debt; accretive to non-GAAP operating income only from 2029 [T2/T4]
- Average analyst target $572-576, median $580, low $350, zero sell ratings; ~7-8% upside from $535 [T4 aggregation, Oct 2026]
- Technicals mixed: +25% 1yr but 20d SMA signal bearish, RSI 59 neutral, 1m return z-score -0.01, vol at 1yr median; 60d SPY correlation 0.15 [quant analysis, Oct 21, 2026]
Catalysts and risks
Catalysts
- Q3 2026 earnings Nov 2, 2026 (AMC) — first full Crinetics accounting, cash/debt disclosure, Journavx trajectory
- Povetacicept FDA decision Nov 30, 2026 — label breadth, REMS, confirmatory requirements
- Q4 2026 earnings Feb 10, 2027 — 2027 guidance and povetacicept launch commentary
- Early povetacicept launch metrics and payer coverage decisions if approved
Risks
- Sell-the-news on Nov 30 approval given known PDUFA, PRV, and public interim data
- Crinetics dilution and bridge-debt interest pressuring 2027 EPS
- IgAN competition (Filspari, Vanrafia, Fabhalta, Tarpeyo) limiting uptake vs $3B peak hopes
- Journavx launch slower than implied by '1M+ cumulative Rx' marketing language
- CRL or delay on povetacicept — low probability but gap-risk large
What to watch
- 2026/2027 EPS revision direction weekly — the single most diagnostic variable
- Nov 2 Q3 print: Crinetics accretion/dilution math, post-deal cash and debt, Journavx quarterly revenue
- Nov 30 label language, REMS, and confirmatory-trial requirements
- Post-PDUFA price reaction: failure to rally on approval confirms expectations were fully priced
- Analyst target migration vs the current ~$575 mean
Market snapshot when the call was made 2026-10-21
Price
| Return 1w | +5.2% |
| Return 1m | +1.9% |
| Return 3m | +10.9% |
| Return 6m | +19.8% |
| Return 1y | +25.1% |
| From 52-week high | -6.0% |
| Realized vol, 20d | 28% |
| SPY 3m / 1y | +4.7% / +15.2% |
| QQQ 3m / 1y | +4.8% / +18.6% |
Technicals
VRTX technicals as of 2026-10-21: last close $524.52; 20d SMA 510.12 (bearish); 50d SMA 522.37; 12d EMA 508.78; 26d EMA 511.33; RSI 14 59.0 (balanced); 20d vol 27.6%; volume x1.2 vs 20d avg
Next earnings: 2027-02-10 AMC
Sources (30 · T1 = primary filings)
- T4https://finance.yahoo.com/healthcare/articles/vertex-pharmaceuticals-drugs-gaining-ground-151902515.html
- T4https://markets.financialcontent.com/stocks/quote/news?Symbol=NQ:VRTX
- T4https://tickeron.com/ticker/VRTX/
- T4https://www.trefis.com/stock/vrtx/articles/619428/why-should-you-think-about-vertex-differently-now/2026-10-20
- T4https://www.perplexity.ai/finance/VRTX
- T4https://www.stocktitan.net/overview/VRTX/
- T4https://www.marketbeat.com/stocks/NASDAQ/VRTX/news/
- T4https://www.marketbeat.com/stocks/OTCMKTS/VRTC/news/
- T1https://www.sec.gov/Archives/edgar/data/1658247/000165824726000052/crnxq226earningspr.htm
- T1https://www.sec.gov/Archives/edgar/data/875320/000119312526296710/d113650dex991.htm
- T4https://investors.vrtx.com/news-releases/news-release-details/vertex-completes-acquisition-crinetics-pharmaceu…
- T4https://investors.vrtx.com/news-releases/news-release-details/vertex-acquire-crinetics-pharmaceuticals
- T1https://www.sec.gov/Archives/edgar/data/1658247/000114036126027647/ef20077393_formdefa14a.htm
- T4https://www.otcmarkets.com/filing/html?id=19593196&guid=Yoe-k6Qfb4LXB3h
- T4https://news.vrtx.com/press-releases?mobile=1&page=11
- T4https://news.vrtx.com/news-releases/news-release-details/vertex-reports-second-quarter-2026-financial-results
- T4https://investors.vrtx.com/news-releases/news-release-details/vertex-reports-second-quarter-2026-financial-res…
- T4https://investors.vrtx.com/static-files/25a09e85-5615-46d3-8f28-7e5e75440a14
- T4https://investors.vrtx.com/news-releases/news-release-details/vertex-announces-us-fda-acceptance-biologics-lic…
- T4https://pharmaphorum.com/news/travere-undercuts-key-rival-rare-kidney-disease-igan
- T4https://www.biopharmadive.com/news/fda-approval-decisions-watch-2026/808684/
- T4https://www.marketsandstats.com/reports/iga-nephropathy-drugs-market
- T4https://www.zacks.com/stock/news/2995249/will-vertexs-kidney-disease-pipeline-be-a-new-growth-engine
- T4https://www.biopharmadive.com/news/vertex-earnings-q1-2026-povetacicept-journavx-cystic-fibrosis/819280/
- T1https://www.sec.gov/Archives/edgar/data/875320/000087532026000256/ex-991_q22026.htm
- T4https://news.vrtx.com/news-releases/news-release-details/vertex-reports-first-quarter-2026-financial-results
- T4https://www.pricetargets.com/NASDAQ/VRTX/
- T4https://www.marketbeat.com/stocks/NASDAQ/VRTX/
- T4https://stockanalysis.com/stocks/vrtx/transcripts/
- T4https://uk.finance.yahoo.com/quote/VRTX/analyst-insights/
Want a fresh look at VRTX, or another name?
Queue a new deep-research run. Published to the feed when done.
Automated research opinion, published as-is on Oct 22, 2026. Not personalised advice. Figures use end-of-day closes.