No — not yet, and earnings is the test.
Thesis
Bull case
Steel-manned bull: at $36 the market prices NKE as ex-growth, yet the FY28 consensus still implies ~30% EPS recovery, tariff refunds are legally secured and flow to cash/margin over the next year, Q1 guidance calls for gross-margin expansion to begin now, wholesale orders grew 4% with North America up 3%, and the mean sell-side target is 35% above price. A 4.5-4.7% yield pays you to wait, vol compression at the lows often resolves upward when bad news is fully priced (1-month z-score only -0.32 — no capitulation spike needed), and any confirmation on Oct 1 that estimate cuts are done could trigger a violent re-rating from 12-year-low positioning.
Bear case
Steel-manned bear: this is a classic value trap — 21x forward earnings on a business with declining revenue, margins 300bps below FY22, Nike Direct -7%, China weak, and estimates cut every month for a quarter. The stock has made lower lows for a year with no reversal signal, peers are winning (On/Hoka) while NKE underperforms even a weak DECK by 23 points over 1y, and September brought index ejection plus a BofA downgrade. The dividend consumes ~99% of trough EPS, so if FY28 slips, the yield support and the equity story crack together; 'turnaround unlikely before 2027' (September coverage) means 3-6 month holders are early at best.
What would change our mind
- If Oct 1 results show FY27 estimates stabilizing or rising (first positive revision in 4+ months) with gross-margin expansion confirmed, the no-buy stance is invalidated — that would be the entry signal
- If the stock breaks above the 50d SMA (~$39.50) on earnings volume with estimates intact, the technical bearish-trend premise fails
- If FY28 consensus EPS falls below ~$1.90 or management pushes the recovery past FY28, the recovery-and-yield bull case is invalidated at any price
- If the dividend is cut or buybacks are suspended to preserve cash, the yield-support leg of the thesis is invalidated
Since publication vs SPY · closed horizons are frozen
The full research everything the view rests on
Direct answer to the question asked
Where the edge would come from
What the price assumes
The market prices NKE as a no-growth, ex-growth-index casualty: consensus Hold with a ~$49 average target (+35%) but negative drift (JPMorgan Underweight $40, RBC Sector Perform $50, September BofA downgrade), removal from the S&P 100, and Dow-seat jeopardy (Reuters, Sep 17). Consensus still embeds a meaningful FY28 recovery ($2.11-2.17 EPS vs $1.66 in FY27), so even the depressed price assumes the turnaround eventually works.
Why the market may be wrong
Bearish consensus could be wrong if the IEEPA tariff refunds (Supreme Court ruling Feb 2026; refunds ordered, slow/contested) convert into real cash and margin faster than expected, if guided Q1 gross-margin expansion signals the margin trough is in, and if wholesale (+4%) and North America (+3%) momentum broadens — a FY28 EPS recovery to $2.11+ at even an 18-20x multiple implies $38-43 plus a 4.5% yield while you wait. Conversely, bullish sell-side targets could be wrong because estimates have been cut for 90 straight days and the stock has made lower lows the entire time — the 'cheap' 21x multiple is on numbers that keep shrinking.
The one thing to watch
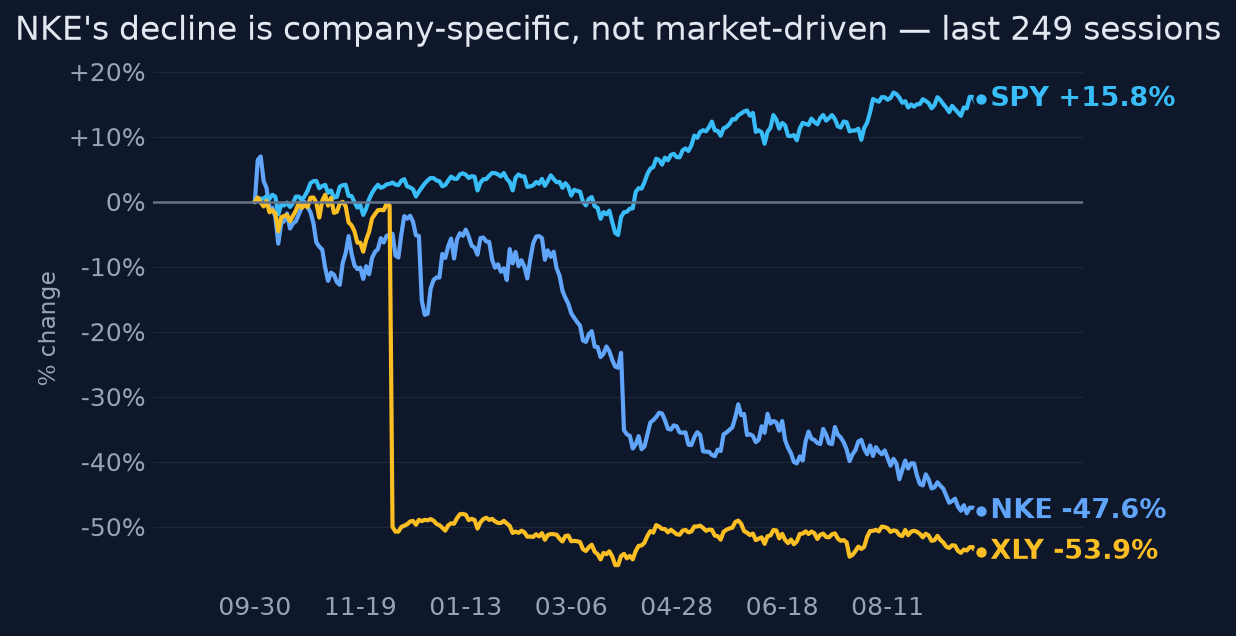
The ~4.5% dividend yield is not independent downside protection — at a ~99% payout of trough FY27 EPS, the yield and the recovery thesis are the same bet: if the FY28 EPS rebound to ~$2.11 slips, the dividend becomes contested and the 'yield floor' under the stock disappears. So the single variable to watch is not price or RSI but whether FY28 estimates stop falling after Oct 1; the decline is ~97% idiosyncratic (60d correlation to SPY just 0.16), so no market rally will rescue it — only company-specific estimate stabilization will.
Key evidence (11)
- FY2026 10-K [T1 SEC]: $9.0B cash + short-term investments vs ~$11.0B total debt; inventory $7.5B; ~$2.4B dividends vs only ~$122M buybacks
- SEC XBRL: revenue $51.4B (FY24) -> $46.3B (FY25) -> $46.4B (FY26); diluted EPS $3.73 -> $2.16 -> $2.10; gross margin ~42.9% vs 46.0% in FY22
- Q4 FY26 (reported Jun 30, 2026, company release): revenue -1% reported / -4% currency-neutral; reported EPS $0.72 included a $0.52 one-time IEEPA tariff-recovery benefit; gross margin 49.2% flattered by ~900bps from the same item
- Guidance: low-to-mid single-digit revenue declines for the next three quarters; gross-margin expansion expected to begin Q1 FY27
- Consensus [T4 Yahoo/Zacks, Sep 2026]: FY27 ~$45.4B / $1.66-1.67 EPS, cut from $1.82 ninety days earlier; FY28 ~$2.11-2.17, cut from $2.40 — revisions still negative
- Technicals (Sep 28-29, 2026): $36.39 close, 0.7% above 52-week low, below 20d SMA $36.94 and 50d SMA $39.53; RSI-14 36; 20d realized vol at 8th percentile of trailing year; 1y return -49% vs SPY +17%
- Quant: 60d correlation to SPY 0.16, idiosyncratic share ~97% — the decline is company-specific, not beta
- Reuters (Sep 17, 2026) [T2]: falling share price puts Dow seat in jeopardy; removed from S&P 100 in quarterly rebalance
- Supreme Court Feb 20, 2026 ruling struck down IEEPA tariffs [T1 CRS]; refunds ordered but slow and contested — a genuine but timing-uncertain tailwind
- Dividend $0.41/quarter (declared Jun 8, 2026) = ~4.5-4.7% yield at current price vs ~$1.66 FY27 consensus EPS = ~99% payout
- Q1 FY27 earnings scheduled Oct 1, 2026 (company announcement Aug 28, 2026); next report after that Dec 16, 2026
Catalysts and risks
Catalysts
- Q1 FY27 earnings Oct 1, 2026 — guided gross-margin expansion, China trajectory, tariff-refund commentary
- Q2 FY27 earnings Dec 16, 2026 (consensus $0.53 EPS / ~$11.96B revenue)
- IEEPA tariff refund processing pace and amounts (court/CBP proceedings ongoing)
- Further analyst rating/target revisions following the September downgrade wave
- Potential index decisions on Dow composition if share price stays depressed
- Any change to the dividend given ~99% payout of FY27 EPS
Risks
- Binary earnings event two days away — vol compression (8th percentile) implies a large move is coming, direction unknown
- Estimates still falling: FY27 EPS consensus cut from $1.82 to $1.66 in 90 days; another cut cycle post-earnings breaks the 21x 'cheap' framing
- Dividend sustainability if FY28 recovery slips — payout ~99% of trough EPS
- China demand and Nike Direct (-7% in Q4) deterioration
- Tariff-refund timing/quantum uncertainty; benefits may be smaller or later than hoped
- Index-removal overhang (S&P 100 done, Dow seat in question) creating mechanical selling pressure
- Competitive share loss to On, Hoka/Deckers, Adidas persisting beyond the turnaround window
What to watch
- FY27/FY28 EPS estimate revisions in the 2 weeks after Oct 1 — direction of revisions matters more than the print itself
- Gross margin ex-tariff-recovery items (Q4's 49.2% included ~900bps one-time benefit; underlying trend is what counts)
- China and Nike Direct revenue trends vs North America/wholesale strength
- Cash received from IEEPA tariff refunds (amount and timing in 10-Q cash-flow statement)
- Inventory trajectory vs the $7.5B FY26 level
- Price/volume reaction at the 52-week low: a high-volume reversal off $35-36 with estimate stabilization is the confirmed entry; a breakdown on volume after earnings confirms the value-trap read
- Dividend declarations for any signal of payout stress
Market snapshot when the call was made 2026-09-28
Price
| Return 1w | +0.7% |
| Return 1m | -7.4% |
| Return 3m | -12.3% |
| Return 6m | -30.7% |
| Return 1y | -48.7% |
| From 52-week high | -51.0% |
| Realized vol, 20d | 24.2% |
| SPY 3m / 1y | +5.8% / +16.7% |
| QQQ 3m / 1y | +1.7% / +24.1% |
Technicals
NKE technicals as of 2026-09-28: last close $36.39; 20d SMA 36.94 (bearish); 50d SMA 39.53; 12d EMA 36.41; 26d EMA 37.48; RSI 14 36.2 (balanced); 20d vol 21.9%; volume x1.1 vs 20d avg
Next earnings: 2026-12-16
Verifier notes PASS
Weakly sourced
- '12-year lows' (thesis, bear_case): the only support is T4 investing.com coverage ('trading near 12-year lows'); no primary price-history data in the bundle confirms the exact lookback. The core technical claims (51% below 52w high, -49% 1y, 0.7% above 52w low) are fully evidenced, so this is not decision-changing, but the precise '12-year' framing rests on a single T4 source.
- 'Estimates have been cut for 90 straight days' (why_market_may_be_wrong): the evidence shows negative revisions over a 90-day window ($1.82→$1.67, $2.40→$2.11, T4 Yahoo), not literally daily cuts. Minor rhetorical overstatement of an otherwise supported trend.
Sources (24 · T1 = primary filings)
- T4https://about.nike.com/en/newsroom/releases/nike-inc-reports-fiscal-2026-fourth-quarter-and-full-year-results
- T4https://companiesmarketcap.com/nike/sec-reports-10k/0000320187-26-000088/
- T1https://www.sec.gov/Archives/edgar/data/320187/000032018726000088/nke-20260531.htm
- T4https://www.zacks.com/stock/news/2946521/nike-q4-earnings-beat-estimates-north-america-revenues-up-3
- T4https://news.futunn.com/en/notice/307722709/nike-10-k-fy2026-annual-report
- T4https://www.stocktitan.net/sec-filings/NKE/8-k-nike-inc-reports-material-event-217c938e5679.html
- T2https://www.wsj.com/market-data/quotes/NKE/financials/annual/balance-sheet
- T4https://247wallst.com/investing/2026/09/18/nike-is-no-longer-a-growth-story-is-it-a-dividend-story-yet/
- T4https://dart.deloitte.com/USDART/home/publications/deloitte/heads-up/2026/supreme-court-tariff-ruling-accounti…
- T1https://www.congress.gov/crs-product/LSB11398
- T4https://www.foley.com/insights/publications/2026/06/what-every-multinational-should-know-about-the-governments…
- T4https://www.pwc.com/us/en/services/tax/library/pwc-cit-issues-order-related-to-ieepa-duty-refunds.html
- T4https://www.kq2.com/stacker-international/2026/09/22/months-after-ieepa-tariffs-were-struck-down-some-refunds-…
- T4https://www.pwc.com/ca/en/services/tax/publications/tax-insights/us-court-ieepa-tariff-refunds-2026.html
- T4https://www.sidley.com/en/insights/newsupdates/2026/04/ieepa-tariff-refund-claims-key-considerations-for-lende…
- T4https://www.foley.com/insights/publications/2026/03/what-every-multinational-should-know-aboutmanaging-the-aft…
- T2https://www.reuters.com/business/media-telecom/nikes-falling-share-price-puts-its-dow-seat-jeopardy-2026-09-17…
- T2https://www.reuters.com/sustainability/cop/nike-shareholders-reject-climate-proposal-backed-by-norway-wealth-f…
- T2https://www.reuters.com/company/nike-inc/
- T2https://www.reuters.com/markets/companies/NKE.N/
- T4https://www.investing.com/news/stock-market-news/nike-stock-takes-another-beating-after-bofa-downgrade-can-nke…
- T4https://uk.investing.com/news/stock-market-news/nike-stock-outlook-trading-at-12year-lows-with-turnaround-unli…
- T4https://fortune.com/2026/09/08/nike-stock-plummets-sp500-market-cap-index/
- T4https://uk.investing.com/news/stock-market-news/nike-stock-takes-another-beating-after-bofa-downgrade-can-nke-…
Earlier and later calls on NKE
- Oct 14, 2026Value trap — for now.Lean bearishview changed
Want a fresh look at NKE, or another name?
Queue a new deep-research run. Published to the feed when done.
Automated research opinion, published as-is on Sep 29, 2026. Not personalised advice. Figures use end-of-day closes.