Cheap-ish, but no edge yet.
Thesis
Bull case
Stock is 26% below its 52-week high at ~18.5x forward earnings — the low end of its 17.7-21.2x recent range — on what may be trough EPS, with a ~3% yield providing carry. The SRS/GMS pro-distribution platform ($18.3B + $5.5B) diversifies away from DIY softness, and any sustained mortgage-rate decline would unlock years of deferred big-ticket renovation demand; repair/maintenance demand and aging housing stock provide a floor. If housing turns, operating leverage on a 33% gross margin base is substantial and consensus targets imply +29%.
Bear case
Earnings have declined for three consecutive years, FY26 EPS growth is guided to flat-to-+4% only because of ~$730M in non-recurring tariff refunds, and near-term revisions are sharply negative. Mortgage rates are rising, not falling; both major retailers describe a frozen housing market with consumers deferring big-ticket projects indefinitely. Net interest expense of ~$2.3B/yr (debt-funded SRS/GMS) caps EPS recovery, FY27 consensus growth is unearned, and the Nov 17 print risks exposing refund-flattered margins — a 'cheap on depressed earnings' stock that is actually fairly valued on normalized (lower) earnings.
What would change our mind
- If Q3 (Nov 17) shows US comps accelerating above ~+2% with gross margin ≥33.1% held WITHOUT refund support, the bear/quality thesis is wrong — buy the inflection
- If 30-year mortgages fall sustainably below ~6.5% and existing-home sales inflect up, the cyclical-recovery thesis activates
- If FY27 consensus EPS holds ~$15.02 through the Nov print, downside is cushioned and LEAN_BEARISH should be upgraded to LEAN_BULLISH on valuation
Since publication vs SPY · closed horizons are frozen
The full research everything the view rests on
Direct answer to the question asked
Where the edge would come from
What the price assumes
Consensus implies ~+29% upside (avg target $375.93) and embeds FY27 EPS of ~$15.02 (+~5% growth) and FY28 ~$15.99, i.e., the price is expected to recover on a housing inflection despite no visible evidence of one. The low target ($310) is barely above the current price, suggesting targets are stale and anchored to a recovery narrative.
Why the market may be wrong
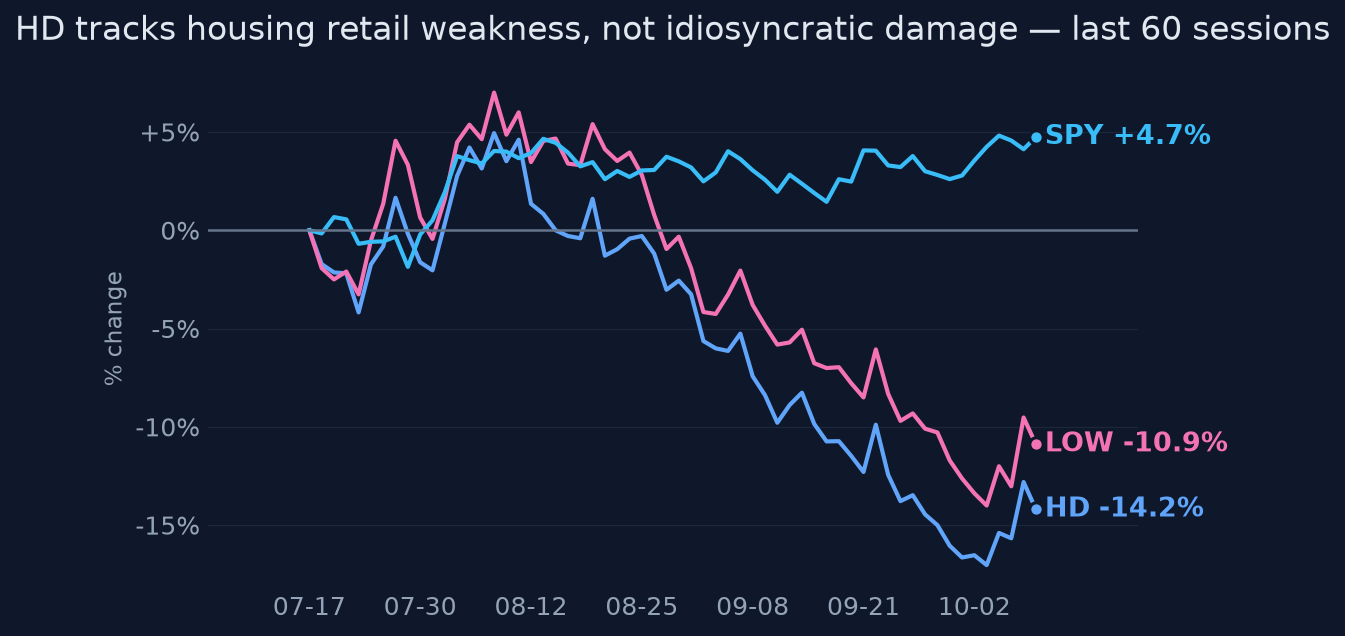
FY27 growth is being extrapolated from a sector that both HD and LOW describe as 'frozen,' with 30-year mortgages re-accelerating to 7.40% (Oct 8, 2026). The Q2 'beat' included ~$685M of COGS relief from IEEPA refunds, so underlying EPS power is overstated, and current-quarter revisions ran 28 down vs 1 up in 30 days. Sell-side targets have not yet reset to this weaker near-term reality.
The one thing to watch
The single variable that matters is not comps or guidance — it's whether Q3 (Nov 17) shows underlying gross margin holding AFTER lapping the ~$730M IEEPA tariff-refund benefit. If adjusted EPS misses because the refund cushion is gone, the 'cheap at 18.5x trough EPS' framing collapses because $14-15 EPS itself was refund-assisted; the real trough EPS may be lower.
Key evidence (8)
- Diluted EPS declined FY22-FY25: $16.69 → $14.23; operating margin 15.3% → 12.7% [T1 SEC XBRL]
- Q2 FY26 (Aug 18, 2026): sales +5.7%, US comps +1.3%, adj EPS $4.92 beat, but included ~$730M IEEPA tariff refunds (~$685M COGS relief); guidance merely reaffirmed [T1 IR release/transcript; T2 Reuters]
- Q1 FY26 US comps only +0.4%; FY26 guidance EPS growth flat to +4% [T1]
- Current-quarter revisions: 28 down vs 1 up in 30 days; Zacks cut Q3 to $3.87 from $3.95 [T4 Yahoo/MarketBeat — noted as lower-tier sourcing]
- 30-yr mortgage 7.40% week of Oct 8, 2026, up from 7.03% two weeks prior [Freddie Mac PMMS]
- Lowe's cut FY26 outlook to bottom of range (Aug 19, 2026) [T2 Reuters]; HD-LOW 60d correlation 0.92
- Dividend raised only 1.3% in Feb 2026 ($2.33/qtr) — a cautious management signal; yield ~3%
- Consensus Moderate Buy, avg target $375.93, range $310-$425; Melius Buy $397 (Oct 6, 2026) [T3/T4]
Catalysts and risks
Catalysts
- Q3 FY26 earnings Nov 17, 2026 — tariff-refund lap effect, comps trend, any guidance change
- September existing-home sales (Oct 13, 2026) and monthly housing turnover data
- FOMC meetings and 10-year Treasury/term premium trajectory driving mortgage rates
- Potential further analyst target resets if Nov print disappoints
- Any SRS/GMS segment disclosure quantifying pro-platform growth
Risks
- Tariff-refund benefit laps, exposing weaker underlying margins
- Mortgage rates stay elevated or rise further, keeping housing frozen through 2027
- FY27 consensus EPS cuts of 5-10% would make the stock not actually cheap
- Further tariff/input-cost escalation beyond refund offsets
- SRS/GMS integration underperformance or pro-market slowdown removing the key bull offset
What to watch
- Q3 gross margin ex-tariff-refund effects (the key earnings-quality tell)
- Weekly Freddie Mac PMMS — direction of 7.4% mortgage rate
- Revision trend into Nov 17: does 28-down/1-up persist or stabilize
- US comps vs LOW's — any break of the 0.92 correlation would signal idiosyncratic share gains
- Buyback resumption/disclosure as a capital-return signal
Market snapshot when the call was made 2026-10-09
Price
| Return 1w | +2.8% |
| Return 1m | -4.9% |
| Return 3m | -13.8% |
| Return 6m | -13.8% |
| Return 1y | -24.2% |
| From 52-week high | -25.8% |
| Realized vol, 20d | 24.2% |
| SPY 3m / 1y | +3.9% / +15.7% |
| QQQ 3m / 1y | +5.5% / +22.9% |
Technicals
HD technicals as of 2026-10-09: last close $290.74; 20d SMA 293.68 (bearish); 50d SMA 317.68; 12d EMA 290.40; 26d EMA 298.72; RSI 14 44.2 (balanced); 20d vol 24.0%; volume x0.9 vs 20d avg
Sources (23 · T1 = primary filings)
- T1https://ir.homedepot.com/~/media/Files/H/HomeDepot-IR/press-release/q2-2026-earnings-release.pdf
- T2https://www.reuters.com/business/retail-consumer/home-depot-beats-quarterly-sales-estimates-steady-repair-dema…
- T4https://www.marketbeat.com/articles/home-depot-and-lowes-hit-52-week-lowsbut-analysts-arent-giving-up/
- T1https://ir.homedepot.com/~/media/Files/H/HomeDepot-IR/2026/hd-2q26-transcript.pdf
- T1https://ir.homedepot.com/news-releases/2026/08-18-2026-110040463
- T1https://ir.homedepot.com/financial-reports/quarterly-earnings/2026
- T1https://www.sec.gov/Archives/edgar/data/354950/000035495026000101/hd_exhibit991x05032026.htm
- T4https://simplywall.st/stocks/cl/retail/snse-hd/home-depot-shares
- T4https://www.nar.realtor/research-and-statistics/housing-statistics/existing-home-sales
- T4https://freddiemac.gcs-web.com/news-releases/news-release-details/mortgage-rates-average-728
- T4https://www.freddiemac.com/pmms
- T4https://freddiemac.gcs-web.com/node/32111/pdf
- T3https://www.cnbc.com/2026/08/19/lowes-low-q2-2026-earnings.html
- T2https://www.reuters.com/business/lowes-cuts-annual-sales-growth-forecast-consumers-curb-high-cost-renovations-…
- T4https://www.freddiemac.com/pmms/archive
- T4https://stocklight.com/stocks/us/nyse-hd/the-home-depot/annual-reports/nyse-hd-2026-10K-26769447.pdf
- T3https://www.cnbc.com/investingclub/2026/10/06/a-new-analyst-call-on-home-depot-reflects-our-feeling-on-what-to…
- T1https://ir.homedepot.com/~/media/Files/H/HomeDepot-IR/2026/The%20Home%20Depot%20Inc%20-%202026%20Proxy%20State…
- T4https://www.pricetargets.com/NYSE/HD/
- T1https://www.sec.gov/Archives/edgar/data/1600438/000110465925064147/tm2519400d3_ex99-2.htm
- T4https://www.wisesheets.io/pe-ratio/HD
- T4https://finance.yahoo.com/markets/stocks/articles/home-depot-stock-down-17-124700120.html
- T4https://www.marketbeat.com/stocks/NYSE/HD/
Want a fresh look at HD, or another name?
Queue a new deep-research run. Published to the feed when done.
Automated research opinion, published as-is on Oct 11, 2026. Not personalised advice. Figures use end-of-day closes.