Neither distressed entry nor trap — fairly de-rated.
Thesis
Bull case
The de-rating is done: price -65%, TVL -50%, memecoin premium fully unwound, yet Solana kept #1 DEX-volume share and fees/revenue are now inflecting positive (+7.5%/+15.5% 30d). Alpenglow's 150ms finality is a genuine technical lead being sold on the news; Firedancer remains unpriced upside. Vol at the 18th percentile with price +15% above the 200d sets up for a squeeze if the crypto regime turns — and with beta 1.38, any BTC recovery lifts SOL disproportionately. ETF outflows are small in absolute terms vs $1.7B AUM.
Bear case
Even after -65%, SOL is expensive on fundamentals: 0.53% fee yield, ~1,670x FDV/revenue, 10.4x mcap/TVL, uncapped ~3.6-3.8% inflation, and post-SIMD-0096 value accrual flows to validators not holders. The memecoin fee engine is gone and fee share keeps falling to Ethereum, Base and Hyperliquid; Ethereum holds ~78% of DeFi lending vs Solana's ~5.4%. The 'institutional bid' was overstated by seed capital and has now reversed; October relative strength flipped -9pp vs BTC. In a risk-off crypto regime (BTC -28% 1y), a 1.38-beta asset with no cash-flow floor has further to fall if BTC rolls over.
What would change our mind
- Bullish-tilt invalidation: Solana fee share of cross-chain fees falls below ~15% while TVL breaks below ~$5B — confirms value-capture deterioration, not just beta
- Bearish-tilt invalidation: 30d fees sustain >20% growth for two consecutive months AND ETF flows resume net inflows — signals genuine activity recovery
- Decisive break of the 52w low (~$62) on rising volume invalidates the 'de-rating complete' framing
- SOL/BTC ratio making new 1y lows would confirm idiosyncratic deterioration rather than beta
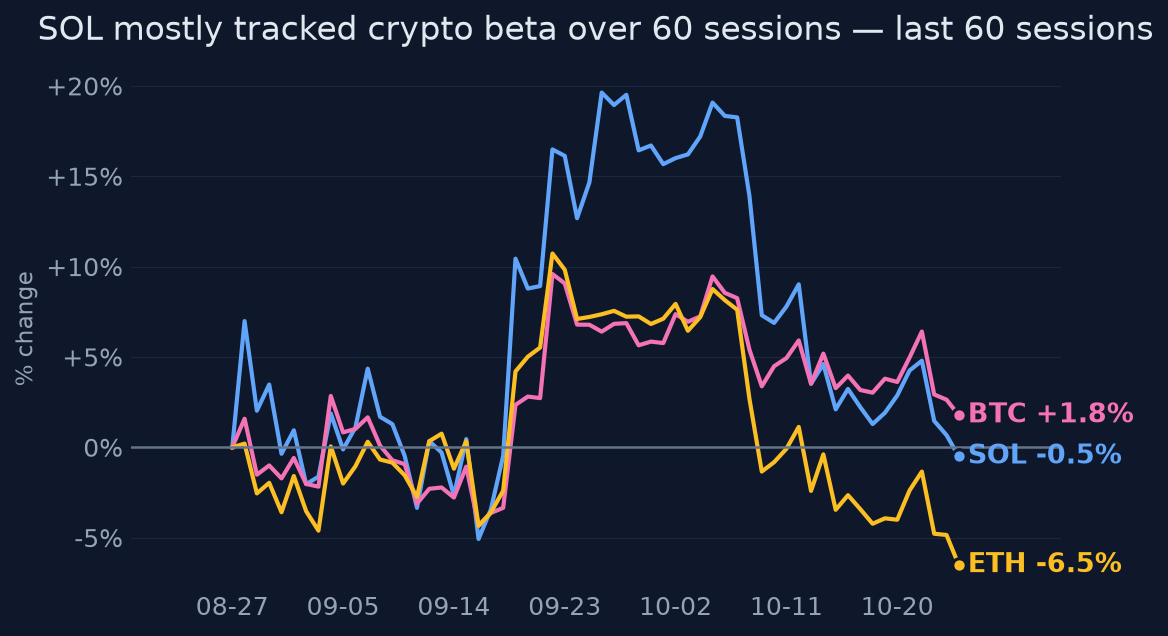
Since publication vs BTC · closed horizons are frozen
No price data after the entry date yet.
The full research everything the view rests on
Direct answer to the question asked
Where the edge would come from
What the price assumes
The market prices SOL as a high-beta BTC proxy with optionality on a Solana-activity recovery: ~$60B mcap vs $237M annual fees assumes a meaningful rebound in on-chain activity, not current run-rate. The October price action (-13% 1m, ETF outflows) suggests the market is actively repricing downward the probability of that recovery happening in the next two quarters.
Why the market may be wrong
Two-sided. Bears may be wrong because volume leadership persisted (~30-36% cross-chain spot DEX share, seventh consecutive quarter per Galaxy [T3]) and fees are inflecting up (+7.5% 30d, revenue +15.5%) while the Alpenglow milestone (150ms finality, live Oct 21) is a real technical differentiator being sold on the news. Bulls may be wrong because ~$449M of the ETF 'institutional bid' was launch seed capital [T4], so organic demand is much thinner than the $1.58B cumulative headline, and SOL's structural value-accrual problem (uncapped ~3.6-3.8% inflation, post-SIMD-0096 burns reduced to 50% base fee only) means even a usage recovery accrues mostly to validators, not holders.
The one thing to watch
The variable to watch is not Solana's price or TVL — it is the fee-share divergence: Solana holds #1 spot-DEX volume share (~30-36%) but its network-fee share collapsed from 26.6% to 17.3% in one quarter (Galaxy [T3]). That gap quantifies the memecoin-era problem: throughput dominance without economic capture. The thesis resolves when fee share, not volume share, inflects — and since SIMD-0096 routed priority fees to validators, even that inflection wouldn't accrue to the token. Watch Solana's fee share of cross-chain fees as the single discriminator.
Key evidence (9)
- DefiLlama: TVL $5.74B, -49.9% 1y, -56.6% below ATH (2026-10-25) [T3]
- DefiLlama: 30d fees $25.9M (+7.5% vs prior 30d); 1y fees $237M; annualized fees = 0.53% of mcap; FDV/annualized revenue ~1,670x [T3]
- Quant: 60d beta to BTC 1.38, correlation 0.83; ETH corr 0.87; idiosyncratic share only 25-31%; 20d vol at 18th percentile of trailing year (2026-10-25)
- Galaxy [T3]: Solana spot-DEX volume share ~30-36% (Q2/Q3 2026, #1 for 7th straight quarter) but fee share fell 26.6% (Q1) -> 17.3% (Q2 2026); Q2 DEX volume -45% QoQ
- ETF flows [T3/T4]: cumulative ~$1.58B inflows / $1.71B AUM (Oct 13) but ~$449M was seed capital; 14-week inflow streak ended Oct 5-9 with -$25M, all five sessions negative, mostly BSOL
- Alpenglow consensus upgrade activated mainnet epoch 1064, Oct 21 2026, ~150ms finality vs 12.8s (solana.com/CoinDesk [T2/T4]) — landed during the selloff
- Tokenomics [T4, secondary]: uncapped supply, ~3.6-3.8% current inflation, SIMD-0096 moved 100% of priority fees to validators, leaving only 50% base-fee burn; 92.7% of total supply circulating
- Macro [T4 directional]: BTC -28% 1y vs QQQ +16%; BTC ETFs swung +$1.075B (Oct 19-21) to -$773M (Oct 22-23) — unstable institutional bid
- Technicals: below 20d/50d SMA, +15% above 200d, RSI 37, +63% off 52w low
Catalysts and risks
Catalysts
- Firedancer mainnet rollout progress (status currently unverified — any confirmed deployment % is a repricing event)
- SOL ETF flow direction resumption or continuation of outflows (weekly Farside/CoinMarketCap data)
- Post-Alpenglow latency-driven application launches and whether fee share recovers vs volume share
- Monthly unlock lots (~0.1% supply each, Nov-Jan, unverified [T4])
- Macro regime shift: Fed policy / liquidity conditions driving the entire crypto complex
- Any revival of consumer/memecoin cycle restoring Solana's high-fee activity
Risks
- Beta risk dominates: BTC continuation of -28% 1y trend mechanically drags SOL at 1.38x
- Structural dilution: ~3.6-3.8% inflation with minimal burn compounds against non-staked holders
- Fee-share erosion to Ethereum/Base/Hyperliquid accelerates
- ETF outflow streak extends, removing the marginal buyer narrative
- Unlock/unverified supply data could be worse than reported ([T4] sources only)
What to watch
- Solana's share of cross-chain network fees (Galaxy/DefiLlama) — the single discriminator between volume leadership and value capture
- Weekly SOL ETF flows: whether the Oct 5-9 outflow streak was a blip or regime change
- Firedancer validator deployment % (official Anza/Jump sources only)
- 30d fee trend vs prior 30d (currently +7.5%) — does the stabilization hold
- BTC trend: with corr 0.83 and beta 1.38, BTC direction decides most of SOL's path
- SOL/BTC relative strength: the -9pp 1m flip vs +9pp 3m — which wins
Market snapshot when the call was made 2026-10-25
Price
| Return 1w | -1.8% |
| Return 1m | -13.2% |
| Return 3m | +36.3% |
| Return 6m | +17.8% |
| Return 1y | -47.5% |
| From 52-week high | -49.2% |
| Realized vol, 20d | 41.2% |
| BTC 3m / 1y | +25.0% / -27.6% |
| ETH 3m / 1y | +25.0% / -40.5% |
| QQQ 3m / 1y | +3.3% / +16.3% |
Technicals
Sources (24 · T1 = primary filings)
- T4https://solana.com/upgrades/alpenglow
- T4https://solana.com/pl/upgrades
- T4https://solana.com/uk/alpenglow
- T4https://x.com/solana/status/2112906742585512150
- T4https://solanacompass.com/news/us-spot-solana-etfs-shed-about-25m-in-a-week-as-outflows-hit-all-five-sessions
- T4https://solanacompass.com/news/all-six-us-solana-etfs-recorded-zero-net-flows-for-five-consecutive-sessions
- T4https://solanacompass.com/news/us-spot-solana-etfs-hit-122-billion-cumulative-inflow-record-after-years-bigges…
- T2https://www.coindesk.com/tech/2026/10/22/solana-completes-alpenglow-upgrade-here-s-what-it-means-for-users
- T4https://coinhubnetwork.com/chain-fees-and-activity-snapshot-2026-09/
- T4https://www.insidedeeptech.com/defi-industry-report-q3-2026/
- T4https://solanacompass.com/projects/defillama
- T4https://blockonomi.com/dex-statistics-2026-volume-market-share-and-perp-data/
- T3https://www.galaxy.com/insights/research/solana-q1-2026-dex-rwa-stablecoins-market-share
- T3https://www.galaxy.com/insights/research/solana-q2-2026-report-tokenized-economy-dex-rwa-stablecoins
- T4https://x.com/Blockworks/article/2110732492671942964
- T4https://eco.com/support/en/articles/11827084-best-dexs-in-2026-fees-volume-ranked
- T4https://crypto.news/bitcoin-etfs-reversed-course-in-a-day-who-is-buying-when-the-funds-sell/
- T4https://econotimes.com/Bitcoin-BTC-ETFs-Take-In-526-7-Million-October-Price-Loss-Nears-2-1757433
- T4https://coinpaper.com/37763/bitcoin-et-fs-bleed-636-million-ethereum-funds-lose-another-111-million
- T4https://x.com/FarsideUK/status/2113839581179056261
- T4https://econotimes.com/U-S-Bitcoin-ETFs-Draw-526-7-Million-as-Spot-Sellers-Persist-1757689
- T4https://cointelegraph.com/markets/bitcoin-etfs-528-million-btc-tops-84k
- T4https://x.com/FarsideUK/status/2108046265413988766/photo/1
- T4https://x.com/CryptoXLounge/status/2113856591820734474
Earlier and later calls on SOL
- Oct 16, 2026Real activity, weak token capture.No clear edge
Want a fresh look at SOL, or another name?
Queue a new deep-research run. Published to the feed when done.
Automated research opinion, published as-is on Oct 25, 2026. Not personalised advice. Figures use end-of-day closes.