Great company, bad entry price.
Thesis
Bull case
The strongest bull case is that Palantir is in a genuine demand supercycle where estimates chase reality upward: FY26 guidance has been raised 13.5% cumulatively in six months, US commercial grew 149%, NDR 128% and doubling RDV signal durable forward demand, and the FY27 consensus of +49% may prove as conservative as FY26's initial guide did. Defense AI budgets (Maven ramp, $1.5T FY27 request) and sovereign AI adoption provide a multi-year funded runway few software companies have. If FY27 estimates get revised toward $2.75-3.00 EPS and the market merely holds a ~100x multiple on that, the stock reaches $275-300. GAAP profitability at 31-47% operating margins with $9.2B cash also means this is not a cash-burning story stock — it can grow into its multiple faster than skeptics model.
Bear case
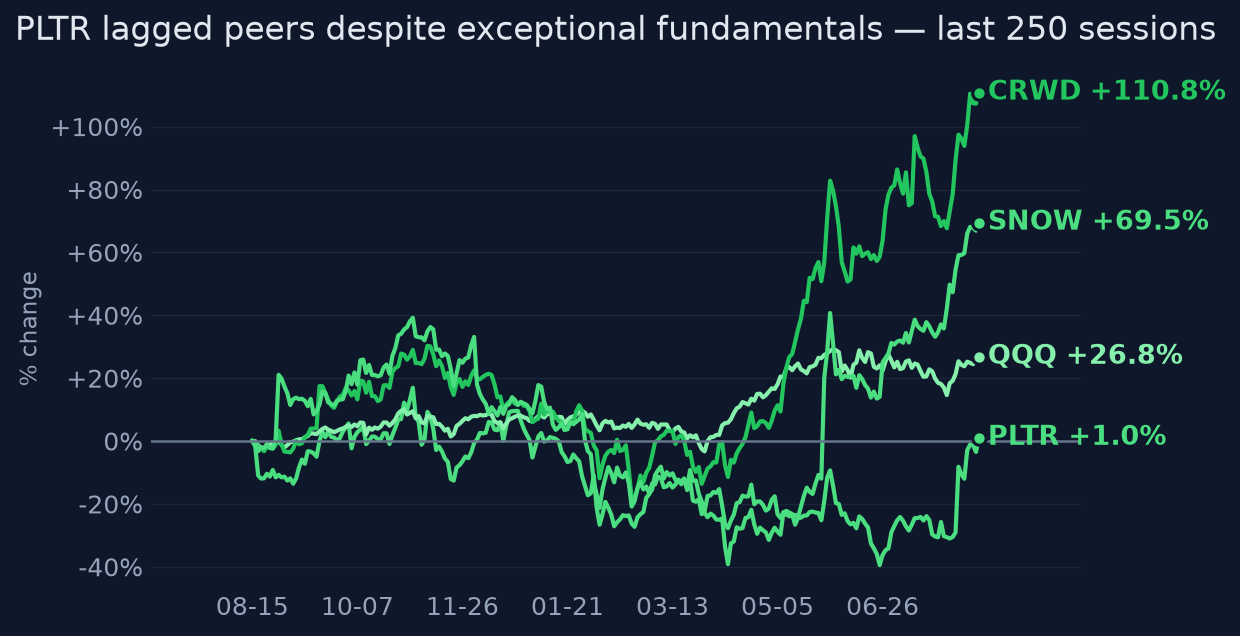
The strongest bear case is arithmetic, not narrative: at 50x sales and ~112x forward consensus earnings, growth is already decelerating (93% Q2 print -> 82% FY26 guide -> ~49% FY27 consensus), and the market cut this stock ~48% from its Nov 2025 record within the past year with no fundamental deterioration, on top of repeated 8-13% post-earnings valuation selloffs (May 2025; Q1 2026). One-year holders are down 4% while owning the fastest-growing large-cap software story on earth — the multiple is eating the fundamentals. The 55% Q2 net margin flattered true operating leverage (~47% op margin, boosted by interest income). International growth lags badly (total +93% vs US +115%), insider selling continues, and the entry point is the most overbought condition of the year (RSI 79, +34% in a month, ~110% realized vol). If AI-software sentiment rolls over — C3.ai is down 40% in a year showing what disappointment does — PLTR's beta (1.56) and multiple make it the highest-beta expression of that trade.
What would change our mind
- If Q3 2026 delivers a fourth consecutive guidance raise AND the stock holds above ~$180 through year-end, the multiple-compression regime may be ending — the bearish 'multiple eats fundamentals' thesis would be invalidated
- If FY27 consensus revenue estimates are revised above ~$13B (>55% growth) without the stock re-rating, the 'growth already priced' claim weakens
- Bull-case invalidation (downside-confirmation trigger): any quarter where US commercial growth falls below ~80% or NDR drops materially below 128% would signal the supercycle is normalizing faster than priced
- If the stock breaks decisively below ~$135-145 (50d/20d SMA zone) on no fundamental news, it confirms sentiment-driven compression is reasserting
Since publication vs SPY · closed horizons are frozen
The full research everything the view rests on
Direct answer to the question asked
Where the edge would come from
What the price assumes
The current price assumes FY27 consensus (~$12.2B revenue, ~+49% growth, $2.31 EPS) is at least achievable and that a 77x FY27 P/E multiple holds. It also implicitly assumes no repeat of the Nov 2025 -> mid-2026 compression episode, i.e., that the market now tolerates 50x sales for a decelerating (82% -> ~49%) grower. Consensus targets only 7-16% above spot after the melt-up suggest the Street itself does not see meaningful re-rating from here.
Why the market may be wrong
Both directions are plausible. Bears may be wrong because Palantir has beaten and raised every quarter in this window, FY27 consensus may still be conservative given the raise pattern (Feb $7.2B -> Aug $8.15B for FY26 alone), and Maven/DoD AI budget ramps ($240M FY26 -> >$2B proposed FY27) plus sovereign AI demand could extend the supercycle. Bulls may be wrong because the market has already demonstrated — a -48% peak-to-trough collapse from the Nov 2025 record plus repeated 8-13% post-earnings selloffs (May 2025; Q1 2026) — that it will cut this multiple sharply with no fundamental deterioration at all, and Q2's +93% is the peak rate: guidance implies deceleration is already underway.
The one thing to watch
The variable to watch is not Palantir's growth rate — it's the compression ratio: the forward P/E compressed ~44% over two years (~25%/yr, from 267x to 204x to 149x per a single T3/T4 MarketWatch analyst-estimate snapshot) *while* the company beat and raised continuously, meaning the stock only rises when earnings growth outruns multiple decay by a wide margin. At a triple-digit forward multiple with growth mathematically decelerating from 93% toward ~49%, the hurdle for stock appreciation is actually rising even as the business performs. Falsifiable version: if FY27 EPS estimates hold at ~$2.31 while the stock stalls below the ~$207 record through year-end, the market is confirming that ~150x was the ceiling, and the fair multiple anchor is lower.
Key evidence (9)
- FY2025 (SEC XBRL, T1): revenue $4.48B (+56%), GAAP net income $1.63B, operating margin 31.6%
- Q2 2026 (Aug 3, 2026, company PR T1 / CNBC T3): revenue $1.94B (+93% YoY) vs $1.81B est.; adj EPS $0.41 vs $0.34 est.; US commercial +149%, US gov +90%; customers 711 (+20%); NDR ~128%; RDV ~$8.7B (~2x YoY); ~$9.2B cash
- Guidance raised 3x in 2026 (T1/Reuters T2): $7.18-7.20B (Feb) -> $7.65-7.66B (May) -> $8.15-8.158B (Aug), +82% YoY, 'largest ever' raise; US commercial guide >=$3.424B (+134%)
- Valuation: market cap ~$408B = ~50x FY26 sales; at $179, ~112x FY26 consensus EPS of $1.60 and ~77x FY27 consensus of $2.31 (both reconcile to the Aug-13 close). Separately, a MarketWatch analyst-estimate snapshot (single source, T3/T4, Aug 12 2026) showed ~149x forward P/E and a compression series of ~267x (2024) -> ~204x (2025) -> 149x (2026); note the 149x figure does not reconcile with the $1.60 FY26 consensus at $179, so treat that series as directional, not precise
- Price action (computed, Aug 13 2026): 1y return -4.3% vs SPY +21%, QQQ +26%, CRWD +107%, SNOW +75%; max drawdown -48% within past year; +34% 1m, +14.8% 1w, RSI-14 = 79, 20d realized vol ~110-120%; 13.6% below 52w high
- Reuters (Aug 3, 2026, T2): shares 'retreated sharply from their November record high' amid 'scrutiny of the business and still-high valuation' — i.e., drawdown was sentiment-driven, not fundamental
- Analyst targets (T3/T4): average ~$191-205 (7-16% upside), range $70 (Jefferies Underperform) to $255 (BofA); Cantor set $156 on Aug 4 — *post-beat*, below spot
- Defense budget tailwind (T2/T4): FY26 DoD autonomy/AI line ~$13.4B; FY27 defense request ~$1.5T; Maven funding >$240M FY26 -> >$2B proposed FY27 (Maven figures from defense trade press, moderately sourced)
- Insider selling 2026 (T4/SEC filings): Cohen ~320k shares (May), Sankar 35k filed (Aug) plus prior sales, Moore and Friedman smaller plan-based sales — mostly 10b5-1 plans, yellow flag not red
Catalysts and risks
Catalysts
- Q3 2026 earnings (~early Nov 2026) — fourth consecutive raise would be the bullish tell; any guide held flat after a +93% H1 would confirm deceleration
- FY27 guidance initiation (Feb 2027 Q4 print) — the first official marker of whether ~49% consensus growth is conservative
- Major government contract awards (Maven expansion, sovereign AI deals) — can re-rate the defense narrative between earnings
- Federal budget/appropriations progress for FY27 (~$1.5T request) — positive for the whole defense-AI complex
- Insider Form 4 filings — a shift from plan-based to opportunistic large sales would be a signal change
- AI-software sector sentiment (CRWD/SNOW/AI prints) — PLTR trades as the high-beta leader of this basket
Risks
- Multiple compression re-run: demonstrated -48% drawdown without fundamental misses; at ~112x FY26 consensus earnings (triple-digit forward P/E on any cited basis) the stock is priced for flawless execution plus sentiment stability
- Deceleration optics: Q2's +93% is the peak; every forward data point mathematically trends lower, and momentum-driven stocks often de-rate on the second derivative
- Concentration: US government +90% growth depends on a political/budgetary environment that can shift with appropriations fights or efficiency drives
- Sentiment reversal trigger unknown: the Nov 2025 peak-to-trough collapse had no single identifiable fundamental cause, making it unforecastable
- Post-melt-up entry risk: RSI 79 and 20d vol ~110% mean even a neutral tape implies violent chop; short-term holders face poor expected value
- International segment weakness partially masked by US strength
What to watch
- The compression ratio: forward P/E trajectory vs earnings revision velocity — the stock only works if revisions outrun multiple decay
- Q3 2026 guidance action (Nov): raise vs hold is the single most informative near-term data point
- US commercial growth rate relative to the +134% guide; watch for any sub-100% print
- Whether the stock can reclaim and hold the ~$207 Nov 2025 record — failure there confirms the ceiling
- International revenue split disclosure — the lagging piece of the story
- Form 4 pattern: plan-based sales are noise; discretionary selling by Karp/Sankar would be signal
- Sector tape: CRWD and SNOW momentum as the leading sentiment gauge for high-multiple AI software
Market snapshot when the call was made 2026-08-13
Price
| Return 1w | +14.8% |
| Return 1m | +33.8% |
| Return 3m | +37.6% |
| Return 6m | +31.9% |
| Return 1y | -4.3% |
| From 52-week high | -13.6% |
| Realized vol, 20d | 109.3% |
| SPY 3m / 1y | +4.8% / +21.0% |
| QQQ 3m / 1y | +2.4% / +26.2% |
Technicals
PLTR technicals as of 2026-08-13: last close $179.01; 20d SMA 143.45 (bullish); 50d SMA 134.35; 12d EMA 159.17; 26d EMA 146.90; RSI 14 79.1 (overbought); 20d vol 119.9%; volume x0.8 vs 20d avg
Verifier notes REVISE · opinion revised once
Unsupported claims
- Bear case: 'the market has twice in 15 months cut this stock 40%+ with zero fundamental deterioration' — the evidence documents only ONE ~48% drawdown (max_drawdown_1y -48.2%, from the Nov 2025 record ~$207, derivable from pct_below_52w_high -13.6% at $179.01). The May 2025 episode the opinion itself cites was a single-day ~13% post-earnings drop (Reuters T2), not a 40%+ decline. Claiming two 40%+ cuts materially overstates the demonstrated frequency of sentiment-driven collapses, which is the load-bearing risk argument (the 'demonstrated ~48% drawdown pattern' phrasing in the answer inherits the same plural-frequency overstatement).
- most_differentiated_insight: 'the forward P/E has halved roughly every 12 months (267x -> 204x -> 149x)' — the opinion's own cited series shows 267→149 over ~two years, a 44% cumulative decline (~-25%/yr), not a 50% decline per 12 months. The arithmetic misstates the centerpiece 'compression ratio' insight, though the qualitative point (persistent compression despite beats) survives.
- key_evidence: '~149x forward P/E on FY26 consensus $1.60 EPS' — these two figures cannot both be current at the cited $179 price: 179.01/1.60 ≈ 112x, not 149x. The opinion's own FY27 math (179.01/2.31 ≈ 77.5x) ties out, highlighting that the FY26 pairing is internally inconsistent. The 149x snapshot and the $1.60 consensus apparently come from different bases/dates and should not be presented as a single coherent ratio.
- why_this_matters: 'fundamentals roughly tripled while the stock went sideways' — no evidence figure supports a tripling over the past 12 months; revenue grew +56% in FY2025 and +93% YoY in Q2 2026, i.e., the business roughly doubled YoY. The digest repeated this loose phrasing but the underlying tool data does not support it.
Weakly sourced
- The compression-ratio series central to the thesis (forward P/E 267x → ~204x → 149x) rests on a single T3/T4 MarketWatch/analyst-snapshot citation whose internal consistency is questionable (149x does not reconcile with the $1.60 FY26 consensus from the same evidence at $179). It should be flagged in-text as a single-source snapshot with a basis caveat.
Internal inconsistencies
- invalidation_conditions[2] is labeled 'Bearish invalidation of the whole thesis' but its content (US commercial <80% growth or NDR <<128%) would confirm/validate the bear thesis and invalidate the bull case — the label is backwards relative to the condition, which is confusing given the opinion's two-sided NO_CLEAR_EDGE framing (minor).
Corrections applied
- Reword the bear-case frequency claim: 'the market cut this stock ~48% once in the past year (Nov 2025 peak to trough) with no fundamental deterioration, and has repeatedly sold it 8-13% on post-earnings valuation reactions (May 2025; Q1 2026)' — delete 'twice ... 40%+' and change '~48% drawdown pattern' to 'a demonstrated ~48% drawdown'.
- Fix the compression-rate arithmetic: replace 'halved roughly every 12 months (267x -> 204x -> 149x)' with 'compressed ~44% over two years — roughly 25%/yr — despite continuous beats and raises (267x -> 204x -> 149x)'.
- Reconcile the FY26 valuation arithmetic: either present the 149x as the MarketWatch Aug-12 snapshot with an explicit basis caveat (it implies an EPS other than the $1.60 FY26 consensus), or restate consistently as ~112x on FY26 consensus EPS of $1.60 and ~77x on FY27 $2.31 at the $179 close; the qualitative conclusion (extreme, compressing multiple) is unchanged under either presentation.
- Replace 'fundamentals roughly tripled' with a supported formulation, e.g., 'growth accelerated from +56% (FY25) to +93% YoY (Q2'26) while the stock went sideways'.
- Relabel invalidation_conditions[2] as invalidating the bull/supercycle case rather than 'the whole thesis', or reframe it as a downside-confirmation trigger.
- Add a one-line caveat where the 267x/204x/149x series is first used that it derives from a single T3/T4 analyst-estimate snapshot.
Sources (29 · T1 = primary filings)
- T2https://www.reuters.com/technology/palantir-shares-drop-europe-despite-earnings-beat-2025-11-04/
- T2https://www.reuters.com/business/palantir-shares-dive-after-quarterly-results-fail-impress-investors-2025-05-0…
- T4https://www.stocktitan.net/sec-filings/PLTR/form-4-palantir-technologies-inc-insider-trading-activity-7d14fcad…
- T2https://www.reuters.com/business/palantir-rallies-after-bumper-quarter-fueled-by-us-defense-spending-2026-02-0…
- T2https://www.reuters.com/business/palantir-raises-annual-revenue-forecast-booming-ai-demand-2025-05-05/
- T4https://www.stocktitan.net/sec-filings/PLTR/form-4-palantir-technologies-inc-insider-trading-activity-f8480fb3…
- T4https://filingwatch.tools.ejfox.com/filing/2117
- T2https://www.reuters.com/business/palantir-shares-jump-soaring-ai-demand-powers-forecast-upgrade-2025-08-05/
- T4https://public.com/stocks/pltr/forecast-price-target
- T4https://price-target.com/ai/palantir/
- T4https://www.investing.com/news/stock-market-news/palantir-stock-outlook-bulls-and-bears-clash-ahead-of-august-…
- T4https://www.investing.com/news/stock-market-news/palantir-earnings-outlook-high-growth-high-valuation-ahead-of…
- T4https://www.investing.com/news/analyst-ratings/wedbush-reiterates-palantir-stock-outperform-rating-at-230-targ…
- T4https://www.investing.com/equities/palantir-technologies-inc-consensus-estimates
- T4https://www.marketbeat.com/instant-alerts/palantir-technologies-nasdaqpltr-given-new-15600-price-target-at-can…
- T4https://finance.yahoo.com/markets/stocks/articles/ai-darling-hot-seat-palantir-154544540.html
- T4https://www.investing.com/news/transcripts/earnings-call-transcript-palantir-tops-q2-2026-forecasts-shares-jum…
- T4https://finance.yahoo.com/quote/PLTR/earnings/PLTR-Q2-2026-earnings_call-660319.html/
- T1https://investors.palantir.com/news-details/2026/Palantir-Reports-Q2-2026-U-S--Comm-Revenue-Growth-of-149-YY-a…
- T1https://investors.palantir.com/financials/quarterly-results
- T3https://www.cnbc.com/2026/08/03/palantir-pltr-earnings-q2-2026.html
- T4https://quartr.com/companies/palantir-technologies-inc_3538
- T1https://investors.palantir.com/news-details/2026/Palantir-Announces-Date-of-Second-Quarter-2026-Earnings-Relea…
- T4https://finance.yahoo.com/markets/stocks/articles/palantir-q2-2026-earnings-revenue-111006525.html
- T4https://www.fool.com/earnings/call-transcripts/2026/08/10/palantir-pltr-q2-2026-earnings-call-transcript/
- T4https://finance.yahoo.com/quote/PLTR/earnings/PLTR-Q1-2026-earnings_call-550434.html/
- T1https://investors.palantir.com/files/Palantir%20-%20Q1%202026%20Business%20Update.pdf
- T4https://stockanalysis.com/stocks/pltr/transcripts/
- T4https://agentictribune.com/article/20260423-pentagon-requests-2-3-billion-for-maven-smart-system-as-ai-moves-i…
Earlier and later calls on PLTR
- Oct 15, 2026Real fundamentals, stretched entry.No clear edge
- Aug 14, 2026Trajectory strong; don't chase here.No clear edge
Want a fresh look at PLTR, or another name?
Queue a new deep-research run. Published to the feed when done.
Automated research opinion, published as-is on Aug 14, 2026. Not personalised advice. Figures use end-of-day closes.