Real fundamentals, stretched entry.
Thesis
Bull case
Demand is accelerating, not peaking: U.S. commercial +149%, RPO +103%, sovereign-AI demand broadening, and estimates still rising with zero downward revisions. Operating leverage is real (op margin -27% in 2021 → 47% GAAP in Q2 2026), so if FY27 consensus keeps getting revised up 10%+ per quarter, even an 85x multiple gets grown into faster than bears model — another large Q3 beat-and-raise could push the stock toward the $230–$265 bull targets (+15–32%).
Bear case
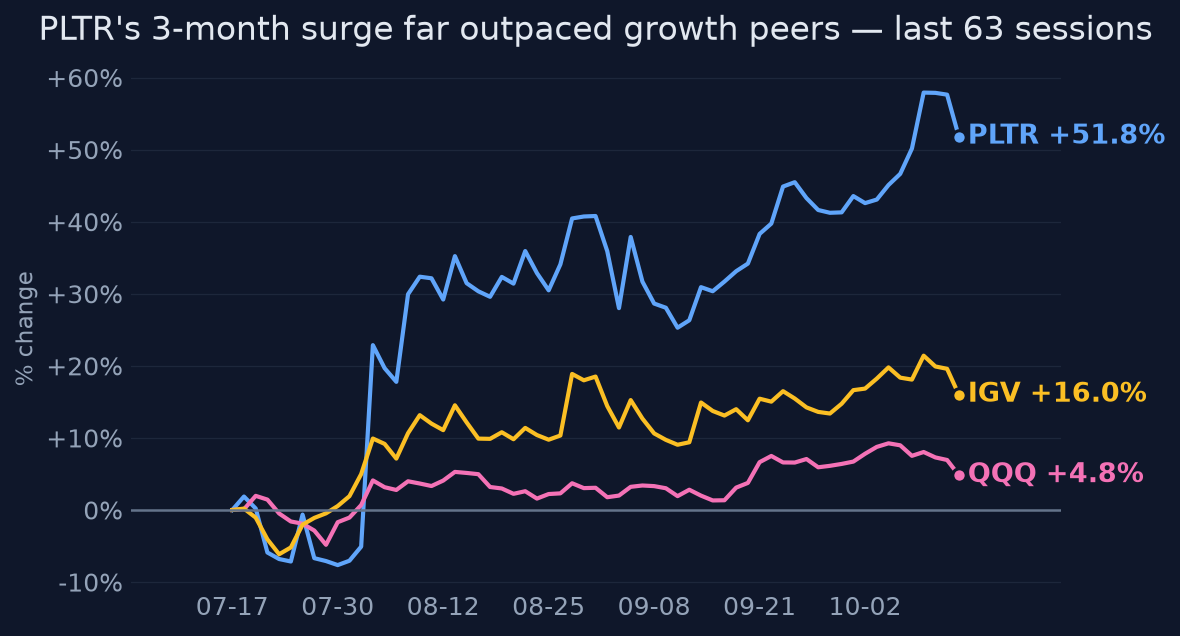
The price already discounts the excellence. The aggregator-sourced consensus target equals the current price, and the 3-month rally outpaced even the combined fundamental upgrades (6.5% guide raise, 11pp growth acceleration, +12% FY27 EPS revision) — i.e., predominantly multiple expansion. At 123x FY26 earnings with SBC ~$265M/quarter diluting behind 'adjusted' margins, any deceleration in FY27 from the computed ~+51% consensus growth toward 30-40%, a merely in-line Q3, or a high-multiple software rotation triggers a stock that has shown it can draw down 48% within a year.
What would change our mind
- If Q3 delivers a guidance raise of similar or larger magnitude than Q2's AND the stock fails to make new highs within weeks, the momentum thesis is broken — exit/reverse
- If FY27 EPS revisions turn net negative or FY27 revenue consensus drops below ~+40% growth, the bull case is invalidated at this multiple
- If the stock breaks below the 50d SMA (~$181) on earnings volume, the technical setup that the scan flagged no longer exists
- Conversely, a confirmed re-acceleration of FY27 estimates above $2.60 with the street raising targets above price would invalidate the 'fully priced' framing
Since publication vs SPY · closed horizons are frozen
The full research everything the view rests on
Direct answer to the question asked
Where the edge would come from
What the price assumes
At ~$201 the market prices in continued beat-and-raise execution: FY26 revenue +82% ($8.15B), FY27 revenue ~$12.3B (implying ~+51% growth, computed from a single T4 market summary) and EPS of $2.34, with no deceleration and no multiple compression. An aggregator-sourced consensus 12-month target of ~$200.54 implies the street sees zero incremental upside from here despite believing the growth.
Why the market may be wrong
The market could be wrong in either direction, which is why there's no edge: bulls are right that 26 upward vs 0 downward FY27 EPS revisions in 30 days and +103% RPO growth signal demand durability that could force yet another guidance raise; bears are right that the stock's 49% 3-month re-rating dwarfs even the combined fundamental upgrades (6.5% FY26 guide raise, 11pp growth acceleration, +12% FY27 EPS revision), so any deceleration toward 'merely' 30-40% growth violently compresses an 85x forward multiple. The 3rd-percentile vol reading suggests the options market may be underpricing gap risk into the (unconfirmed) Nov 2 print.
The one thing to watch
The variable to watch is not the Q3 beat itself but the guidance-raise-to-price-response ratio: the stock re-rated ~49% against fundamental upgrades (guide raise, growth acceleration, FY27 revisions) that were large in absolute terms but small relative to the price move — meaning the marginal buyer is now paying mostly for multiple expansion. The moment a large guidance raise stops producing upside, the momentum regime is over regardless of how good the fundamentals are.
Key evidence (10)
- Q2 2026 (reported Aug 12, 2026): revenue $1.935B +93% YoY; U.S. commercial +149%; U.S. government +90%; GAAP op margin 47%; adj FCF $1.22B (63% margin) [T1 Palantir IR]
- FY26 guidance raised to $8.150–8.158B (+82% YoY), up from ~$7.66B guided in Q1 — a ~6.5% midpoint raise plus an 11pp acceleration in expected growth rate, vs a +49% 3-month stock move [T1]
- Forward indicators: remaining deal value $13.1B (+83% YoY), RPO $4.9B (+103%), closed TCV $3.373B [T1]
- FY27 consensus EPS revised up ~12% in 90 days ($2.09→$2.34); 26 upward vs 0 downward revisions in 30 days [T4]
- Valuation: ~$459B market cap ≈ 123x FY26 EPS ($1.62), 85x FY27 EPS ($2.34), ~56x FY26 sales [computed from T1/T4 consensus]
- Consensus 12-month price target ~$200.54 vs price ~$201; target range $80–$265 [T4 aggregators only — load-bearing but low-tier]
- 20d realized vol 30.5% at the 3rd percentile of trailing year vs 58.5% 1y vol; 1y max drawdown -48% [computed from price history]
- Past earnings reactions are ambiguous in the evidence: two T4 transcript titles contradict each other on whether Q1 2026 was a beat-and-climb or beat-and-drop; cannot be resolved from the bundle
- Q2 GAAP EPS included $0.03 unrealized SpaceX gain; SBC ~$265M/quarter; Karp sold ~1.38M shares (~$206M) Feb/May/Aug 2026, characterized in filings as automatic 10b5-1 tax-withholding sales [T4 Form 4 aggregators — weak bearish signal]
- Q3 2026 report expected ~Nov 2, 2026 (not company-confirmed) [T4]
Catalysts and risks
Catalysts
- Q3 2026 earnings ~Nov 2, 2026 (guided revenue $2.160–2.164B; date not company-confirmed) — binary event into compressed vol
- FY26 guidance raise magnitude at Q3 vs the stock's reaction (the revision-to-re-rating ratio)
- FY27 consensus revision trajectory (currently +12%/90 days)
- Any confirmed Sep–Oct contract announcements the research could not verify
Risks
- Multiple compression on any growth deceleration — the dominant risk at 85x FY27 EPS
- Q3 in-line or small-beat reaction: stock priced for another large raise, and at least one prior print produced a muted/negative reaction despite a beat (which print is unresolvable from the evidence)
- Vol regime shift: 3rd-percentile 20d vol with beta ~3 to SPY means a macro wobble hits PLTR disproportionately
- SBC/dilution and one-off investment gains flattering headline profitability
- Government budget/procurement timing lumpiness; international segment detail unquantified
- Key valuation anchors (consensus target ~$200.54, $80–$265 range, FY27 revenue ~$12.3B) rest on T4 aggregators only
What to watch
- Q3 print (~Nov 2, unconfirmed): revenue vs $2.16B guide and especially the FY26/FY27 guidance raise size relative to the stock's reaction
- FY27 revision direction and breadth (26:0 up:down currently — any flip matters)
- 20d realized vol normalization post-earnings; whether the vol compression resolves up or down
- Q3 10-Q: diluted share count trend and SBC as % of revenue
- International commercial growth disclosure — the unverified soft spot
- Street target moves: consensus target at price means any analyst capitulation (up or down) is informative
Market snapshot when the call was made 2026-10-14
Price
| Return 1w | +3.5% |
| Return 1m | +16.5% |
| Return 3m | +49.5% |
| Return 6m | +41.4% |
| Return 1y | +13.4% |
| From 52-week high | -3.9% |
| Realized vol, 20d | 30.5% |
| SPY 3m / 1y | +2.5% / +16.1% |
| QQQ 3m / 1y | +3.3% / +21.1% |
Technicals
PLTR technicals as of 2026-10-14: last close $200.97; 20d SMA 191.92 (bullish); 50d SMA 181.12; 12d EMA 197.93; 26d EMA 189.84; RSI 14 60.9 (balanced); 20d vol 30.7%; volume x1.0 vs 20d avg
Next earnings: 2027-02-01 AMC
Verifier notes REVISE · opinion revised once
Unsupported claims
- The opinion repeatedly asserts 'Q1 2026 was a beat-and-drop reaction' (thesis, bear_case, key_evidence). The evidence bundle's own T4 citations contradict each other on this point: one Investing.com transcript title reads 'Palantir Q1 2026 exceeds forecasts, stock climbs' and another reads 'earnings beat, stock drops'. The evidence cannot resolve which is correct, so stating beat-and-drop as an established fact is not supported by the bundle as provided.
- FY27 consensus revenue '+51%' growth: the evidence gives FY27 revenue of ~$12.3B and FY26 guidance of ~$8.15B, which implies ~51%, so this is acceptable arithmetic — but the opinion presents it as 'consensus FY27 revenue growth' when the evidence only supplies a single FY27 revenue figure from a T4 market summary; the +51% is derived, not stated, and should be tagged as computed.
Weakly sourced
- The Q1 2026 beat-and-drop claim rests solely on contradictory T4 transcript titles, yet it anchors the bear case ('recall Q1's beat-and-drop') and appears in the thesis — a materially decision-relevant precedent.
- The claim that the stock's +49% 3-month move was 'mostly multiple expansion' relies on the FY26 guidance raise of 6.5% as the sole benchmark for fundamentals; the evidence also shows an 11-percentage-point acceleration in expected growth rate and a +12% FY27 EPS revision, which partially undercuts the pure 'multiple expansion' framing. The claim is arguable but presented as more definitive than the evidence warrants.
- Consensus price target ~$200.54 and the $80–$265 range rest on T4 aggregators only; this is load-bearing for the central 'street target = price' argument.
Internal inconsistencies
- Minor: the answer states the move happened '~2.5 weeks before a binary Q3 print (~Nov 2)' while key_evidence correctly notes the date is not company-confirmed; the catalysts section also flags it as unconfirmed, so this is internally handled, but the market_expectation framing treats the date as settled. Not material enough to fail on its own.
Corrections applied
- Soften or verify the Q1 2026 reaction claim: either confirm from a reliable source whether Q1 2026 was a beat-and-drop or a beat-and-rally, or rephrase as 'one of the past two prints produced a muted/negative reaction despite a beat' and remove it from load-bearing positions in the bear case until verified.
- Tag the consensus price target ($200.54) and target range as aggregator-sourced [T4] in the body of the argument, not only in key_evidence, since the core 'street won't underwrite the stock' thesis depends on it.
- Present the +51% FY27 revenue growth as computed from the $12.3B FY27 consensus revenue figure, and note it derives from a single T4 market summary.
- Qualify the 'multiple expansion, not revisions' framing to acknowledge the +12% FY27 EPS revision and 11pp guidance-growth acceleration, e.g., 'predominantly multiple expansion despite meaningful FY27 estimate revisions'.
Sources (24 · T1 = primary filings)
- T4https://www.pricetargets.com/NASDAQ/PLTR/
- T4https://www.marketbeat.com/stocks/NASDAQ/PLTR/forecast/
- T4https://finance.yahoo.com/markets/stocks/articles/pltr-stock-just-8-away-121057822.html
- T4https://www.marketbeat.com/instant-alerts/consensus-palantir-technologies-inc-pltr-what-are-analysts-thinking-…
- T4https://finance.yahoo.com/quote/PLTR/research-reports/
- T4https://www.zacks.com/stock/research/PLTR/price-target-stock-forecast
- T4https://247wallst.com/investing/2026/10/13/palantir-stock-has-become-a-wall-street-sensation-heres-my-price-pr…
- T4https://www.theglobeandmail.com/investing/markets/stocks/PLTR/pressreleases/
- T4https://www.stocktitan.net/sec-filings/PLTR/form-4-palantir-technologies-inc-insider-trading-activity-48a8d6e3…
- T4https://www.stocktitan.net/sec-filings/PLTR/form-4-palantir-technologies-inc-insider-trading-activity-87b6859e…
- T4https://trabud.com/insider-trading/PLTR
- T4https://strongbuyanalytics.com/stocks/PLTR/sec-filing-news
- T4https://aistockwire.com/stock/PLTR
- T4https://www.stocktitan.net/sec-filings/PLTR/form-4.html
- T4https://www.signalstack.news/insiders/palantir/
- T4https://www.stocktitan.net/sec-filings/PLTR/form-4-palantir-technologies-inc-insider-trading-activity-c654c12a…
- T1https://investors.palantir.com/news-details/2026/Palantir-Reports
- T1https://investors.palantir.com/news-details/2026/Palantir-Reports-Q2-2026-U-S--Comm-Revenue-Growth-of-149-YY-a…
- T4https://finance.yahoo.com/quote/PTX.HM/earnings/PTX.HM-Q2-2026-earnings_call-660319.html/
- T4https://finance.yahoo.com/quote/PLTR.VI/earnings/PLTR.VI-Q2-2026-earnings_call-660319.html
- T4https://www.theglobeandmail.com/investing/markets/stocks/PLTR/pressreleases/3767775/palantir-pltr-q2-2026-earn…
- T4https://finance.yahoo.com/quote/PTX0.DU/earnings/PTX0.DU-Q2-2026-earnings_call-660319.html
- T4https://finance.yahoo.com/quote/PTX.MU/earnings/PTX.MU-Q2-2026-earnings_call-660319.html
- T1https://investors.palantir.com/news-details/2026/Palantir-Announces-Date-of-Second-Quarter-2026-Earnings-Relea…
Earlier and later calls on PLTR
- Aug 14, 2026Great company, bad entry price.No clear edge
- Aug 14, 2026Trajectory strong; don't chase here.No clear edge
Want a fresh look at PLTR, or another name?
Queue a new deep-research run. Published to the feed when done.
Automated research opinion, published as-is on Oct 15, 2026. Not personalised advice. Figures use end-of-day closes.