Derated, not deteriorating — lean bullish.
Thesis
Bull case
The market is pricing terminal disruption that the numbers don't show: 18-22% guided bookings growth, record FCF, stable FY27 estimates, and ~$104 street targets versus a $69 stock. The September restructuring (10% headcount cut) likely converts into margin upside in H2 2026/2027 that offsets AV spend. Uber's aggregator position — demand aggregation, pricing, insurance, regulatory infrastructure — remains the cheapest commercialization path for every AV player except Waymo, and the Nvidia/Lucid/Nuro deals plus Aurora stake give it optionality across multiple AV outcomes. At 15.6x FY27 with buybacks shrinking the share count, even flat growth compounds EPS; any sign Waymo renews in Austin/Atlanta or AV losses stay contained re-rates the stock toward the street's targets (50% upside).
Bear case
Waymo at 500k rides/week is no longer a pilot, and its pullback from Uber (Phoenix ended, reported tension) is the market's clearest signal that the winning AV player intends to keep the economics itself — exactly the disintermediation scenario Uber's platform thesis depends on avoiding. Uber's response requires hundreds of millions into unproven partners (Nuro/Lucid) with 2027+ deployment timelines, already visible in below-consensus Q3 EPS guidance. The restructuring may signal that organic growth no longer funds the pivot — a read supported by the stock falling on its best cash-flow quarter ever. If consensus FY27 EPS of $4.45 proves optimistic (insurance costs, AV spend, share loss in premium urban trips), the 'cheap' 15.6x multiple is an illusion and the stock derates further toward Lyft-style multiples.
What would change our mind
- Q3 2026 bookings growth comes in below the 18-22% cc guidance range while AV spending rises — evidence the core business is decelerating AND the hedge is expensive
- Waymo formally ends or announces non-renewal of Austin/Atlanta operations on Uber's platform
- FY2027 consensus EPS revised down more than ~10% (below ~$4.00), converting the apparent 15.6x multiple into a value trap
- Restructuring fails to produce disclosed savings by Q4 2026 reporting while headcount cuts hit product velocity
- Evidence emerges of measurable mobility share loss to Waymo/Tesla in overlapping metros (market-level booking data)
Since publication vs SPY · closed horizons are frozen
The full research everything the view rests on
Direct answer to the question asked
Where the edge would come from
What the price assumes
At ~20.6x FY26 / ~15.6x FY27 consensus EPS and 3% above the 52-week low, the price assumes meaningful probability that autonomous providers (Waymo, Tesla) structurally erode Uber's take rate and growth, and that Uber's AV investments (Lucid/Nuro, Nvidia 28-city plan) are value-destructive capital. It also implicitly discounts the possibility that consensus FY27 EPS of ~$4.45 is too high. What it does NOT appear to assume is continued 18-22% bookings growth with expanding margins — which is what the company is actually guiding.
Why the market may be wrong
Two ways. Bullish version: the AV threat is a terminal-value narrative with no current P&L evidence — bookings are guided up 18-22% cc, the restructuring adds cost leverage, and a 7% FCF yield funds buybacks that mechanically lift EPS even in a flat-growth scenario; the market may be paying 2026 prices for a 2029 risk. Bearish version the market may be UNDER-pricing: Waymo — the most advanced AV player — is shrinking its Uber relationship (Phoenix ended, tension flagged) while scaling to ~500k paid rides/week in 14-15 cities, and Uber's replacement partners (Nuro/Lucid, Baidu, WeRide) are unproven at scale; if disintermediation economics show up sooner than expected, even 15.6x FY27 is not cheap.
The one thing to watch
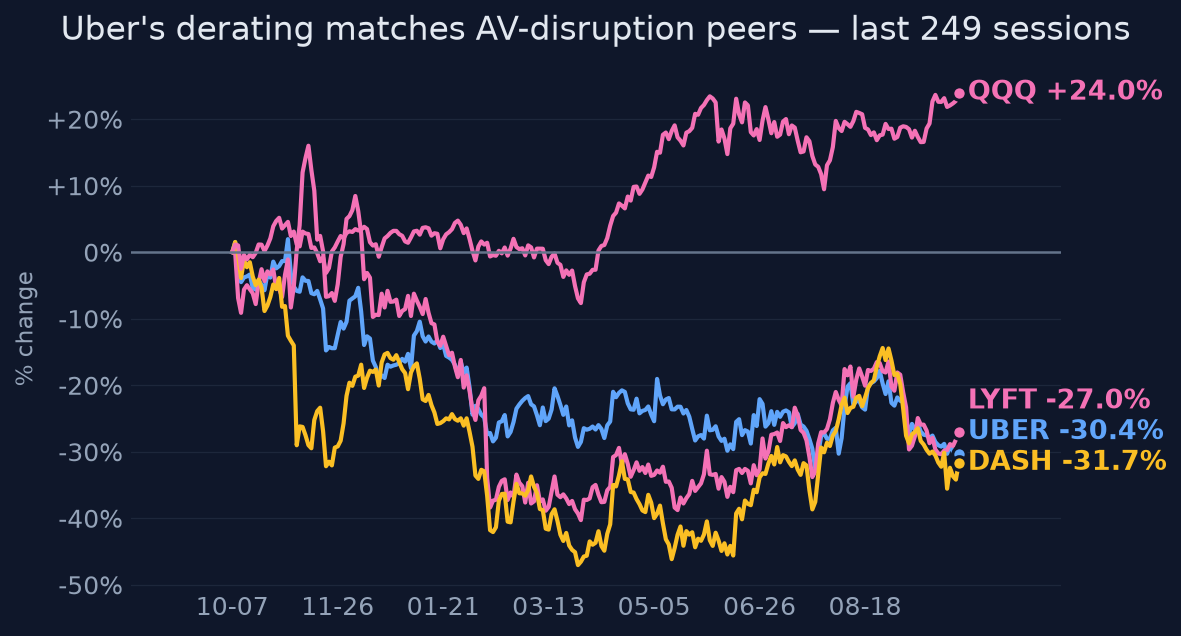
The single most important quantitative fact is that UBER, LYFT, and DASH all fell almost exactly 29-30% over the past year while diverging operationally — the cohort is trading as one AV-disruption basket with a 0.64 Uber-Lyft correlation but only 0.15 to SPY. That reframes the trade: Uber's near-term stock price will be set by the resolution of the AV narrative, not by whether it beats Q3 EPS by a cent. The variable to watch is therefore not bookings growth but the Waymo-Uber contract trajectory in Austin/Atlanta — if Waymo exits or re-prices those markets, the platform-aggregator thesis breaks; if Waymo renews or deepens, the basket derating reverses regardless of what Uber itself does.
Key evidence (10)
- UBER -29.5% 1y vs LYFT -30.4%, DASH -29.3%, SPY +15.1%, QQQ +24.8%; 60d correlation 0.64 to LYFT vs 0.15 to SPY — cohort derating, not idiosyncratic failure [computed from daily price history, 2026-10-06]
- FY2025: revenue $52.0B (+18%), operating margin 10.7% (vs 6.4% in 2024), GAAP EPS $4.73 [SEC XBRL, T1]
- Q2 2026 (Aug 5): revenue $14.2B +12% YoY, gross bookings >$58B above guidance high end, non-GAAP EPS +35% YoY, TTM FCF >$10B first time [T1 investor.uber.com; T1 SEC 10-Q; T2 Reuters]
- Q3 2026 guidance: gross bookings $58.25-60.25B (+18-22% cc) but adjusted EPS $0.84-0.88, below $0.89 consensus, tied to robotaxi investment; stock fell on the print [T2 Reuters 2026-08-05]
- Consensus FY26 EPS ~$3.35-3.37, FY27 ~$4.42-4.45, 3-month revisions roughly flat; analyst PT ~$104 [T3 MarketWatch, T2 WSJ snapshots, Sept 2026]
- Waymo: ~500k paid rides/week across 14-15 cities; Uber-Waymo relationship shrinking — Phoenix partnership ended, tension disclosed [T2 Reuters Sept 2026; relationship status partly T4-sourced]
- Tesla paid robotaxi live in Austin/Dallas/Houston/Miami with dynamic pricing but undisclosed fleet size — real, not yet at scale [T2 Reuters Apr/Sept 2026]
- Uber AV commitments: $300M Lucid + multi-hundred-million Nuro (20,000+ Gravity robotaxis) [T1 IR Jul 2025]; Nvidia 28-city robotaxi plan from 2027 [T2 Reuters 2026-03-16]; Uber Autonomous Solutions platform Feb 2026 [T1 IR]; ~19.7% Aurora Class A stake [T4-sourced ownership figure]
- Sept 2026 restructuring: 3,300 jobs (~10% of staff, largest since COVID), management flattening, engineering/science/delivery teams combined, no disclosed dollar savings target [T2 Reuters/Bloomberg 2026-09-02]
- Next earnings: Q3 2026 results November 4, 2026 [T1 BusinessWire]; 20d realized vol at 0th percentile of trailing year — coiled at lows [quant analysis]
Catalysts and risks
Catalysts
- Q3 2026 earnings November 4, 2026 — first read on restructuring savings, AV spend trajectory, and whether bookings guidance holds
- Any Waymo-Uber contract news in Austin/Atlanta (renewal, re-pricing, or exit) — the single highest-impact event for the thesis
- Tesla Cybercab/robotaxi expansion announcements (fleet size, new cities, pricing data)
- Uber-Nvidia 28-city robotaxi rollout details ahead of 2027 launch
- Q4 2026 earnings February 2, 2027 with first FY27 guidance
- Quantified restructuring savings disclosure (none given so far)
Risks
- Waymo exits or re-prices the Uber partnership, validating disintermediation and collapsing the aggregator thesis
- AV investment spending accelerates, pushing EPS guidance below consensus again and confirming the margin trade-off is structural
- FY27 consensus EPS (~$4.45) proves too high — insurance costs, driver-classification regulation, or AV losses compress estimates
- The restructuring signals growth anxiety rather than discipline; 10% cuts can damage execution in delivery/engineering
- Insurance-cost and driver-classification pressures referenced in coverage but not quantified — weakly sourced tail risk
- Cohort correlation works both ways: a Tesla robotaxi breakthrough or Waymo expansion headline hits the whole basket regardless of Uber's numbers
What to watch
- Waymo-Uber Austin/Atlanta contract status and any Waymo expansion announcements — the lead variable, ahead of Uber's own prints
- Nov 4 Q3 print: gross bookings vs $58.25-60.25B guide, adjusted EPS vs $0.84-0.88, and any quantified restructuring savings
- FY27 estimate revision trend — flat-to-up supports the derating-is-overdone thesis; a break below ~$4.30 breaks it
- Uber's AV capital commitments (additional equity investments or fleet purchase obligations in filings)
- 20d realized vol expansion from the 0th percentile — direction of the break will likely track the AV narrative, not the tape
- Lyft and DoorDash price action as basket-sentiment proxies; UBER outperforming the cohort on down days would signal idiosyncratic accumulation
Market snapshot when the call was made 2026-10-05
Price
| Return 1w | -2.2% |
| Return 1m | -10.9% |
| Return 3m | -6.0% |
| Return 6m | -5.2% |
| Return 1y | -29.5% |
| From 52-week high | -32.0% |
| Realized vol, 20d | 22.6% |
| SPY 3m / 1y | +2.4% / +15.1% |
| QQQ 3m / 1y | +6.6% / +24.8% |
Technicals
UBER technicals as of 2026-10-05: last close $69.48; 20d SMA 70.27 (bearish); 50d SMA 73.10; 12d EMA 69.47; 26d EMA 70.99; RSI 14 39.2 (balanced); 20d vol 21.4%; volume x0.9 vs 20d avg
Next earnings: 2027-02-02 AMC
Sources (23 · T1 = primary filings)
- T4https://techcrunch.com/2026/08/01/ubers-autonomous-vehicle-deal-tracker/
- T1https://investor.uber.com/news-events/news/press-release-details/2025/Lucid-Nuro-and-Uber-Partner-on-Next-Gene…
- T1https://investor.uber.com/news-events/news/press-release-details/2026/Uber-Unveils-Uber-Autonomous-Solutions-t…
- T4https://www.aljazeera.com/economy/2025/7/17/uber-to-invest-in-300m-in-ev-maker-lucid-amid-robotaxi-deal
- T1https://investor.uber.com/news-events/news/press-release-details/2026/Lucid-Nuro-and-Uber-Unveil-Global-Robota…
- T4https://quartr.com/companies/uber-technologies-inc_5981
- T4https://insideevs.com/news/787935/how-uber-plans-to-win-the-autonomous-vehicle-race/
- T4https://www.investors.com/news/technology/uber-stock-autonomus-vehicles-robotaxi-solutions/
- T2https://www.reuters.com/commentary/breakingviews/london-will-wage-international-robotaxi-warfare-2026-06-24/
- T2https://www.reuters.com/business/world-at-work/uber-cut-3300-jobs-overhaul-bloomberg-news-reports-2026-09-02/
- T2https://www.reuters.com/legal/litigation/musk-pushes-regulatory-limits-with-teslas-cybercab-robotaxi-service-2…
- T2https://www.reuters.com/business/autos-transportation/teslas-cybercab-event-set-thursday-with-few-details-2026…
- T2https://www.reuters.com/business/autos-transportation/uber-nvidia-plan-robotaxi-rollout-28-cities-starting-nex…
- T2https://www.reuters.com/business/amazons-zoox-alphabets-waymo-expand-robotaxi-services-more-us-cities-2026-09-…
- T2https://www.reuters.com/business/autos-transportation/tesla-rolls-out-robotaxis-dallas-houston-2026-04-18/
- T2https://www.reuters.com/technology/teslas-musk-unveil-robotaxis-amid-fanfare-skepticism-2024-10-10/
- T2https://www.bloomberg.com/news/articles/2026-09-02/uber-to-cut-3-300-jobs-in-company-overhaul-to-reduce-manage…
- T2https://www.reuters.com/business/autos-transportation/uber-forecasts-weak-quarterly-profit-doubles-down-robota…
- T2https://www.bloomberg.com/news/videos/2026-09-02/uber-to-cut-3-300-jobs-in-management-overhaul-video
- T4https://www.bnnbloomberg.ca/business/company-news/2026/09/02/uber-to-lay-off-10-per-cent-of-staff-in-biggest-c…
- T4https://finance.yahoo.com/markets/stocks/articles/uber-cutting-3-300-jobs-115712298.html
- T4https://economictimes.indiatimes.com/tech/technology/uber-to-cut-3300-jobs-in-overhaul-bloomberg/articleshow/1…
- T4https://finance.yahoo.com/small-business/articles/uber-cut-3-300-jobs-112432567.html
Earlier and later calls on UBER
- Oct 18, 2026Yes — derating looks overdone.Lean bullish
- Sep 1, 2026Yes — value is emerging here.Lean bullish
- Aug 9, 2026Not immediately; strategically, yes.Lean bullish
Want a fresh look at UBER, or another name?
Queue a new deep-research run. Published to the feed when done.
Automated research opinion, published as-is on Oct 6, 2026. Not personalised advice. Figures use end-of-day closes.