Priced for a future not yet visible.
Thesis
Bull case
The Q3 beat shows demand is more resilient than the bear narrative; energy storage is a real second business growing into miss-and-recover cadence; robotaxi went from zero to paid unsupervised rides in six metros within months, and if the Oct 21 call discloses even modest paid-rider revenue plus a credible Cybercab volume-production timeline, the market will capitalize the ramp at software multiples — Tesla has repeatedly re-rated 30-50% on narrative inflections, and a Q4 near 520K deliveries plus robotaxi numbers would be exactly that. Median target $412 and the $550-840 bull targets imply the Street's center of mass is above spot.
Bear case
This is a shrinking automaker (EPS -75% in two years, deliveries -2.1% YoY, China share halved, storage missing) wearing a $1T+ costume of unpriced optionality. The Q3 'beat' was inventory drawdown against a lowered bar; Q4 needs 519-572K to hit consensus — a sequential leap with no new model. The robotaxi is 1/10th of Waymo's demonstrated scale, has no disclosed revenue, faces two NHTSA probes, and independent trackers dispute the company's fleet claims. At 180x forward with negative revisions, the first hard robotaxi numbers are more likely to shrink the narrative premium than grow it; BNP's $266 target is what the auto business plus reasonable optionality is worth.
What would change our mind
- Oct 21 call discloses robotaxi revenue with paid rider-only trip counts and active fleet consistent with company claims (300+ vehicles) — converts narrative to fact
- Auto gross margin prints ≥18% with deliveries on a path to 1.8M+ FY26 — core deterioration thesis breaks
- FY27 EPS revisions turn net positive for 60+ days — the down-revision regime ends
- Confirmed Cybercab volume production start date in 2027 with regulatory path cleared
Since publication vs SPY · closed horizons are frozen
The full research everything the view rests on
Direct answer to the question asked
Where the edge would come from
What the price assumes
Median Street target $412.50 implies ~13% upside and a consensus Buy, so the market expects Q3 to show stabilizing auto margins (~17.3% gross expected), energy growth offsetting auto weakness, and — critically — the Oct 21 call to convert robotaxi from narrative to numbers: paid rider-only trips, active fleet, initial revenue. Consensus FY26 deliveries ~1.77-1.82M embed a heroic Q4 acceleration to ~519-572K.
Why the market may be wrong
Consensus may be conflating 'beat vs lowered bar' with demand recovery: Q3's beat was inventory drawdown (deliveries exceeded production by 22K) with Model 3/Y at 98.3% of volume — no new demand driver. If the Oct 21 call confirms robotaxi revenue is immaterial and independent trackers (no confirmed paying riders as of Sep 30) are closer to truth than the company's '300+ Cybercabs, 8x growth in 30 days' claim, the multiple-supporting narrative loses its first falsifiable test. Conversely, if Tesla discloses real paid-rider volumes, bears anchored on 'pilot scale' are wrong fast.
The one thing to watch
The variable to watch is not deliveries or margins — it is whether Tesla discloses a robotaxi revenue line on Oct 21. The fleet-size contradiction (company: 300+ Cybercabs in Austin, up 8x in 30 days; Texas registrations in June: 59 vehicles; independent trackers: no confirmed paying riders as of Sep 30) is the first moment Tesla's $1T autonomy narrative becomes falsifiable with audited numbers. Any disclosure small enough to be called 'immaterial' reprices the stock as a 180x automaker; silence itself is information.
Key evidence (11)
- Q3 2026 deliveries 486,532: +5.3% vs company-compiled consensus but -2.1% YoY; deliveries exceeded production by 22,141 (inventory drawdown); Model 3/Y = 98.3% of volume [T1 ir.tesla.com, Oct 2026]
- Diluted EPS: $4.30 (2023) → $2.04 (2024) → $1.08 (2025); 2025 operating margin 4.6%; revenue fell to $94.8B in 2025 [T1 SEC XBRL]
- Forward P/E ~170-190x on FY26 consensus EPS ~$1.74; FY27 EPS consensus cut ~12.6% over 90 days; 19 downward vs 4 upward revisions in 30 days [T3/T4, Oct 2026]
- Paid Cybercab rides began Sep 3, 2026 in Austin; unsupervised ops in TX/FL; Bay Area still safety-drivered; company claims 300+ Cybercabs in Austin [T2 Reuters + T4]
- Texas registration data (June): 59 Tesla robotaxis vs 600+ Waymo; Waymo at 500K+ fully autonomous rides/week across 10+ cities [T2/T3]
- No disclosed robotaxi revenue line; revenue described as negligible; independent trackers claimed no confirmed paying riders as of Sep 30 [T4 — explicitly contested with company claims]
- China BEV share ~6.6% Q2 2026 vs 15%+ in 2020; BYD at 22.8% September NEV share [T2/T3]
- Energy storage Q3: 13.7 GWh, below ~15.9 GWh expectation [T1/T4]
- NHTSA scrutiny: school-zone speeding allegations (~1,000 vehicles) and Cybercab self-certification inquiry [T2/T4]
- Street: median target $412.50, average $398-412, dispersion $25-$840 across 38-46 analysts [T3/T4]
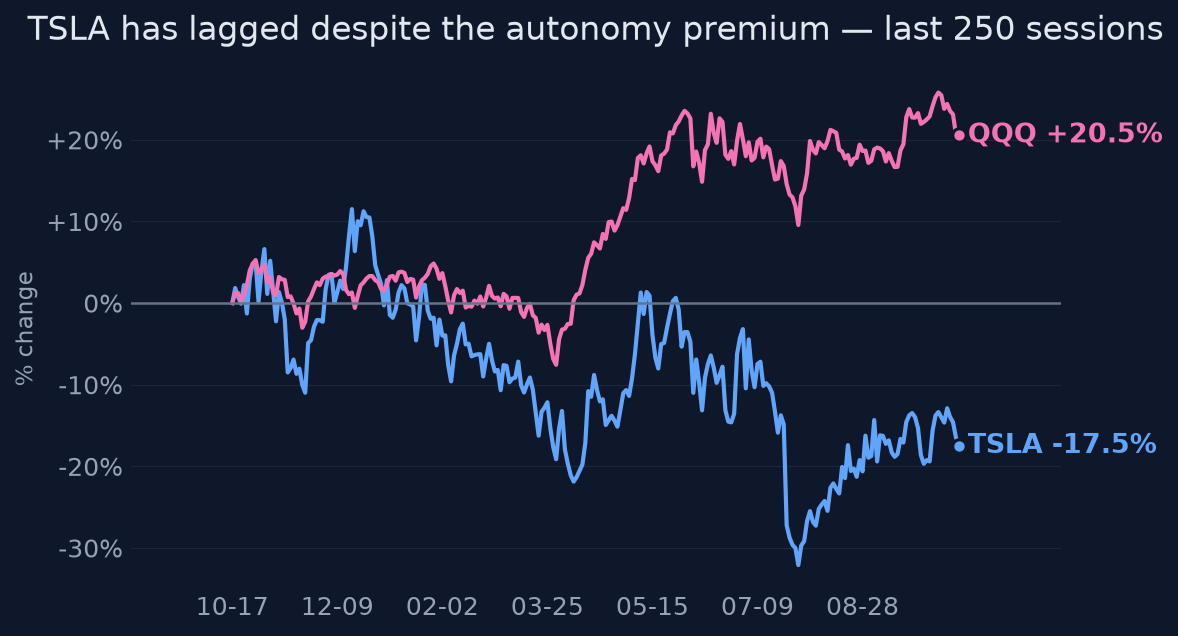
- 1yr return -15.6% vs SPY +16.5%/QQQ +21.7%; 26% below 52w high; 20d realized vol at 6th percentile of its own 1yr range into earnings [market data, Oct 15 2026]
Catalysts and risks
Catalysts
- Q3 2026 earnings and call, Oct 21, 2026 (5:30pm ET): auto gross margin vs ~17.3% expected, first robotaxi revenue/trip disclosure, FCF and AI capex
- Q3 10-Q filing: segment detail, any robotaxi accounting, inventory levels confirming/refuting pull-forward
- Q4 2026 delivery report (early Jan 2027) vs implied 519-572K consensus requirement
- Cybercab volume production timeline announcement; affordable model confirmation
- NHTSA probe outcomes on school-zone speeding and Cybercab self-certification
- Q4 2026 earnings Jan 26, 2027 (consensus EPS $0.486, revenue ~$29.1B)
Risks
- Narrative re-rating risk: TSLA has a long history of rallying on autonomy promises despite fundamentals; a charismatic Oct 21 call could gap the stock up regardless of numbers
- Short-side crowding and high beta (1.9) make bearish positioning violent around catalysts
- Fleet-size data is contested and partly T4-sourced; if company claims prove accurate, the bear 'pilot scale' claim weakens
- Energy storage and potential affordable model could re-accelerate the core business
- Consensus data itself is unreliable — FY27 EPS estimates ranged $0.73 to $2.34 across vendors
What to watch
- Whether 'robotaxi' appears as a revenue or deferred-revenue line in the 10-Q, and exact paid-rider trip counts on the call
- Active fleet vs registered fleet reconciliation; Bay Area transition to unsupervised
- Q4 weekly delivery/registration data (China insurance registrations) vs the 519-572K implied requirement
- NHTSA docket updates on the two open probes
- FY27 EPS consensus direction post-earnings; any capex guidance signaling AI spend vs FCF tradeoff
- 20d realized vol — at 6th percentile pre-earnings, options imply the market is underpricing the print
Market snapshot when the call was made 2026-10-15
Price
| Return 1w | -3.4% |
| Return 1m | +1.2% |
| Return 3m | -4.8% |
| Return 6m | -6.8% |
| Return 1y | -15.6% |
| From 52-week high | -26.0% |
| Realized vol, 20d | 30.6% |
| SPY 3m / 1y | +3.8% / +16.5% |
| QQQ 3m / 1y | +4.7% / +21.7% |
Technicals
TSLA technicals as of 2026-10-15: last close $362.44; 20d SMA 370.81 (bullish); 50d SMA 358.76; 12d EMA 371.03; 26d EMA 368.19; RSI 14 44.1 (balanced); 20d vol 30.7%; volume x0.8 vs 20d avg
Next earnings: 2027-01-26 AMC
Sources (32 · T1 = primary filings)
- T2http://rmb.reuters.com/rmd/rss/item/tag:reuters.com,2026:newsml_KBN3VI1B6?channel=frL012
- T4https://finance.yahoo.com/technology/ai/articles/kimbal-musk-says-tesla-cybercab-033013115.html
- T4https://www.hudson-labs.com/research/tesla-q3-2026-earnings-preview-tsla-revenue-margins-outlook
- T4https://teslanorth.com/2026/10/14/tesla-q3-2026-earnings-questions/
- T4https://www.investors.com/news/tesla-cybercabs-nhtsa-investigation-elon-musk-robotaxi-ev-model-y/
- T4https://www.roadandtrack.com/news/a74108053/tesla-robotaxi-nhtsa-school-zone-speeding-allegation/
- T4https://finance.yahoo.com/markets/stocks/articles/fantastic-news-tesla-stock-investors-100501621.html
- T4https://www.automotiveworld.com/news/school-zone-petition-adds-to-teslas-robotaxi-probe-pile/
- T4https://cnevpost.com/2026/10/13/china-nev-market-share-sept-2026-byd-tesla/
- T4https://www.mercurynews.com/2026/06/11/teslas-robotaxi-falls-short-with-long-waits-and-stalled-rides/
- T4https://economictimes.indiatimes.com/tech/technology/waymo-launches-fully-autonomous-robotaxis-in-miami-to-exp…
- T4https://www.latimes.com/business/story/2026-05-29/teslas-robotaxi-dreams-lag-far-behind-waymo
- T4https://www.marketscreener.com/news/tesla-s-china-made-ev-sales-extend-growth-streak-but-momentum-fades-ce7858…
- T4https://finance.yahoo.com/markets/stocks/articles/alphabet-robotaxi-stock-buy-waymo-093702345.html
- T4https://finance.yahoo.com/markets/stocks/articles/tesla-sustain-china-ev-sales-122000323.html
- T4https://cnevpost.com/2026/10/13/china-nev-export-share-sept-2026/
- T3https://global.morningstar.com/en-gb/stocks/tesla-stock-is-down-nearly-20-this-year-is-it-buy-ahead-earnings
- T4https://ca.finance.yahoo.com/news/jefferies-raises-tesla-price-target-144400027.html
- T4https://stockanalysis.com/stocks/tsla/
- T4https://www.thecerbatgem.com/2026/10/15/teslas-tsla-sell-rating-reaffirmed-at-glj-research-2.html
- T4https://sg.finance.yahoo.com/news/tesla-target-lowered-analysts-worried-203300332.html
- T4https://beinsure.com/news/tesla-stock-price-forecast/
- T4https://www.marketbeat.com/stocks/NASDAQ/TSLA/forecast/
- T4https://public.com/stocks/tsla/forecast-price-target
- T2https://www.reuters.com/business/autos-transportation/tesla-posts-stronger-than-expected-quarterly-deliveries-…
- T4https://finance.yahoo.com/markets/stocks/articles/tesla-posts-486-532-q3-105000042.html
- T1https://ir.tesla.com/press-release/tesla-third-quarter-2026-production-deliveries-and-deployments
- T4https://www.stocktitan.net/sec-filings/TSLA/8-k-tesla-inc-reports-material-event-750c0543f755.html
- T1https://ir.tesla.com/press-release/delivery-consensus-third-quarter-2026
- T3https://www.cnbc.com/2026/10/02/tesla-tsla-q3-2026-vehicle-delivery-production.html
- T4https://newscord.org/article/tesla-reports-486532-q3-deliveries-energy-storage-deployments-rise-to-137-gwh--St…
- T4https://finance.yahoo.com/markets/stocks/articles/delivery-outlook-shows-tesla-tsla-171443015.html
Earlier and later calls on TSLA
- Oct 19, 2026Low bar — margins and robotaxi decide.Lean bearish
Want a fresh look at TSLA, or another name?
Queue a new deep-research run. Published to the feed when done.
Automated research opinion, published as-is on Oct 16, 2026. Not personalised advice. Figures use end-of-day closes.