Low bar — margins and robotaxi decide.
Thesis
Bull case
The bar is low and pre-cut: estimates already embed -15% EPS and -32% pretax profit, deliveries beat, and the stock is +4% into the print on heavy volume with RSI neutral. If auto gross margin ex-credits holds ≥17%, the FY27 EPS cut-cycle stops, the ~$405 average target (14% up) becomes the anchor, and any concrete Cybercab production timeline or robotaxi fleet/utilization metrics re-rates the autonomy option that constitutes most of the $1.46T valuation. Energy storage growth and resilient FY27 revenue guidance (~14%) would confirm Tesla is outgrowing the post-tax-credit air pocket. Tesla has repeatedly re-rated on narrative alone, and vol at the 8th percentile means positioning is not stretched.
Bear case
Everything good is already known: the delivery beat is two weeks old and FY estimates were already raised, yet EPS estimates kept falling — the marginal buyer has no new volume catalyst. At 155–182x forward earnings with net income down ~75% from 2023, regulatory credits nearly gone, a China price war, and a fresh NHTSA probe, the downside lever is multiple compression on deteriorating fundamentals; the upside requires unproven robotaxi/Optimus milestones that even prediction markets price at ~7% for year-end. Goldman's $360 target below the market price formalizes this: rising AI capex with no monetization offset caps earnings even if revenue beats. A margin print below 16.5% or any Cybercab/Optimus timeline walk-back likely triggers a downside move toward the low end of the implied range and beyond, given the stock's -39% max drawdown over the past year.
What would change our mind
- If auto gross margin ex-credits holds ≥17% AND management gives verifiable Cybercab production dates plus robotaxi fleet/utilization metrics, the bearish lean is wrong — the cut-cycle stops and the narrative re-rates
- If FY27 guidance confirms ≥13.9% revenue growth with stable margins, the EPS-cut thesis is invalidated
- If the stock sells off >10% post-print on a margin miss while FY27 EPS estimates fall below ~$2.00, the bearish view has played out and should be reassessed rather than pressed
- If FSD subscription revenue or robotaxi operating metrics are disclosed and material, the 'no autonomy revenue' premise of the bear case weakens
Since publication vs SPY · closed horizons are frozen
The full research everything the view rests on
Direct answer to the question asked
Where the edge would come from
What the price assumes
Consensus: revenue ~$27.8–27.9B (-0.8% YoY), adjusted EPS ~$0.43–0.45 (-15% YoY), pretax profit ~$1.72B (-32% YoY), automotive gross margin ~17.3%. Options imply a 6.3–7.5% one-day move vs a 5.95% average absolute move over the last four reports. Street: Moderate Buy, 14 Buy / 11 Hold / 2 Sell, average PT ~$405 (~14% upside), but Goldman at Neutral/$360 sits below the current price and Morgan Stanley is a Hold at $400. Crucially, Q3 deliveries (486.5k, beat) are already known, so volume surprise is largely exhausted — expectations are pre-cut on EPS but intact on FY27 revenue growth (~13.9%).
Why the market may be wrong
Two directions. Consensus may be too pessimistic on margins: deliveries beat with FY estimates raised, energy storage is scaling (13.7 GWh despite missing consensus), and 20-day realized vol is at the 8th percentile of the past year — a coiled setup if margin holds and robotaxi metrics land. More likely, consensus is too optimistic on the timeline: FY27 still assumes ~14% revenue growth and EPS of $2.16–2.20 despite four consecutive quarters of revenue-over-margin evidence (revenue beats alongside EPS misses, including Q2's $0.33 vs ~$0.54), collapsing regulatory credits, the US tax-credit expiry, and a China market that contracted 20% in H1 2026. The extreme forward multiple means the stock only holds if the autonomy narrative converts to numbers — prediction markets assign ~7% odds to public Optimus availability by end-2026, suggesting even bulls' milestones are soft.
The one thing to watch
The delivery beat is public, FY26 delivery estimates were raised — and EPS estimates kept falling anyway. Volume and earnings expectations have decoupled, so the variable that matters on Oct 21 is not EPS vs the $0.44 bar but automotive gross margin ex-credits: it is the single number that determines whether the FY27 EPS cut-cycle (down ~15% in 90 days) stops. An EPS beat driven by credits or one-offs would leave the downtrend in estimates intact; a margin hold ≥17% ex-credits — or a miss below ~16.5% — is what actually re-prices the stock.
Key evidence (12)
- Q3 2026 deliveries 486,532 vs ~457–462k consensus — a beat, but -2.1% YoY vs the tax-credit-rush quarter [T1 IR press release; T2 Reuters, Oct 2, 2026]
- FY26 delivery estimates raised from 1.65M (June) to ~1.82M — the volume good news is already in consensus [T2 Reuters]
- Energy storage deployments 13.7 GWh vs ~15.9 GWh consensus — a miss [T1/T4 aggregation]
- Q2 2026 adjusted EPS $0.33 vs ~$0.54 consensus; revenue has beaten 4 straight quarters while EPS misses — persistent volume-over-margin pattern [T4 previews, multiple]
- FY27 EPS consensus cut ~13–16% over 90 days ($2.52–2.56 → $2.16–2.20); 19 downward vs 4 upward revisions in 30 days [T4 consensus aggregators, Oct 2/8 2026 — moderately sourced]
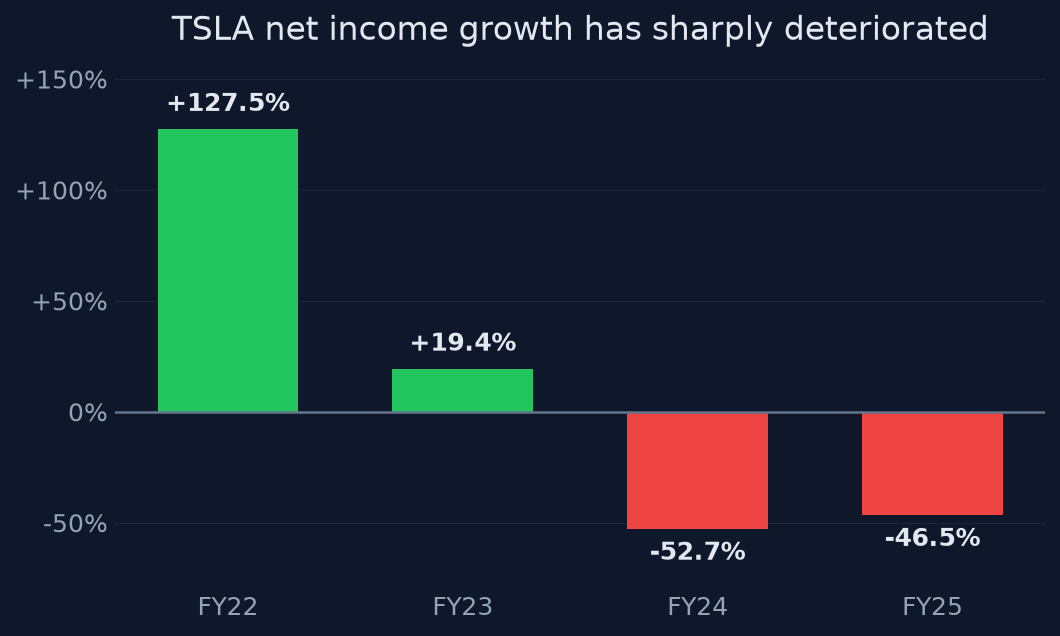
- Net income $15.0B (2023) → $7.1B (2024) → $3.8B (2025); operating margin 4.6% in 2025 [T1 SEC XBRL]
- Regulatory credit revenue $146M in Q2 2026 vs $439M a year earlier — a pure-margin headwind [T4, company-filing-derived]
- Forward P/E ~155–182x on FY26 EPS ~$1.77; market cap ~$1.46T [T1 SEC + T4 market data]
- Stock -18.5% over 1y vs SPY +14.8%; -27.6% below 52w high; 20d vol at 8th percentile of past year [market data, Oct 16–19 2026]
- Goldman Sachs Neutral/$360: print matters less than FSD/robotaxi/Optimus updates; Morgan Stanley Hold/$400; consensus Moderate Buy, avg PT ~$405 [T4 aggregation — flag as moderately sourced]
- New October 2026 NHTSA evaluation of Cybercab/Model Y automated driving in school zones; robotaxi in only 7 metros by Q2-end; Cybercab limited Austin service [T2-adjacent + T4]
- China auto market -20% H1 2026; Chinese hybrid exports to EU tripled to $7.5B H1 2026, circumventing EV tariffs [T2 Reuters]
Catalysts and risks
Catalysts
- Q3 2026 earnings after close Wed Oct 21, 2026; webcast 5:30pm ET — auto gross margin ex-credits is the key number
- Management commentary on Cybercab production timeline and robotaxi city-expansion/fleet targets on the call
- FY27 revenue growth guidance vs the ~13.9% consensus assumption
- NHTSA school-zone probe developments (October 2026 onward)
- FSD Supervised approvals in additional European markets; FSD subscription/attach-rate disclosure
- Third-generation Optimus production start targeted before year-end 2026
- China price-war trajectory and EU-China hybrid export agreement implementation
Risks
- Auto gross margin ex-credits below ~16.5% confirms the volume-over-margin structural decline
- Rising AI/robotics capex and opex with no monetization offset (Goldman's stated concern) compresses FCF
- Regulatory setback from the NHTSA probe or FSD naming/approval issues in Europe hits the autonomy narrative that carries the multiple
- Energy-storage miss proves demand-driven rather than timing, removing a growth offset
- China market contraction (-20% H1 2026) and BYD/hybrid competition force further price cuts
- Sell-the-news dynamic: delivery beat already priced, stock +4% into the print, EPS bar pre-cut — limited upside catalyst from the numbers alone
- Valuation risk is permanent, not event-specific: 155–182x forward earnings leaves no margin of safety if milestones slip
What to watch
- Automotive gross margin excluding regulatory credits vs the ~17.3% preview — the single most important line
- Q3 regulatory-credit revenue (Q2 was $146M) and how much of any EPS beat is credit-driven
- AI/robotics capex and opex trajectory vs free cash flow
- Robotaxi: number of metros, fleet size, paid rides/utilization, safety data; Cybercab production start date
- FSD subscription/attach-rate disclosure and European approval cadence
- Energy storage: whether the 13.7 GWh miss is described as timing or demand
- FY27 EPS consensus revisions in the two weeks post-print — continuation of the down-cycle vs stabilization
- NHTSA probe headlines and any Cybercab/Optimus timeline language changes vs prior 'end-2026' targets
Market snapshot when the call was made 2026-10-16
Price
| Return 1w | -7.3% |
| Return 1m | -3.1% |
| Return 3m | -4.0% |
| Return 6m | -11.5% |
| Return 1y | -18.5% |
| From 52-week high | -27.6% |
| Realized vol, 20d | 31.4% |
| SPY 3m / 1y | +2.9% / +14.8% |
| QQQ 3m / 1y | +2.0% / +17.9% |
Technicals
TSLA technicals as of 2026-10-16: last close $354.72; 20d SMA 370.33 (bullish); 50d SMA 359.46; 12d EMA 368.52; 26d EMA 367.22; RSI 14 48.2 (balanced); 20d vol 29.3%; volume x1.8 vs 20d avg
Verifier notes REVISE · opinion revised once
Unsupported claims
- The opinion twice claims a FIVE-quarter pattern: 'five consecutive quarters of volume-over-margin evidence' (why_market_may_be_wrong) and 'five quarters of EPS misses' (why_this_matters). The evidence supports only FOUR: 'Tesla reportedly exceeded revenue estimates in each of the prior four quarters,' with one explicit EPS miss documented (Q2 2026 $0.33 vs ~$0.54). The opinion's own key_evidence bullet says 'revenue has beaten 4 straight quarters.' No evidence establishes a fifth consecutive quarter of EPS misses.
Corrections applied
- Change both instances of 'five' to 'four': 'five consecutive quarters of volume-over-margin evidence' → 'four consecutive quarters of volume-over-margin evidence' and 'five quarters of EPS misses' → 'a run of EPS misses over the past four quarters (including Q2's $0.33 vs ~$0.54)'. All other figures verified against evidence: revenue/EPS consensus ranges, 6.3–7.5% implied move vs 5.95% average, 486,532 deliveries vs ~457–462k, FY26 deliveries 1.65M→1.82M, FY27 EPS $2.16–2.20 from $2.52–2.56 (13–16% cut), 19 down/4 up revisions, net income $15.0B→$3.8B (down ~75% ✓), 155–182x forward P/E on FY26 EPS ~$1.77, $146M vs $439M credits, 17.3% preview margin, $405 avg PT / $360 GS / $400 MS, 14/11/2 ratings, vol 8th percentile, -39% max drawdown, ~7% Optimus prediction-market odds, LEAN_BEARISH at conviction 5 is within the 5–6 band, and invalidation conditions are falsifiable.
Sources (26 · T1 = primary filings)
- T1https://ir.tesla.com/press-release/tesla-third-quarter-2026-production-deliveries-and-deployments
- T1https://ir.tesla.com/
- T2https://www.reuters.com/business/autos-transportation/tesla-posts-stronger-than-expected-quarterly-deliveries-…
- T4https://www.teslarati.com/tesla-q3-earnings-say-questions/
- T4https://www.cmcmarkets.com/en-nz/market-news/the-week-ahead-oil-meta-and-tesla-earnings
- T4https://markets.businessinsider.com/news/stocks/will-tesla-s-q3-earnings-help-tsla-stock-recover-here-s-what-a…
- T4https://www.perplexity.ai/finance/TSLA/earnings
- T4https://www.basenor.com/blogs/news/spacex-and-tesla-both-report-q3-2026-earnings-this-week
- T4https://www.investors.com/news/tesla-elon-musk-robotaxi-cybercab-optimus-electric-vehicle/?src=A00331A&refcode…
- T4https://scanx.trade/stock-market-news/companies/tesla-q3fy26-results-musk-says-robots-will-drive-most-value/53…
- T2https://www.bloomberg.com/news/articles/2026-10-06/tesla-to-showcase-its-cybercab-robotaxi-at-paris-auto-show
- T4https://applescoop.org/story/tesla-q3-2026-earnings-october-21-what-to-watch
- T4https://stockstotrade.com/news/tesla-inc-tsla-news-2026_10_16-2/
- T4https://scanx.trade/stock-market-news/technology/tesla-drops-full-self-driving-name-europe-assisted-driving/53…
- T4https://finance.yahoo.com/markets/stocks/articles/tesla-robotaxis-fsd-optimus-outlook-135634668.html
- T2http://rmb.reuters.com/rmd/rss/item/tag:reuters.com,2026:newsml_KBN3VS0GC?channel=frL012
- T2http://rmb.reuters.com/rmd/rss/item/tag:reuters.com,2026:newsml_KBN3VS0CC?channel=frL012
- T4https://money.usnews.com/investing/news/articles/2026-10-12/chinas-7-5-billion-eu-hybrid-boom-faces-new-curbs-…
- T4https://www.tipranks.com/news/the-fly/gm-ford-seen-reporting-in-line-to-slightly-better-q3-prints-thefly-news
- T4https://www.piptheory.com/research/tesla-q3-2026-deliveries-preview-production-gap
- T4https://note.com/bloomo_economics/n/nf452e79cf4e2?hl=en
- T4https://www.japantimes.co.jp/business/2026/10/12/china-hybrid-eu-curbs/
- T3https://www.cnbc.com/2026/07/28/ford-motor-f-earnings-q2-2026.html
- T1https://ir.tesla.com/press
- T4https://www.mexc.com/learn/article/tesla-earnings-date-time-results-history
- T4https://www.teslabriefing.com/en/articles/stock-q3-earnings-call-oct21-confirmed-2026-10-02
Earlier and later calls on TSLA
- Oct 16, 2026Priced for a future not yet visible.Lean bearish
Want a fresh look at TSLA, or another name?
Queue a new deep-research run. Published to the feed when done.
Automated research opinion, published as-is on Oct 19, 2026. Not personalised advice. Figures use end-of-day closes.