No — the rally outran the evidence.
Thesis
Bull case
The ad franchise is compounding at 28% with AI tools (Advantage+) demonstrably driving monetization faster than Google's, and Meta is on track to become the largest digital ad seller in 2026. At ~21x FY27 EPS of $34.39, the stock is not expensive if capex plateaus in 2027 — FCF would improve mechanically on the capex line, though the magnitude of any recovery also depends on operating expenses, taxes, and working capital, and no evidence-supported full-year FCF forecast exists in the bundle. Muse then becomes free optionality on a consumer-AI platform with 3.6B daily users as distribution. A clean Q3 (if the market-estimated Oct 28 date holds) with stable capex language and any Muse revenue disclosure could push the stock through the (weakly sourced) ~$794 consensus target and toward new highs.
Bear case
The stock added ~$200B+ of market cap in a month amid AI enthusiasm around a product with no disclosed revenue, a security incident, and a retracted feature — while a T4 feed showed EPS estimates being cut, Q2 FCF printed at ~$784M, Reality Labs posted ~$4.62B of quarterly operating losses, and ~$27B of Hyperion development costs were financed through an 80/20 JV in which Meta does not borrow directly. If the Q3 report brings 2027 capex signals above $145B or another EPS miss, the market reprices the FCF recovery out a year and the multiple compresses; at 18x FY26 EPS of $31 the stock is ~$558 and at 18x FY27 EPS of $34.39 it is ~$619 — roughly $560-$620, or 15-23% downside (note: the 18.3x early-September multiple used to anchor this scenario is itself T4-only, so treat the range as illustrative). That compares with ~9% upside to a T4-only consensus target. EU DMA, child-safety litigation, and antitrust remain unpriced tail risks.
What would change our mind
- Q3 2026 report (if the ~Oct 28 market-estimated date holds) shows FCF recovering materially from the ~$784M Q2 trough — e.g., above ~$5B/quarter [analyst-defined decision rule, not evidence-derived] — AND capex commentary implies flat-to-down 2027 spending vs 2026; this would validate the 'temporary trough' bull case and undermine the bearish multiple-compression view
- Muse discloses meaningful revenue or paid-subscriber scale — e.g., >$1B annualized run-rate [analyst-defined decision rule, not evidence-derived] — converting the narrative premium into earnings
- FY27 EPS estimates are revised UP after Q3 while the stock holds ~23x — indicating the multiple expansion is being validated by fundamentals rather than diverging from them
Since publication vs SPY · closed horizons are frozen
The full research everything the view rests on
Direct answer to the question asked
Where the edge would come from
What the price assumes
At ~23.5x FY26 consensus EPS of ~$31 and ~21x FY27 EPS of ~$34.39, the market is paying a full megacap multiple (roughly in line with Alphabet) for ~20%+ revenue growth plus meaningful AI-monetization optionality. The September rally prices Muse as a credible new revenue engine before any revenue disclosure, and the price implies investors believe the weak Q2 2026 FCF print (~$784M) is a temporary investment trough rather than a structural reset — though the evidence does not yet establish either.
Why the market may be wrong
The market may be wrong in both directions, but the more probable near-term error is overpaying for narrative: the +23% move coincided with EPS estimate cuts (a T4 feed shows 2 up vs 9 down revisions — directional, not established), meaning the re-rating was largely multiple expansion amid AI enthusiasm rather than earnings-driven — historically the most fragile kind of rally. That said, the rally also had support from strong advertising growth, positive revenue revisions, and a broad AI-sector lift, so Muse cannot be isolated as the sole driver. The bearish error would be underestimating how quickly Meta's AI ad tools are already converting capex into 28% revenue growth and a projected overtake of Google in 2026 digital ad share; if Q3 shows FCF inflecting, the 'capex with no payoff' bear case weakens materially.
The one thing to watch
The single variable that matters most now is not revenue growth or Muse downloads — it is any 2027 capex language management may offer on the Q3 call: Meta declined to give a 2027 figure in July, Q2 FCF was only ~$784M against $31B+ quarterly capex, and the stock's September re-rating assumes that trough is temporary. There is no guarantee management will disclose a formal 2027 number at the next report — but if it signals 2027 capex growth above ~$145B, the market must reprice FCF recovery out another year and the multiple compresses; if capex plateaus while revenue grows 20%+, the FCF picture improves mechanically on the capex line alone (though opex, taxes, and working capital also matter). Watch the capex sentence, not the EPS beat/miss.
Key evidence (11)
- Q2 2026 (Jul 29, 2026): revenue $60.8B +28% YoY, fastest since 2021; but EPS $6.18 missed $7.22 consensus on legal charges/severance; operating income fell 8% YoY [Reuters T2; Meta IR T1]
- Q2 2026 free cash flow was ~$784M after >$31B of Q2 capital expenditures; FY2026 capex guidance is $130-145B [T1/T4; Meta IR T1; Reuters T2]
- 2026 expenses guided to $165-169B; management declined to provide a 2027 capex figure [Meta IR T1; Reuters T2, Jul 2026]
- FY26 EPS consensus revised down ~$32.91 to ~$31 over 3 months while revenue revisions were positive; a T4 feed shows 2 up vs 9 down EPS revisions and 45 up vs 13 down revenue revisions — directional only [MarketWatch T3; Seeking Alpha T4]
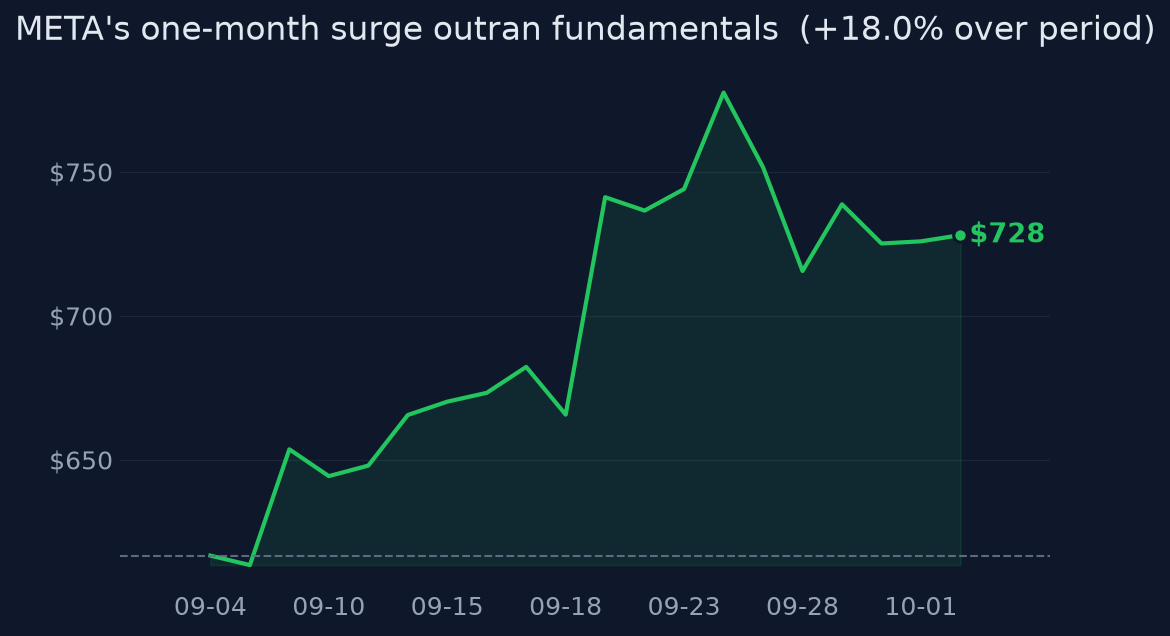
- Stock +22.8% in 1 month (z-score +2.04, 20d vol 55% at 97th percentile of 1y), but only +1.5% over 1y with a -30.1% max drawdown [market data, 2026-10-02]
- Muse AI agent (launched Sep 8, 2026): 2.8M downloads, briefly topped ChatGPT in US/Canada app stores; subscriptions $20/$100 are 'extra features only'; no disclosed revenue; human-concierge feature rolled back over disclosure failures; security vulnerability forced stronger warnings; Reuters Breakingviews called it 'value destruction' [Reuters T2, Sep 2026]
- Reality Labs operating losses reduced 2025 operating profit by ~$19.2B; Q2 2026 RL operating loss ~$4.62B on $431M revenue; 2026 operating losses guided similar to 2025 [SEC 10-Q T1]
- Hyperion data center JV: ~$27B of total development costs, funded 80% by Blue Owl with Meta retaining 20%; ~$26B of debt expected via PIMCO and other bond investors; Meta is not borrowing the financing directly [Meta IR T1; Reuters T2]
- Meta projected to surpass Google in 2026 digital ad revenue ($243.5B vs $239.5B, +24.1% vs +11.9% growth) [eMarketer via Reuters T2, Apr 2026]
- Consensus price target ~$794 vs $728 implies ~9% upside [T4 — weakly sourced; treat as directional only, not a reliable basis for risk/reward quantification]
- Forward P/E ~23.2-23.5x FY26 EPS [Zacks/MarketBeat T4, Sep-Oct 2026]; 2025 net income fell to $60.5B from $62.4B despite operating income rising to $83.3B [SEC XBRL T1]
Catalysts and risks
Catalysts
- Q3 2026 earnings report — market-estimated ~Oct 28, 2026 [T4, unconfirmed]; the feed's official next report is Jan 26, 2027 (Q4 2026). Any 2027 capex commentary would be the decisive variable, though Meta may again decline to provide a figure
- Any Muse monetization disclosure (paid subscriber counts, small-business attach rates) — positive or negative depending on magnitude
- FY26/Q4 report Jan 26, 2027 with possible formal 2027 capex and expense guidance
- Regulatory/legal developments: EU DMA enforcement, child-safety trials, US antitrust proceedings
- Analyst estimate revisions in the weeks around the Q3 print — currently trending negative on EPS [T4 feed, directional only]
Risks
- 2027 capex signaled above $145B, extending the FCF trough and forcing multiple compression
- Muse fails to monetize or suffers further safety/privacy incidents, deflating the September narrative premium
- EPS quality issues persist (legal charges, severance) making headline beats/misses noisy
- Reality Labs operating losses remain ~$19B/yr with no narrowing path
- Off-balance-sheet-style JV financing (Hyperion, 80/20 Blue Owl-Meta) reduces visibility into the true cost and risk of the AI buildout if AI sentiment turns
- Regulatory escalation (EU DMA, child safety, antitrust) adds expense and business-model constraints
- Extreme realized volatility (55% 20d, 97th percentile) means position sizing errors are punished quickly
- Key quantitative anchors — the ~$794 consensus target, the 2-up/9-down revision count, and the 18.3x historical multiple — are T4-only; treat as directional, not established fact
What to watch
- Any 2027 capex commentary on the Q3 call (date unconfirmed) — the single most important potential disclosure
- Quarterly FCF print vs the ~$784M Q2 trough
- FY26/FY27 EPS revision direction post-earnings (T4 feed currently shows 2 up vs 9 down)
- Any Muse revenue, subscriber, or enterprise-attach disclosure
- Reality Labs operating loss trajectory vs the ~$4.62B/quarter run rate
- Further JV or off-balance-sheet data center financing announcements
- Insider selling filings while the stock is near highs
- EU DMA and child-safety litigation headlines
Market snapshot when the call was made 2026-10-02
Price
| Return 1w | -3.1% |
| Return 1m | +22.8% |
| Return 3m | +21.3% |
| Return 6m | +26.7% |
| Return 1y | +1.5% |
| From 52-week high | -6.4% |
| Realized vol, 20d | 55.2% |
| SPY 3m / 1y | +2.4% / +15.1% |
| QQQ 3m / 1y | +3.7% / +24.3% |
Technicals
META technicals as of 2026-10-02: last close $728.08; 20d SMA 695.92 (bullish); 50d SMA 625.04; 12d EMA 718.05; 26d EMA 683.49; RSI 14 62.2 (balanced); 20d vol 56.8%; volume x0.5 vs 20d avg
Next earnings: 2027-01-26 AMC
Verifier notes REVISE · opinion revised once
Unsupported claims
- The claims that the "entire" one-month rally rests on Muse and was "pure multiple expansion on an unproven product" overstate the evidence. Reuters supports Muse/AI enthusiasm as a major catalyst, but the bundle also cites a broad AI-sector lift, strong advertising growth, and positive revenue revisions; it does not establish Muse as the sole cause.
- The opinion extrapolates one quarter into a full-year cash-flow thesis. The bundle supports Q2 2026 free cash flow of about $784M after more than $31B of quarterly capex, but not a full-year "2026 FCF collapse," a 2027 recovery toward $60B-$80B, or the assertion that FCF recovery would be "mechanical" if capex plateaus. Operating expenses, taxes and working capital also affect FCF.
- The bear case says "$27B of data center spend was moved off balance sheet." The evidence instead describes roughly $27B of total Hyperion development costs in a new 80/20 Blue Owl-Meta JV, with Meta not borrowing the financing directly. It does not show that $27B of existing Meta spending was moved off its balance sheet or that the full amount represents Meta leverage.
- The descriptions of Reality Labs as "burning ~$19B/yr" and "$4.6B/quarter" conflate operating losses with cash burn. The evidence provides approximately $19.2B of 2025 operating losses and a $4.62B Q2 2026 operating loss, not segment cash-flow figures.
- The 18x downside calculation is wrong. At 18x FY2026 EPS of $31, the value is about $558; at 18x FY2027 EPS of $34.39, it is about $619. Thus the evidence-supported range is approximately $560-$620, representing roughly 15%-23% downside from $728, not $560-$650 and 10%-20% downside.
- The claim that the near-term outcome will be set by "one disclosed number" for 2027 capex is too certain. The evidence only says Meta previously declined to provide a 2027 figure; it does not establish that management will disclose formal 2027 capex guidance at the next report.
- The $5B quarterly FCF and $1B Muse annualized-revenue invalidation thresholds are analyst-selected assumptions rather than figures supported by the evidence. They may be used as decision rules, but should be identified explicitly as such.
Weakly sourced
- October 28, 2026 is repeatedly presented as the earnings date even though the bundle calls it a market-estimated, unconfirmed T4 date and separately lists January 26, 2027 as the next report. Because the thesis is organized around the October event, the date must remain explicitly conditional.
- The approximately $794 consensus price target is supported only by a T4 source. Although the opinion later acknowledges this weakness, it still uses the target prominently to quantify upside and establish asymmetric risk/reward.
- The "2 up vs 9 down" EPS-revision count is from a T4 feed and is central to the claim of pure multiple expansion. The early-September 18.3x valuation reference used to anchor the bearish compression scenario is also T4-only.
Internal inconsistencies
- The final invalidation condition—if the stock falls more than 10% on benign capex language, "the bear thesis is confirmed"—is not an invalidation condition. It describes purported confirmation and price action alone would not establish the bear thesis's fundamental causation.
Corrections applied
- Replace sole-cause language with: "The rally was associated largely with Muse and broader AI-monetization enthusiasm even as EPS estimates declined; the evidence cannot isolate Muse as the sole driver."
- State the periods separately: "Q2 FCF was about $784M after more than $31B of Q2 capex, while FY2026 capex guidance is $130B-$145B." Remove the unsupported $60B-$80B forecast or label it clearly as an analyst scenario with a cash-flow bridge, and do not call recovery mechanical.
- Describe Hyperion as an 80/20 JV financing structure for approximately $27B of development costs, with Meta retaining 20% and not borrowing the financing directly; remove the claim that $27B of Meta spending was moved off balance sheet.
- Replace "cash burn" with "operating loss" for Reality Labs unless segment cash-flow evidence is added.
- Change the 18x valuation range to approximately $560-$620 and the downside to approximately 15%-23%, or provide a separate supported EPS/multiple assumption that produces $650.
- Refer to October 28 only as an unconfirmed market estimate and frame 2027 capex commentary as something management may provide, not a guaranteed disclosed number.
- Treat the $794 target, revision counts and 18.3x historical multiple as weak directional datapoints, or remove them from the core quantitative risk/reward until corroborated by stronger sources.
- Label the $5B FCF and $1B Muse-revenue thresholds as analyst-defined decision rules.
- Move the greater-than-10% stock-decline condition out of invalidation_conditions or replace it with a genuinely thesis-invalidating fundamental outcome.
Sources (39 · T1 = primary filings)
- T1https://investor.atmeta.com/investor-news/press-release-details/2026/Meta-Reports-Second-Quarter-2026-Results/…
- T1https://investor.atmeta.com/investor-news/press-release-details/2025/Meta-Announces-Joint-Venture-with-Funds-M…
- T2https://www.reuters.com/business/meta-narrows-annual-capex-forecast-ai-buildout-grows-2026-07-29/
- T2https://www.reuters.com/business/meta-taps-pimco-blue-owl-29-billion-data-center-expansion-project-source-says…
- T4https://www.globaldatacenterhub.com/p/meta-blue-owls-27b-bet-is-this-the
- T3https://www.marketwatch.com/livecoverage/meta-earnings-stock-results-guidance-a2/card/meta-bumps-up-capex-spen…
- T2https://www.reuters.com/legal/transactional/meta-set-clinch-nearly-30-billion-financing-deal-louisiana-data-ce…
- T4https://www.digitalapplied.com/blog/meta-q2-2026-earnings-ad-strength-capex-selloff
- T4https://www.alphaspread.com/security/nasdaq/meta/investor-relations/earnings-call/q2-2026
- T2https://www.reuters.com/business/wall-street-expects-metas-ai-agent-shape-into-new-revenue-engine-2026-09-22/
- T4https://www.investing.com/news/transcripts/earnings-call-transcript-meta-misses-eps-in-q2-2026-as-stock-sinks-…
- T4https://www.theglobeandmail.com/investing/markets/stocks/META/pressreleases/3729590/meta-meta-q2-2026-earnings…
- T3https://www.cnbc.com/2026/09/30/meta-stock-best-month-2013-ai.html
- T4https://www.perplexity.ai/finance/META
- T4https://www.theglobeandmail.com/investing/markets/stocks/META/pressreleases/1604248/meta-meta-q1-2026-earnings…
- T4https://www.investing.com/analysis/meta-stock-pullback-exposes-risk-behind-a-30-monthly-rally-200688541
- T2https://www.reuters.com/business/media-telecom/meta-poised-surpass-google-digital-ad-revenue-first-time-report…
- T4https://www.investing.com/news/stock-market-news/meta-earnings-analysis-questions-answered-and-next-catalysts-…
- T2https://www.reuters.com/business/finance/metas-fall-shows-punters-crave-clearer-ai-payoff-2026-04-30/
- T4https://economictimes.indiatimes.com/tech/technology/meta-poised-to-surpass-google-in-digital-ad-revenue-for-f…
- T2https://www.reuters.com/business/meta-expects-annual-capital-expenditures-rise-superintelligence-push-2026-01-…
- T2https://www.reuters.com/business/google-quarterly-cloud-revenue-growth-beats-expectations-2026-07-22/
- T4https://www.investing.com/news/stock-market-news/meta-platforms-stock-rerate-candidate-at-183x-forward-earning…
- T4https://x.com/rohanpaul_ai/status/2044083185441747385
- T1https://www.sec.gov/Archives/edgar/data/1326801/000162828026028526/meta-20260331.htm
- T1https://www.sec.gov/Archives/edgar/data/1326801/000162828026050705/meta-20260630.htm
- T1https://www.sec.gov/Archives/edgar/data/1326801/000162828026050596/meta-06302026xexhibit991.htm
- T4https://admiralmarkets.com/education/articles/shares/meta-stock-analysis-october-2026
- T4https://www.stocktitan.net/sec-filings/META/8-k-meta-platforms-inc-reports-material-event-a1bd36b6ca44.html
- T4https://www.stocktitan.net/sec-filings/META/10-q-meta-platforms-inc-quarterly-earnings-report-393f7af5508d.htm…
- T4https://www.stocktitan.net/sec-filings/META/10-q-meta-platforms-inc-quarterly-earnings-report-3bd7ce5dd651.htm…
- T1https://www.sec.gov/Archives/edgar/data/1326801/000162828026003832/meta-12312025xexhibit991.htm
- T2https://www.reuters.com/business/meta-testing-human-concierge-its-new-personal-ai-agent-muse-2026-09-22/
- T2https://www.reuters.com/technology/meta-bolsters-muse-safety-warning-after-security-vulnerability-found-inform…
- T2https://www.reuters.com/business/finance/metas-muse-rekindles-fears-over-winners-losers-personal-ai-agent-emer…
- T2https://www.reuters.com/business/media-telecom/meta-expands-muse-ai-agent-small-businesses-2026-09-29/
- T2https://www.reuters.com/business/meta-launches-ai-agent-that-can-access-other-apps-send-emails-make-payments-2…
- T2https://www.reuters.com/business/media-telecom/metas-charm-gadget-carries-ceo-zuckerbergs-big-ai-ambitions-202…
- T2https://www.reuters.com/video/watch/idRW491123092026RP1/
Earlier and later calls on META
- Oct 19, 2026Capex, not revenue, decides.No clear edgeview changed
- Oct 13, 2026No edge until Oct 21.No clear edgeview changed
- Aug 17, 2026Buy, but small and patient.Lean bullishview changed
Want a fresh look at META, or another name?
Queue a new deep-research run. Published to the feed when done.
Automated research opinion, published as-is on Oct 4, 2026. Not personalised advice. Figures use end-of-day closes.