Buy, but small and patient.
Thesis
Bull case
Core ads +28% y/y with AI improving ranking/targeting/pricing; Q2 'miss' is an artifact of $3.6B one-time charges (underlying beat); Q3 guide $61-64B straddles consensus; at ~18.6x forward — a trough versus its own recent range — with estimates already cut, even a partial FCF recovery + a manageable legal outcome re-rates the stock toward the low-20s P/E — 25-30% upside to mid-$700s targets. Meta has done this exact pivot before (2022).
Bear case
This capex cycle is structurally different: $130-145B FY26 with no 2027 guidance and hyperscalers projected to outspend FCF by 2027 means buybacks stay suspended and depreciation is only beginning to hit margins (Q2 2026 operating margin already ~31% vs 41.4% FY2025, partly one-time items); +55% expense growth vs +28% revenue makes the +35% FY26 EPS consensus look stale, so 'cheap' may rest on numbers that get cut again. Add a live trial with claimed penalties near market cap — an unquantifiable tail the market rationally refuses to underwrite — plus EU margin headwinds.
What would change our mind
- Q3 2026 FCF stays below ~$5B while revenue growth decelerates under ~15% — that would confirm structural re-rating, not a timing bulge
- FY27 consensus EPS cut below ~$32 (another ~6%+ cut) while the stock holds current levels — proving the cheap multiple was an artifact of stale estimates
- A youth-safety verdict/settlement in the tens of billions or with engagement-limiting remedies (e.g., mandated design changes for minors)
- Company guides 2027 capex above $150B with no credible FCF recovery path
Since publication vs SPY · closed horizons are frozen
The full research everything the view rests on
Direct answer to the question asked
Where the edge would come from
What the price assumes
The current ~$577-590 price appears to assume the capex cycle is structurally different this time — i.e., FCF does not recover, buybacks stay suspended, and FY26 EPS consensus ($31.71) faces further cuts. The 25% gap below consensus price targets (~$746-768) shows the market has already rejected the Street's patience on AI payback.
Why the market may be wrong
The market is extrapolating a single quarter's FCF collapse as permanent while discounting that (1) the Q2 'miss' was ~$1.2-1.4/share of one-time legal and severance charges — underlying EPS was likely ~$7.4-7.6, above consensus; (2) Meta has a demonstrated willingness (2022 'year of efficiency') to pivot to discipline when shareholders revolt; and (3) the $1.4T legal figure is a claimed ceiling that Meta calls unsupported, while actual verdicts to date ($375M NM, $6M CA bellwether) are tiny relative to cash generation. Sentiment, not fundamentals, is doing most of the work.
The one thing to watch
Stop watching EPS — watch quarterly FCF. The entire debate collapses to whether Q2 2026's $784M FCF was a capex timing bulge or the new run-rate: if Q3 2026 FCF recovers to even half of Q1's $12.4B while revenue stays >20% growth, the 'miss and guide-down' narrative that drove the de-rating is falsified at the same time estimates have already been cut, which is the classic setup for multiple expansion rather than deterioration.
Key evidence (8)
- Q2 2026 (reported Jul 29, 2026): revenue $60.8B vs $60.2B consensus (beat); EPS $6.18 vs $7.22 (miss) — but includes $2.4B legal charges + $1.18B severance (T1 Meta IR; T3 CNBC)
- FY2025 SEC XBRL: revenue $201B (+22%), operating margin 41.4%, EPS $23.49; Q2 2026 total expenses +55% y/y to $42B, implying Q2 2026 operating margin compressed to ~31% ($18.78B on $60.8B) (T1 SEC/T1 Meta IR)
- FCF collapse: Q1 2026 FCF $12.39B (T1 investor release) to Q2 2026 FCF $784M (T2 Reuters, Jul 2026); FY2026 capex guided $130-145B (T2 Reuters)
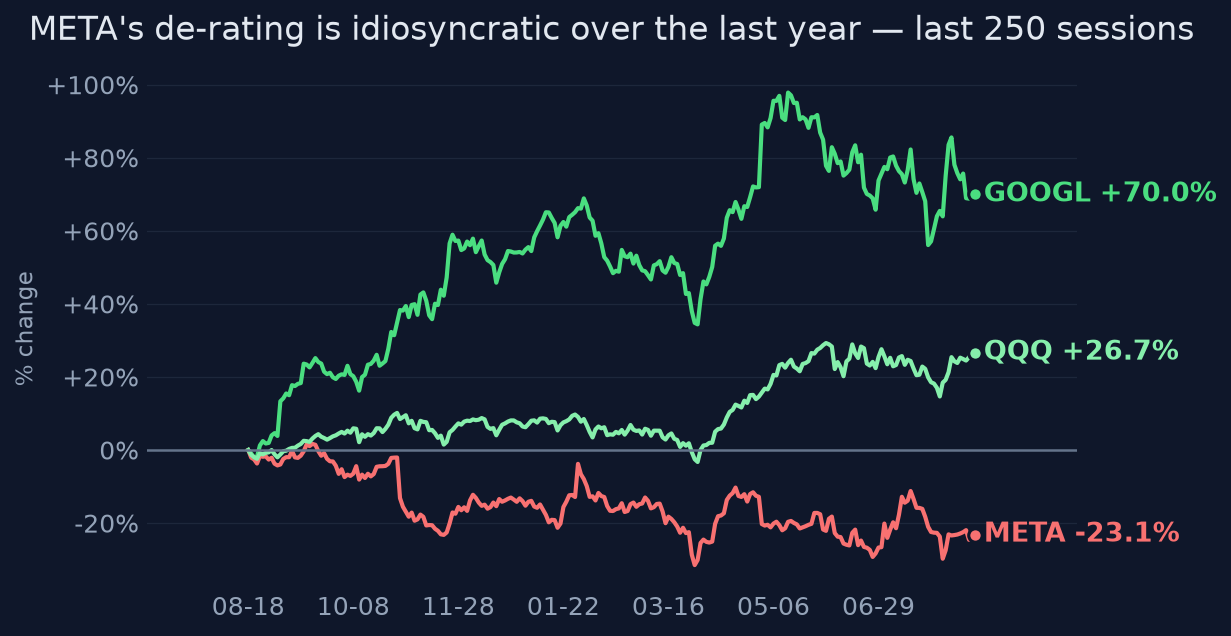
- Price: -24.4% 1y, -25% below 52w high, max drawdown -33.5%, realized vol ~45%; GOOGL +71% 1y over the same window — idiosyncratic repricing (computed price history, Aug 14, 2026)
- Valuation: ~18.6x FY26 consensus EPS $31.71; estimates cut over 3 months (FY26 $32.81→$31.71, FY27 $34.85→$33.96) (T4 — historical P/E range claim weakly sourced and approximate)
- Street: consensus targets ~$746-768, ~55 of 62-65 analysts at Buy, virtually no Sells (T4)
- Legal: 29-state youth-safety trial heading to court Aug 2026 (T2 Reuters, Aug 12, 2026); states' claimed penalties up to $1.4T per Meta (disputed); verdicts to date $375M NM, $6M CA; FTC appealing antitrust loss (T2)
- Buyback reportedly suspended during the period (T4 filing snapshot — not verified against 10-Q)
Catalysts and risks
Catalysts
- 29-state youth-safety trial proceedings and any verdict/settlement (live as of Aug 2026)
- Q3 2026 earnings (~late Oct 2026): FCF print, any 2027 capex commentary, expense trajectory
- FTC antitrust appeal developments
- AI monetization disclosure — any quantification of Meta AI/Llama revenue contribution
- Resumption or formal update on buyback authorization
- Analyst estimate revisions into Q3 print (already trending down)
Risks
- Youth-safety litigation resolves at structural-remedy or multi-billion damages levels rather than manageable dollars
- 2027 capex guided higher than the $130-145B FY26 level, confirming permanent FCF compression
- FY26/FY27 EPS consensus cut again as AI depreciation flows through, undermining the 18.6x 'cheap' frame
- Ad demand macro sensitivity if economy softens into late 2026
- EU DMA-driven ad pricing changes compress European margins
- Buyback suspension extends, removing a key downside support mechanism
What to watch
- Quarterly FCF vs capex ratio (Q3 print) — the single decisive variable
- 2027 capex language on the Q3 call
- State trial news flow: settlement signals, bellwether outcomes, remedy scope
- FCF-based valuation vs consensus EPS cuts — whether the gap between price and targets narrows via stock up or targets down
- Buyback resumption announcements
- Ad pricing/impression growth commentary as evidence AI is monetizing through the core business
Market snapshot when the call was made 2026-08-14
Price
| Return 1w | -0.4% |
| Return 1m | -11.2% |
| Return 3m | -4.6% |
| Return 6m | -9.2% |
| Return 1y | -24.4% |
| From 52-week high | -25.3% |
| Realized vol, 20d | 45.2% |
| SPY 3m / 1y | +3.8% / +20.4% |
| QQQ 3m / 1y | +1.6% / +26.0% |
Technicals
META technicals as of 2026-08-14: last close $589.85; 20d SMA 594.67 (neutral); 50d SMA 597.13; 12d EMA 591.46; 26d EMA 596.98; RSI 14 48.8 (balanced); 20d vol 44.7%; volume x0.6 vs 20d avg
Verifier notes REVISE · opinion revised once
Weakly sourced
- '~18.6x forward earnings — the cheapest of mega-cap tech' (answer section): the bundle contains no peer forward P/E multiples (no GOOGL/MSFT/AMZN valuation data appears anywhere in the evidence), so the superlative 'cheapest of mega-cap tech' is unsupported by the collected data. Only the 18.6x META multiple itself and a [T4]-sourced, self-flagged-as-approximate historical-range claim are evidenced.
- Present-tense '41% operating margins' paired with Q2 2026's ~28% revenue growth in the direct answer: the 41.4% figure is the FY2025 full-year margin (SEC XBRL). Q2 2026 actual operating income was $18.78B on $60.8B revenue ≈ 31% — the evidence explicitly attributes 41.4% to 2025 only. Pairing the two as if contemporaneous materially overstates current profitability in a quarter where margin compression is the central bear point.
Internal inconsistencies
- The direct answer frames current operations as '~28% y/y revenue growth, 41% operating margins' while the bear case (correctly) emphasizes '+55% expense growth vs +28% revenue' and depreciation 'beginning to hit margins' — the 41% figure (FY2025) and the expense-surge reality (Q2 2026, ~31% op margin) belong to different periods and the answer section blurs them.
Corrections applied
- In the answer, rephrase to attribute margins to the correct period, e.g.: 'revenue accelerating to ~28% y/y in Q2 2026 off a 41.4% FY2025 operating margin (Q2 2026 margin compressed to ~31% on one-time charges and the expense surge)'.
- Soften or source the superlative: either drop 'the cheapest of mega-cap tech' or reframe as 'a trough multiple versus its own recent low-to-mid-20s forward P/E range ([T4], approximate)' — the bundle supports the self-referential de-rating claim, not the cross-peer comparison.
- Minor: bear case says hyperscalers 'outspend FCF through 2027' — the Reuters evidence says combined capex exceeds combined FCF 'by 2027'; align the wording ('by 2027') to the source.
Sources (23 · T1 = primary filings)
- T1https://investor.atmeta.com/investor-news/press-release-details/2026/Meta-Reports-Second-Quarter-2026-Results/…
- T4https://variety.com/2026/digital/news/meta-q2-2026-earnings-results-legal-proceedings-charge-1236823577/
- T4https://finance.yahoo.com/m/08413e6f-02e8-3a08-9b34-9426b8aef527/meta-q2-2026-earnings-miss:.html
- T4https://finance.yahoo.com/markets/stocks/articles/meta-shares-drop-q2-profit-203121394.html
- T4https://www.investing.com/news/transcripts/earnings-call-transcript-meta-misses-eps-in-q2-2026-as-stock-sinks-…
- T4https://www.theglobeandmail.com/investing/markets/stocks/META/pressreleases/3729590/meta-meta-q2-2026-earnings…
- T2https://www.reuters.com/business/meta-narrows-annual-capex-forecast-ai-buildout-grows-2026-07-29/
- T2https://www.reuters.com/business/finance/metas-fall-shows-punters-crave-clearer-ai-payoff-2026-04-30/
- T2https://www.reuters.com/business/retail-consumer/metas-ai-splurge-lays-bare-its-compute-conundrum-2026-07-30/
- T4https://cryptodaily.co.uk/2026/07/meta-stock-after-earnings-revenue-vs-cash-burn
- T2https://www.reuters.com/business/ai-investment-boom-puts-big-techs-free-cash-flow-under-pressure-2026-07-22/
- T4https://nilsliu.dev/en/insights/2026-07-30-meta-ai-capex-free-cash-flow/
- T4https://247wallst.com/investing/2026/08/03/meta-price-prediction-analysts-see-40-upside-ahead/
- T4https://finance.yahoo.com/markets/stocks/articles/meta-remains-deeply-discounted-giant-163653339.html
- T4https://public.com/stocks/meta/forecast-price-target
- T2https://www.reuters.com/business/meta-29-states-head-court-biggest-test-yet-youth-social-media-litigation-2026…
- T2https://www.reuters.com/sustainability/boards-policy-regulation/jury-orders-meta-pay-375-mln-new-mexico-lawsui…
- T2https://www.reuters.com/business/meta-says-us-states-are-seeking-14-trillion-penalties-august-youth-safety-tri…
- T2https://www.reuters.com/sustainability/boards-policy-regulation/us-jury-verdicts-against-meta-google-tee-up-fi…
- T2https://www.reuters.com/legal/litigation/jury-reaches-verdict-meta-google-trial-social-media-addiction-2026-03…
- T2https://www.reuters.com/legal/litigation/what-did-jury-decide-social-media-case-against-meta-google-2026-03-25…
- T2https://www.reuters.com/world/ftc-will-appeal-ruling-meta-antitrust-case-over-instagram-whatsapp-deals-2026-01…
- T2https://www.reuters.com/legal/government/whats-latest-trials-over-claims-social-media-is-hurting-children-2026…
Earlier and later calls on META
- Oct 19, 2026Capex, not revenue, decides.No clear edgeview changed
- Oct 13, 2026No edge until Oct 21.No clear edgeview changed
- Oct 4, 2026No — the rally outran the evidence.Lean bearishview changed
Want a fresh look at META, or another name?
Queue a new deep-research run. Published to the feed when done.
Automated research opinion, published as-is on Aug 17, 2026. Not personalised advice. Figures use end-of-day closes.