Lean bullish into Oct 20.
Thesis
Bull case
The de-rating is a sentiment/disclosure event, not a fundamentals event. Netflix delivers Q3 in line with its $12.86B guide, reiterates FY26, shows ads revenue on pace for ~$3B, and the market re-prices from 18.7x toward even the mid-20s forward — implying 30-40% upside mechanically. Buybacks ($4.7B in Q2 alone, ~$27B authorized) accelerate EPS compounding into weakness, content spend growing slower than revenue (~10% vs 13-14%) supports continued margin expansion, and the FY27 EPS consensus anomaly resolves upward, making the stock cheaper than it screens. Absolute engagement growth (+2% YoY) means the YouTube narrative, while directionally true on share, never touches the income statement.
Bear case
Wells Fargo and HSBC are early, not wrong: engagement is the leading indicator for a model that now depends on ad monetization, and Netflix cutting viewing-hours disclosure frequency is what companies do when a metric is about to disappoint. Nielsen share loss (8.8% → 7.8% YoY) plus a weak hit slate means churn rises and ad-tier CPMs/fill suffer into 2027 — which would explain the otherwise-inexplicable FY27 consensus EPS deceleration (+6% on +11% revenue). If Q3 revenue misses $12.86B or FY26 guidance is trimmed, a stock 2.4% off its 52-week low with a 1.6 beta has no valuation floor near 18.7x — 'historical low multiple' is not support when the E is deteriorating. A guide-down on Oct 20 likely opens a path to the low $60s or below.
What would change our mind
- Q3 2026 revenue below $12.86B guide OR FY26 revenue guidance cut below $50.7B — would convert the de-rating from sentiment to fundamentals
- FY26 operating margin guidance cut below 31.5% or FCF guidance cut materially below $12.5B
- Ads revenue tracking materially below the ~$3B 2026 pace — would break the key incremental growth driver
- Disclosure on the Oct 20 call (or subsequent data) showing absolute viewing hours declining YoY — would falsify the SEC-filed +2% H1 engagement fact that anchors the bull case
- FY27 guidance implying EPS growth below ~5% with margin contraction — would validate the consensus anomaly as a real deterioration signal
Since publication vs SPY · closed horizons are frozen
The full research everything the view rests on
Direct answer to the question asked
Where the edge would come from
What the price assumes
The current price appears to assume growth deceleration beyond guidance, sustained engagement erosion to YouTube, and credibility loss from reduced viewing-hours disclosure — i.e., that FY26 guidance is a ceiling, not a base, and that the FY27 EPS consensus of only ~$3.81 (+6%) reflects real margin/spend pressure rather than stale aggregation. Consensus FY26 numbers ($51.2B revenue, ~$3.58 EPS) match guidance, so the discount is entirely in the multiple, not in estimates.
Why the market may be wrong
The market is treating relative share loss (Nielsen TV-time share) as equivalent to absolute engagement decline. They are different variables: Netflix's minutes watched are still growing (+2% YoY H1 2026, SEC-filed), and the ad business monetizes absolute minutes × ad load, not Nielsen rank. A 13-14% grower expanding margins, doubling ads revenue, and retiring shares aggressively at a historical-low multiple does not need engagement share to stabilize for the equity to work — it needs revenue and churn to hold, which current evidence supports. Additionally, the FY27 consensus EPS deceleration (+6% on +11% revenue despite guided margin expansion and buybacks) looks internally inconsistent; if it's stale aggregation, the '18.7x forward' is actually cheaper than it looks.
The one thing to watch
The load-bearing variable is not Nielsen TV-time share — it is churn and ad-tier ARPU. Share-of-TV-time can fall indefinitely while Netflix's monetizable minutes grow; the bear case only transmits to earnings if weak hit-content cadence actually raises churn or caps ad pricing. Netflix's own decision to cut viewing-hours disclosure frequency is the tell worth watching: it removes the exact data series that would falsify either side, which means the next hard falsification points are Q3 revenue vs the $12.86B guide and any churn/ads commentary on Oct 20 — not third-party Nielsen headlines.
Key evidence (10)
- FY2025 (SEC XBRL): revenue $45.2B (+16%), net income $11.0B, operating margin 29.5% — the de-rating is not in the reported P&L [T1]
- Q2 2026 (Jul 16, 2026): revenue $12.56B (hair below consensus), EPS $0.80 (beat); FY26 guidance reiterated at $50.7-51.7B revenue, 31.5% operating margin, ~$12.5B FCF [T1 IR/SEC; T2 Reuters]
- Q3 2026 guide of $12.86B revenue / $0.82 EPS came in below Street; stock fell ~9% and 18+ analysts cut price targets (Reuters, Jul 17, 2026) [T2]
- Netflix reduced 'What We Watched' viewing-hours disclosure from semi-annual to annual — visibility cut exactly when engagement is the contested variable [T2 Reuters]
- Nielsen Gauge (Jul 2026): YouTube record 14.2% of US TV time vs Netflix 7.8%, down from 8.8% a year earlier — the empirical core of the bear case [T3 Nielsen via T4 aggregators]
- Counter-fact: Netflix Q2 2026 shareholder letter reports 97B+ hours viewed in H1 2026, +2% YoY — absolute engagement growing [T1, SEC-filed]
- Ads revenue tracking to ~$3B in 2026, roughly double 2025; record $4.7B buyback in Q2 2026; ~$27B authorization remaining incl. +$25B approved April 2026 [T2/T4 aggregation — buyback totals partially T4-sourced]
- Forward P/E ~18.7x vs historical range ~18.7-38.3x [T4 aggregation — treat historical range as approximate]
- Internal inconsistency flagged: FY27 consensus implies +11% revenue but only +6.4% EPS despite guided margin expansion and buybacks — either an undisclosed 2027 margin shock or stale T4 consensus data
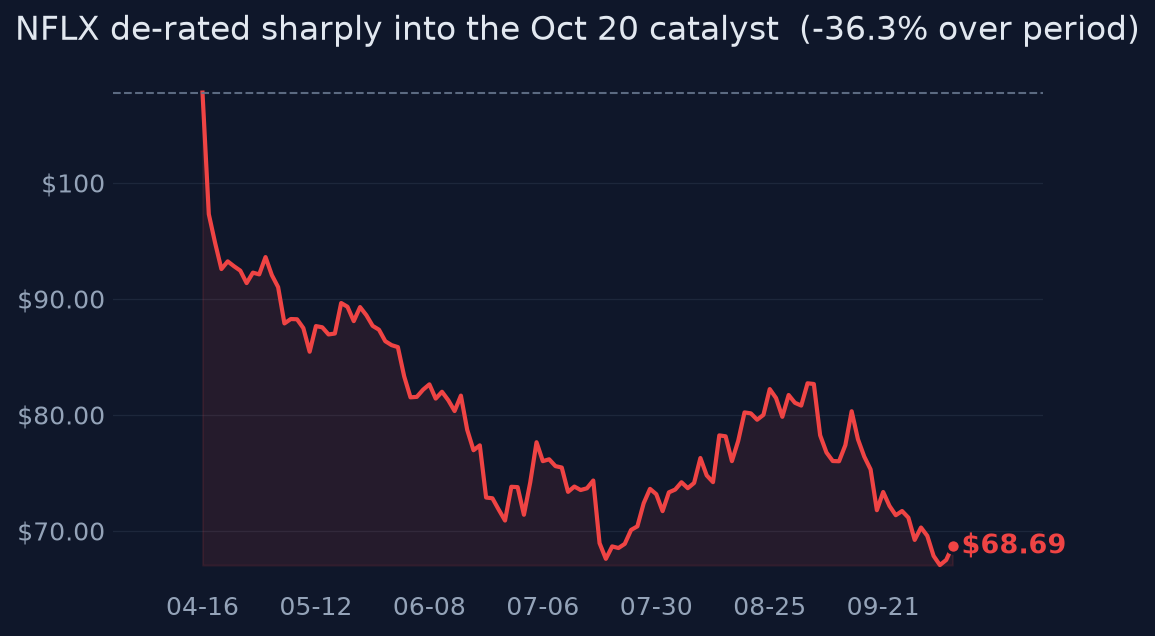
- Price action: -40% 1y, -30% 6m, 2.4% above 52-week low, RSI 27 (oversold), 94% idiosyncratic variance vs GOOGL — a stock-specific de-rating, not a market/sector move
Catalysts and risks
Catalysts
- Q3 2026 earnings, Oct 20, 2026 (~1:01pm PT, confirmed by Netflix IR Sep 14) — revenue vs $12.86B guide, EPS vs $0.82, FY26 guidance, ads progress, any engagement/churn commentary
- Q4 2026 earnings, Jan 18, 2027 (next scheduled report per data) — first clean read on holiday-quarter adds and 2027 guidance
- Nielsen Gauge monthly releases — whether NFLX US TV-time share stabilizes around ~7.8% or keeps sliding
- Any 2027 guidance framing (content spend, margin target) that resolves the FY27 EPS consensus anomaly
- Potential further analyst actions post-Q3 — the Wells Fargo/HSBC downgrades set up a reflexive re-rating if numbers hold
Risks
- Q3 miss or FY26 guidance trim on Oct 20 — the single largest near-term risk given the stock is priced for doubt
- Engagement deterioration transmits to churn/ads: the bear case's core mechanism is currently thin on evidence (T4-heavy) but unfalsifiable given reduced disclosure
- FY27 EPS consensus deceleration may reflect real undisclosed margin/spend pressure rather than stale data
- Reduced viewing-hours disclosure removes the market's ability to verify the bull case between prints, sustaining a sentiment discount
- High beta (1.6) and 33-37% realized vol mean further downside is possible even without fundamental news; 2.4% above 52-week low offers no technical support
- Key bull-case data points (buyback totals, forward P/E range, $3B ads figure) rest partly on T4 aggregation, not solely on filings
What to watch
- Oct 20 print: revenue vs $12.86B, any FY26 guide change, and the language around ads revenue and churn (now that viewing-hours disclosure is annual, call commentary is the only engagement signal)
- Monthly Nielsen Gauge: NFLX share stabilizing at ~7.5-8% vs continued decline; YouTube's trajectory
- Buyback pace in Q3 — whether Netflix accelerated repurchases into the drawdown (a management-conviction signal)
- FY27 consensus revisions: if EPS estimates migrate toward +10%+ growth, the anomaly was stale data and the multiple is cheaper than screened
- Hit-slate performance in Q4 (viewing data from third parties, since Netflix's own report cadence is now annual)
- Ad-tier ARPU/pricing commentary — the transmission point where engagement meets revenue
Market snapshot when the call was made 2026-10-06
Price
| Return 1w | -2.3% |
| Return 1m | -12.2% |
| Return 3m | -9.1% |
| Return 6m | -30.5% |
| Return 1y | -40.4% |
| From 52-week high | -44.7% |
| Realized vol, 20d | 32.9% |
| SPY 3m / 1y | +4.5% / +16.4% |
| QQQ 3m / 1y | +6.8% / +25.9% |
Technicals
NFLX technicals as of 2026-10-06: last close $68.69; 20d SMA 72.56 (bearish); 50d SMA 75.48; 12d EMA 70.14; 26d EMA 72.67; RSI 14 27.3 (oversold); 20d vol 32.7%; volume x1.0 vs 20d avg
Next earnings: 2027-01-18 AMC
Sources (22 · T1 = primary filings)
- T2https://www.reuters.com/business/media-telecom/lacks-excitement-netflix-tumbles-9-weak-earnings-forecast-deepe…
- T4https://www.investors.com/tag/netflix-stock-news/
- T1https://ir.netflix.net/investor-news-and-events/financial-releases/press-release-details/2026/Netflix-to-Annou…
- T4https://www.chosun.com/english/market-money-en/2026/10/01/NBEROHF6YNEQ5FMUGLKITHGYBA/
- T4https://www.chosun.com/english/market-money-en/2026/10/02/P5JZFLIXX5GU7AZ36GEYOUX57Q/
- T4https://www.perplexity.ai/finance/NFLX
- T4https://capital.com/en-gb/analysis/netflix-stock-forecast
- T1https://ir.netflix.net/investor-news-and-events/financial-releases/default.aspx
- T4https://admiralmarkets.com/analytics/traders-blog/netflix-stock-analysis-october-2026
- T1https://www.sec.gov/Archives/edgar/data/1065280/000106528026000211/ex991_q226.htm
- T4https://www.nielsen.com/data-center/the-gauge/
- T4https://techora.ru/news/youtube-uvelichil-otryv-ot-netflix-po-2026-10-04
- T4https://axis-intelligence.com/streaming-statistics/
- T4https://note.com/hirokimiyano/n/ne60177652610?hl=en
- T4https://worldscreen.com/nielsens-gauge-youtube-expands-tv-viewing-share/
- T4https://www.businessinsider.com/netflix-second-quarter-earnings-engagement-report-short-form-video-2026-7
- T2https://www.reuters.com/company/netflix-inc/
- T2https://www.reuters.com/markets/companies/NFLX.O/
- T4https://finance.yahoo.com/markets/stocks/articles/netflix-momentum-despite-being-down-123355121.html
- T4https://www.theglobeandmail.com/investing/markets/stocks/DIS/pressreleases/4427642/netflix-stock-rebound-fuels…
- T4https://www.marketbeat.com/stocks/NASDAQ/NFLX/earnings/
- T4https://www.insiderfinance.io/news/netflix-q3-2026-earnings-oct-20
Earlier and later calls on NFLX
- Oct 16, 2026De-rating overdone, but catalyst-gated.Lean bullish
- Oct 14, 2026Yes — derated, not broken.Lean bullish
- Oct 10, 2026Fairly valued after the reset.Neutralview changed
- Oct 7, 2026Lean bullish — a reset, not a break.Lean bullish
Want a fresh look at NFLX, or another name?
Queue a new deep-research run. Published to the feed when done.
Automated research opinion, published as-is on Oct 7, 2026. Not personalised advice. Figures use end-of-day closes.