Fairly valued after the reset.
Thesis
Bull case
The de-rating is done and the setup into Q3 is favorable: management guided conservatively in July (below Street), margins are at record levels (33.4%), the ad target is intact with upfront commitments closing, and price increases are 'progressing well' with membership gains still contributing per management's own commentary. A ~$27B buyback authorization (~9% of market cap) deployed at 19x forward provides both a floor and an EPS accelerant — buybacks alone can deliver mid-to-high-single-digit EPS growth even if operating growth stalls. If Q3 merely confirms ~12% growth and FY guidance holds, a re-rating toward 22-24x (still well below the ~28x seen earlier in 2026) implies +15-25% upside. Net debt under half a year's FCF means no balance-sheet constraint on returns.
Bear case
This is a structural growth re-rating, not a one-time reset: the drivers of the 2024-25 growth surge appear lapped, engagement grows ~2%, the ad business misses external expectations while management cuts disclosure precisely where scrutiny is highest, and a consolidated Paramount-WBD (HBO Max + Paramount+ + WBD studio) is a stronger rival. Consensus 2027 EPS growth of ~6% reveals margin leverage is nearly exhausted — at that growth rate, 19x is full. The FCF guide raise primarily reflects a one-time termination fee while underlying Q2 FCF fell ~33% y/y; if Q3 disappoints again (the second consecutive guide-down), the multiple compresses toward mature-media levels (e.g., ~15x, implying roughly -20% — an illustrative assumption; the evidence contains no sourced peer-multiple comparison). Declining disclosure (subscribers, then viewing hours) is a late-cycle tell, though this is interpretive, not evidenced fact.
What would change our mind
- For a cautious/neutral stance, bullish invalidation (would upgrade): Q3 revenue ≥ $12.9B with FY26 guidance raised above $51.4B AND upfront commitments confirming >$3B 2026 ad run-rate — that would show the reset overshot
- Bearish invalidation (would downgrade): Q3 revenue below ~$12.7B or FY guidance cut, or ad revenue tracking >5% below the revised ~$3B consensus — confirming the maturity re-rating
- If buyback deployment falls below ~$1B/quarter at these prices, the capital-return floor thesis weakens materially
- If FY27 margin guidance (Jan 2027) comes in above ~33% with revenue growth re-accelerating toward 13%+, the 'leverage exhausted' bear case is wrong
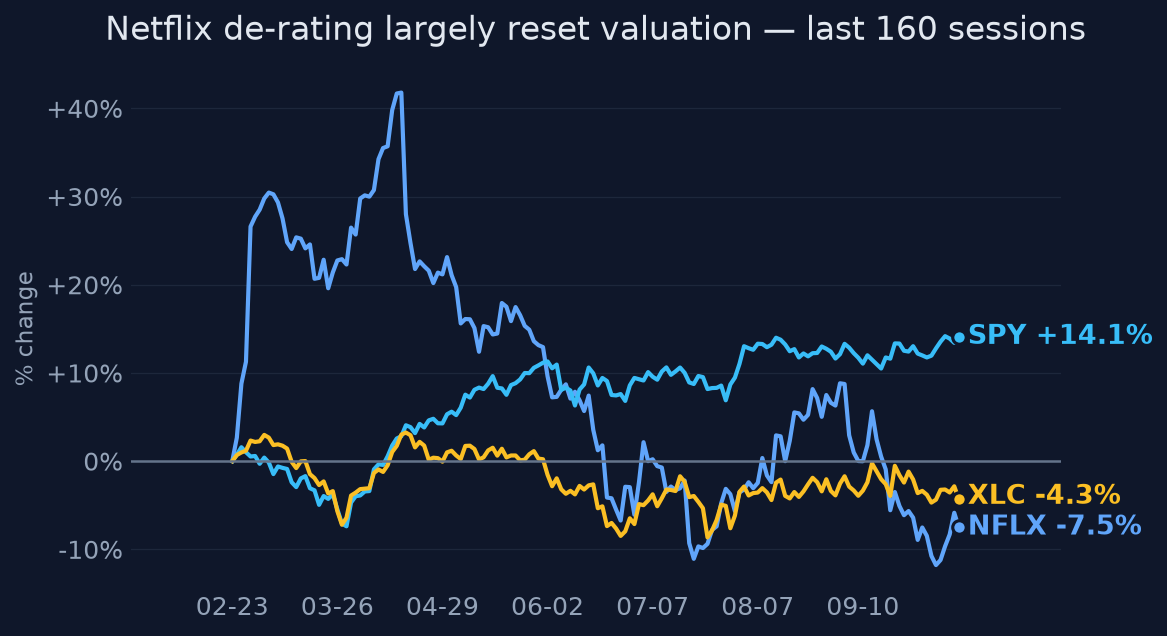
Since publication vs SPY · closed horizons are frozen
The full research everything the view rests on
Direct answer to the question asked
Where the edge would come from
What the price assumes
At ~19x forward EPS ($70.30 vs $3.58 FY26 consensus) — the lowest multiple since 2022 and down from ~28x earlier in 2026 — the price assumes Netflix is a low-double-digit revenue grower with modest further margin expansion. It does NOT appear to assume an ad-business upside surprise or engagement re-acceleration; estimates have only drifted down (1-2 downward revisions per metric in the last 30 days, zero upward). The bar into Q3 is low: guided $12.86B revenue (+12%), $0.82 EPS, ~33.2% margin — figures management set below Street in July.
Why the market may be wrong
Two directions. Bearish surprise risk: consensus 2027 EPS of $3.80 implies only ~6% growth on +11% revenue — if that reflects a margin plateau (~31.5% held flat) rather than conservatism, the 'cheap' 19x is a fair multiple for a maturing media company, and the disclosure reductions (no subscriber counts, viewing-hours going annual in 2027) suggest management knows engagement is the weak variable. Bullish surprise risk: the market may be underweighting the buyback as an EPS engine — a $27.1B authorization deployed at depressed prices could retire ~9% of shares, mechanically lifting per-share metrics even if operating growth stalls, and management's willingness to spend $4.7B in one quarter signals they view the stock as undervalued.
The one thing to watch
The single variable that matters now is not subscriber growth or even ad revenue — it's that Netflix's EPS growth has become buyback-dependent: 2027 consensus implies ~+6% EPS on +11% revenue, meaning operating leverage is nearly exhausted at ~31.5% margins, so per-share value creation hinges on how much of the $27.1B authorization gets deployed at these prices. Watch Q3/Q4 repurchase disclosure as management's own valuation signal; also note the FY26 FCF guidance raise to $12.5B was driven primarily by the after-tax effect of the one-time $2.8B WBD termination fee — underlying FCF momentum actually stalled (Q2 FCF fell to $1.53B from $2.27B).
Key evidence (11)
- 10-for-1 split effective Nov 17, 2025 [T1 Netflix IR] — quoted '-94% 1y return' is a data artifact; real drawdown is ~-27% from $96.24 (Feb 27, 2026) to $70.30, ~-32% over 6 months
- Revenue: $39.0B (2024, +15.6%) → $45.2B (2025, +15.9%) → guided $51.0-51.4B (2026, +13-14%) → consensus $56.9B (2027, +11%) [T1 SEC / T4 consensus]
- Operating margin: 26.7% (2024) → 29.5% (2025) → 31.5% target (2026); Q2 2026 actual 33.4% [T1 SEC / T2 Reuters]
- Q2 2026 (Jul 16): revenue $12.56B and EPS $0.80 in line, but Q3 guide ($12.86B / $0.82) missed Street ($13.0B / $0.84); stock fell ~9%, 18+ analysts cut targets [T2 Reuters]
- Management said Q3 growth driven by membership gains and pricing, with price increases 'progressing well' and acquisition/retention trends healthy — so the specific cause of deceleration is not established in evidence [T4 earnings materials]
- Consensus EPS $3.58 (FY26) vs $3.80 (FY27) — only ~6% growth; revisions mildly negative across the board in last 30 days [T4 Zacks/Yahoo — flag: aggregator-tier, not FactSet/LSEG primary]
- Ads: $3B FY26 target reiterated; Q2 ad revenue ~$618M, +80% y/y but 7.2% below Visible Alpha consensus; analysts cut FY ad estimates ~7.8% to ~$3.02B — no cushion left [T3 S&P Global / T2 Reuters]
- Engagement: viewing hours +2% in H1 2026; quarterly subscriber reporting ended 2025; viewing-hours disclosure goes annual from 2027 [T2 Reuters]
- Capital returns: record $4.7B Q2 buyback; ~$27.1B authorization remaining (~9% of $293B market cap); FY26 FCF guided ~$12.5B, raised from $11B primarily reflecting the after-tax effect of the $2.8B Paramount termination fee; Q2 FCF actually fell y/y to $1.53B on cash taxes [T2/T4]
- Balance sheet: ~$9.1B cash vs ~$14.4B gross debt → ~$5.3B net debt, <0.5x one year's FCF [T4 earnings materials]
- Walked away from WBD bid (Feb 26, 2026) rather than match Paramount's $31/share; stock rallied +13.75% on the discipline — the market's problem is organic growth, not M&A [T2 Reuters]
Catalysts and risks
Catalysts
- Q3 2026 earnings Oct 20, 2026: revenue vs $12.86B guide, EPS vs $0.82, any FY26 guidance tweak, ad-revenue disclosure vs revised ~$3B consensus
- US upfront ad commitment results — management said deals closing 'within weeks' as of July; final pricing/volume validates or breaks the $3B target
- Q3/Q4 buyback disclosure: pace of deployment of the $27.1B authorization at depressed prices
- Q4 2026 print (~Jan 18, 2027) and first FY27 guidance/margin target — the market will immediately test whether the ~6% EPS growth consensus is conservative or real
- Any 2027 content/sports-rights spending escalation or renewed M&A appetite (post-WBD discipline signal)
Risks
- Second consecutive guidance miss on Oct 20 would confirm the growth-deceleration narrative and likely trigger another leg of multiple compression
- Ad revenue misses the revised ~$3.02B consensus — there is no cushion between company target and Street estimate
- Engagement deterioration hidden by reduced disclosure; annual viewing-hours reporting starts 2027, delaying detection
- FCF quality: FY26 guide flattered primarily by the one-time $2.8B termination fee; underlying FCF growth is weaker than the headline (Q2 FCF -33% y/y)
- Consensus estimates rest on T3/T4 aggregators (Zacks, Yahoo, Visible Alpha via S&P Global) — the ~6% FY27 EPS growth figure is an assumption built on non-primary sources
- Beta 1.6 — a broad market drawdown amplifies NFLX downside regardless of fundamentals
What to watch
- Oct 20 print: revenue vs $12.86B guide and the FY26 range ($51.0-51.4B) — hold, raise, or cut
- Ad revenue line vs the revised ~$3.02B FY consensus; any commentary on ad-tier ARM gap closing and upfront pricing
- Quarterly share count change — the direct read on buyback deployment vs the $27.1B authorization
- Estimate revisions in the 30 days post-earnings: whether FY27 EPS ($3.80, +6%) moves up (conservatism confirmed) or down (margin plateau confirmed)
- FCF ex-termination-fee: whether underlying FCF re-accelerates after the Q2 tax-related dip
- Any reversal or expansion of disclosure policy — restoring metrics would signal confidence; further cuts would reinforce the bear interpretation
Market snapshot when the call was made 2026-10-09
Price
| Return 1w | +4.8% |
| Return 1m | -7.5% |
| Return 3m | -4.8% |
| Return 6m | -31.8% |
| Return 1y | -94.2% |
| From 52-week high | -94.3% |
| Realized vol, 20d | 34.8% |
| SPY 3m / 1y | +3.9% / +15.7% |
| QQQ 3m / 1y | +5.5% / +22.9% |
Technicals
NFLX technicals as of 2026-10-09: last close $70.30; 20d SMA 71.66 (bearish); 50d SMA 75.33; 12d EMA 70.30; 26d EMA 72.23; RSI 14 39.8 (balanced); 20d vol 30.8%; volume x0.8 vs 20d avg
Next earnings: 2027-01-18 AMC
Verifier notes REVISE · opinion revised once
Unsupported claims
- 'Paid sharing is done' / 'paid-sharing and price hikes are lapped' (thesis and bear_case): the evidence bundle contains no mention of paid sharing or password-crackdown dynamics at all. Growth deceleration itself is well evidenced (revenue series + guidance), but this specific causal attribution for why growth is fading is asserted without support — and it partially conflicts with evidence that management described membership gains and price increases as still progressing well.
- Comp-set multiples 'Disney/mature-media ~12-15x vs. platform-growth 25x+' (why_this_matters, and implicitly anchoring the bear case's 15x / ~-20% scenario): these specific peer-multiple figures appear nowhere in the evidence. The only valuation comparisons in evidence are NFLX's own forward P/E (~18.7-19.0x, lowest since 2022, down from ~28x) and a 5yr average trailing P/E of 65.18x that the evidence itself flags as not like-for-like.
Weakly sourced
- The bear case's quantitative downside anchor (multiple compression 'toward mature-media levels (15x → ~-20%)') rests on an uncited 15x mature-media multiple — the -20% arithmetic is internally correct but the 15x input is not evidenced.
- The claim that FY26 FCF guidance was raised 'entirely' due to the $2.8B termination fee: the evidence (T4 earnings materials) says the raise from $11B to $12.5B 'primarily reflected the after-tax effect' of the fee. 'Entirely' overstates a T4-sourced point that is central to the FCF-quality argument.
Corrections applied
- In thesis and bear_case, either remove the paid-sharing claim or reframe as inference from the evidenced deceleration, e.g.: 'the drivers of the 2024-25 growth surge appear lapped' — without naming paid sharing, which the evidence does not cover.
- In why_this_matters, drop the specific '12-15x' / '25x+' comp figures or explicitly label them as illustrative assumptions not sourced from the evidence; correspondingly soften the bear case to 'compression toward mature-media multiples (e.g., ~15x, ~-20%)' flagged as an assumption.
- Change 'the FY26 FCF guidance raise to $12.5B was entirely the one-time $2.8B WBD termination fee' to 'was driven primarily by the after-tax effect of the $2.8B termination fee' to match the evidence language.
Sources (28 · T1 = primary filings)
- T1https://ir.netflix.net/investor-news-and-events/financial-releases/press-release-details/2025/Netflix-Announce…
- T4https://www.zacks.com/stock/news/2955750/netflix-q2-earnings-beat-stock-falls-on-revenue-miss-lower-outlook
- T2https://www.reuters.com/business/media-telecom/lacks-excitement-netflix-tumbles-9-weak-earnings-forecast-deepe…
- T4https://www.stocktitan.net/sec-filings/NFLX/8-k-netflix-inc-reports-material-event-479d0dbed156.html
- T3https://www.cnbc.com/2025/10/30/netflix-stock-split.html
- T4https://ground.news/article/netflix-announces-a-10-for-1-stock-split
- T4https://df.bmogam.com/assets/static/ca-pdfs/ZNFL-ratioAdjustment-15711668978-preliminary-en-US.pdf
- T2https://www.reuters.com/business/media-telecom/netflix-third-quarter-earnings-forecast-falls-shy-wall-street-e…
- T3https://www.cnbc.com/2026/07/16/netflix-nflx-earnings-q2-2026.html
- T2https://www.reuters.com/business/media-telecom/netflix-refocus-ads-content-after-failed-warner-bros-bid-2026-0…
- T4https://www.zacks.com/stock/news/2955489/netflix-q2-earnings-call-highlights-ai-ads-growth-plans
- T2https://www.reuters.com/business/media-telecom/netflixs-next-growth-chapter-hinges-keeping-viewers-hooked-2026…
- T3https://www.spglobal.com/market-intelligence/en/news-insights/research/2026/07/netflix-postq-slower-advertisin…
- T4https://finance.yahoo.com/quote/NFLX/earnings/NFLX-Q2-2026-earnings_call-650439.html/
- T4https://finance.yahoo.com/markets/stocks/articles/paramount-paid-netflix-2-8-230000125.html
- T2https://www.reuters.com/legal/transactional/paramount-revises-offer-warner-bros-with-25-cent-ticking-fee-2026-…
- T2https://www.reuters.com/sustainability/boards-policy-regulation/time-inc-discovery-warner-bros-breakup-puts-sp…
- T4https://www.marketbeat.com/stocks/NASDAQ/NFLX/news/
- T2https://www.reuters.com/5f374b32b07b/sustainability/boards-policy-regulation/time-inc-discovery-warner-bros-br…
- T4https://finance.yahoo.com/markets/stocks/articles/buy-netflix-dip-154749772.html
- T4https://finance.yahoo.com/news/netflix-stock-nearly-10-ditching-232344036.html
- T4https://longbridge.com/news/300403774
- T4https://www.investing.com/news/transcripts/earnings-call-transcript-netflix-posts-slight-q2-2026-beat-shares-s…
- T4https://static.poder360.com.br/uploads/2026/07/Netflix-2T2026.pdf
- T4https://www.aol.com/articles/netflix-crosses-growth-threshold-changes-093000000.html
- T4https://financebuzz.com/news/netflix-stock-warning-sign
- T4https://static.poder360.com.br/2026/04/balanco-netflix-1o-tri-2026.pdf
- T4https://finance.yahoo.com/quote/NFC.MU/earnings/NFC.MU-Q2-2026-earnings_call-650439.html/
Earlier and later calls on NFLX
- Oct 16, 2026De-rating overdone, but catalyst-gated.Lean bullishview changed
- Oct 14, 2026Yes — derated, not broken.Lean bullishview changed
- Oct 7, 2026Lean bullish — a reset, not a break.Lean bullishview changed
- Oct 7, 2026Lean bullish into Oct 20.Lean bullishview changed
Want a fresh look at NFLX, or another name?
Queue a new deep-research run. Published to the feed when done.
Automated research opinion, published as-is on Oct 10, 2026. Not personalised advice. Figures use end-of-day closes.