Business strong; stock a speculative buy.
Thesis
Bull case
Figma is growing 48% with accelerating NDR (136%), 85% gross margins, $1.7B cash, and AI monetization already contributing — yet trades below its IPO price at ~6x forward sales because the market lumped it into the AI-disruption basket with Adobe. If Q3 beats a conservative 36% guide and NDR holds, the stock re-rates toward the Street's ~$31 (+45%), with further upside if beta-stage AI products (currently excluded from guidance) begin contributing in 2027. Oversold technicals (RSI 26) and a known near-term catalyst make the setup tactically attractive.
Bear case
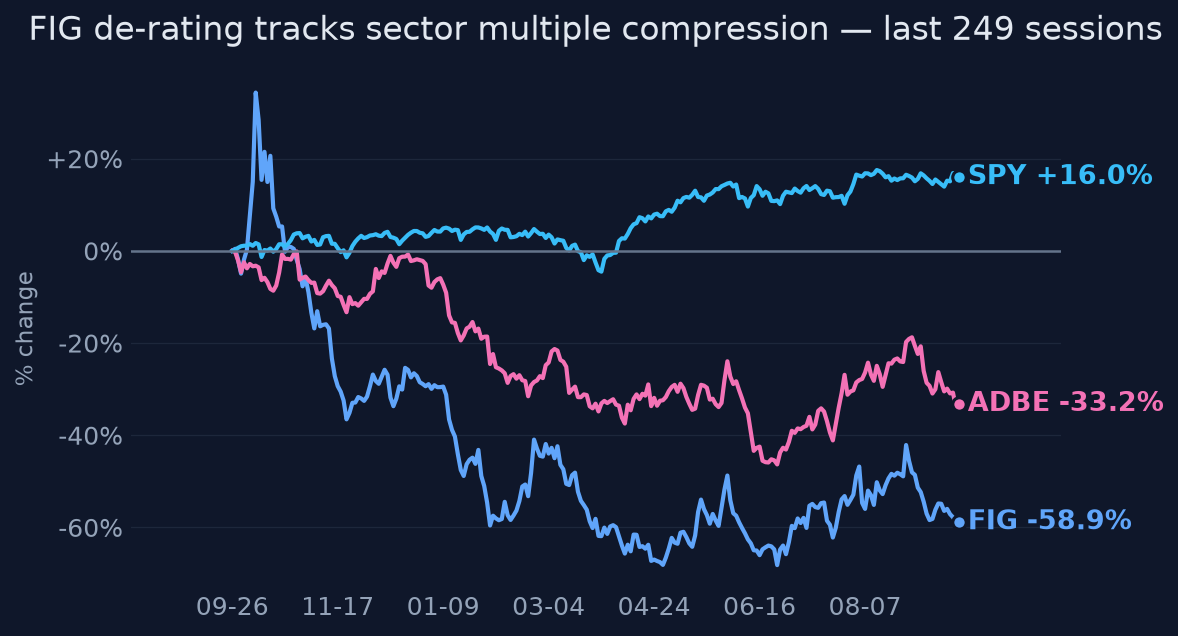
The deceleration is real and structural: 48% → 36% guided → ~24% implied FY27, which at 60-79x forward earnings leaves no margin of safety if growth undershoots. Management is choosing margin suppression (op margin down to 10%, FY op income guide flat despite revenue raise), and the AI threat is genuine longer-term — prompt-to-design and vibe-coding tools attack the seat model upstream, and Q3's NDR could be the first place cracks appear. The stock remains in a sector de-rating (ADBE -34% 1yr, 0.64 correlation), GAAP losses are enormous, and at 68-78% realized vol another -30% drawdown on a soft print is entirely plausible.
What would change our mind
- Q3 2026 revenue growth materially below the ~36% guide midpoint, or FY26 guidance cut
- Net dollar retention falls below ~125-130% — evidence the AI seat-compression thesis is arriving in the data
- Non-GAAP operating income guidance reduced below the $100M low end
- Credible evidence of enterprise churn or seat-count contraction attributable to AI-native tools (vibe coding, prompt-to-design)
- Failure to hold the 52-week low area (~$17) on heavy volume after earnings — signals the market sees deterioration, not compression
Since publication vs SPY · closed horizons are frozen
No price data after the entry date yet.
The full research everything the view rests on
Direct answer to the question asked
Where the edge would come from
What the price assumes
At $21.34 (~$10.4B market cap, ~$8.7B EV), the price implies meaningful skepticism: ~6.3x FY26E and ~4.8x FY27E sales for a company growing 36-48% with 84-85% gross margins. The forward P/E of 60-79x on thin consensus EPS ($0.28 FY26) shows the market doesn't credit current earnings because management is deliberately suppressing margins (FY revenue guide raised but operating income guide held flat at $100-110M). The price assumes growth fades toward ~24% by FY27 and that AI tools eventually compress the seat model.
Why the market may be wrong
The AI-seat-compression thesis is being applied to Figma's multiple before it has appeared in Figma's data. NDR of 136% (up YoY) means existing customers are expanding spend faster than ever, and management explicitly attributed part of Q2 growth to AI credit usage — AI is currently a revenue tailwind, not a substitute. The Q3 guide of ~36% may be conservative given the company just beat and raised. If the sector-wide AI repricing (which hit Adobe similarly) proves overdone for the company with the strongest retention metrics in the group, FIG is the oversold beneficiary.
The one thing to watch
The variable to watch is not headline revenue growth — it's net dollar retention. The entire bear case (AI compresses design seats) must show up in NDR before it shows up anywhere else, and NDR is currently moving the wrong direction for bears (129%→136% with AI credits additive). If Q3 NDR holds ≥130% while the stock trades at ~6x forward sales, the de-rating is provably multiple compression rather than deterioration — that is the falsifiable line between 'cheap' and 'value trap.'
Key evidence (10)
- Q2 2026 (reported Aug 5, 2026): revenue $370M, +48% YoY, beat; EPS $0.08 vs consensus -$0.22 [T1 Figma IR; T2 Reuters 2026-08-05]
- Net dollar retention 136% in Q2 2026, up from 129% a year earlier [T1 IR release]
- FY2026 revenue guidance raised to $1.366-1.374B; non-GAAP operating income guide held at $100-110M [T1/T2]
- Q3 2026 guidance implies ~36% YoY growth at midpoint — the deceleration trigger for the selloff [T2 Reuters; T4 transcript summaries]
- Customer counts: 15,964 >$10k ARR; 1,635 >$100k ARR; $1.7B cash and securities [T1]
- Non-GAAP operating margin fell to 10% in Q2 from 16% in Q1 (Config spend + AI investment) [T2 Reuters]
- Stock: $21.34, below $33 IPO price, -63% 1yr, -70% from 52wk high, RSI 26 (oversold), 60d correlation to SPY 0.06 but 0.64 to ADBE [market data]
- Street consensus Overweight/Buy, average PT ~$31-32 (range $22-42; Citi $35, BofA $30, Wells $36) [T3 MarketWatch; T4 aggregators]
- Consensus estimates: FY26 $1.47B rev / $0.28 EPS; FY27 $1.82B / $0.34 EPS [T4 Yahoo/WSJ estimate pages, Sep 2026]
- FY2025 GAAP net loss -$1.25B (largely IPO-related SBC); GAAP profitability distant [T1 SEC XBRL]
Catalysts and risks
Catalysts
- Q3 2026 earnings (~Nov 2026): test of the 36% growth guide and NDR trajectory — the single decisive event in the horizon
- Any disclosure that beta-stage AI products (currently excluded from guidance) are entering GA monetization
- FY27 preliminary guidance or analyst day commentary on margin trajectory
- Sector read-throughs: Adobe and other design/creative software earnings shaping the AI-disruption narrative
- Potential insider/lockup-related supply events (background overhang flagged but not confirmed as a September driver)
Risks
- Guided deceleration proves real: Q3 at or below 36% with a soft Q4 guide breaks the 'sandbagging' assumption
- NDR rolls over from 136% — first observable evidence of AI seat compression
- Continued margin suppression: op income guide stays flat or is cut again on AI spend
- Sector-wide AI repricing deepens regardless of Figma's company-specific execution
- Extreme volatility (68-78% annualized) and heavy idiosyncratic exposure — sizing risk is as important as direction
- Key estimates (consensus EPS, price targets) rest on T3/T4 aggregators, not primary filings; RPO/forward bookings not confirmed in this research
What to watch
- Q3 2026 NDR vs the 136% print — the single most diagnostic metric for the AI-disruption debate
- Q3 revenue vs the ~$376M consensus and the implied Q4 guide
- Non-GAAP operating margin recovery from 10% as Config seasonality passes
- AI credit monetization disclosures: attach rates, overage revenue, GA timing for beta AI products
- Adobe and Canva competitive moves; any seat-pricing changes in Figma's hybrid seat+usage model
- Estimate revision trend: FY27 EPS/revenue consensus direction into year-end
Market snapshot when the call was made 2026-09-24
Price
| Return 1w | -8.4% |
| Return 1m | -21.8% |
| Return 3m | +26.7% |
| Return 6m | +1.2% |
| Return 1y | -63.3% |
| From 52-week high | -70.0% |
| Realized vol, 20d | 68.2% |
| SPY 3m / 1y | +4.7% / +15.1% |
| QQQ 3m / 1y | +3.5% / +23.9% |
Technicals
FIG technicals as of 2026-09-24: last close $21.34; 20d SMA 24.17 (bearish); 50d SMA 24.53; 12d EMA 22.80; 26d EMA 23.75; RSI 14 26.2 (oversold); 20d vol 44.8%; volume x0.7 vs 20d avg
Sources (29 · T1 = primary filings)
- T2https://www.reuters.com/company/figma-inc/
- T1https://investor.figma.com/news-events/news/news-details/2026/Figma-Announces-Second-Quarter-2026-Financial-Re…
- T4https://www.investing.com/equities/figma-inc-earnings
- T4https://finance.yahoo.com/quote/FIG/
- T4https://finance.yahoo.com/quote/FIG/history/
- T4https://www.marketbeat.com/instant-alerts/price-figma-nyse-fig-stock-price-down-51-time-to-sell-2026-09-22/
- T1https://www.sec.gov/Archives/edgar/data/1579878/000162828026035087/q126pressrelease.htm
- T4https://www.ainvest.com/news/figma-sinks-post-ipo-lows-earnings-high-expectations-2509/
- T4https://www.figma.com/pricing/
- T4https://www.awesomic.com/blog/figma-pricing
- T2https://www.reuters.com/business/adobe-beats-third-quarter-revenue-estimates-2026-09-10/
- T4https://www.investing.com/analysis/figma-trades-in-reset-mode-as-the-market-reprices-growth-after-the-ipo-hang…
- T4https://www.figma.com/pricing-faq/
- T4https://fortune.com/2026/02/18/fig-stock-q4-earnings/
- T4https://finance.yahoo.com/markets/stocks/articles/figma-announces-second-quarter-2026-200500534.html
- T4https://finance.yahoo.com/quote/FIG/earnings/FIG-Q2-2026-earnings_call-669452.html
- T4https://finance.yahoo.com/quote/1S2.DU/earnings/1S2.DU-Q2-2026-earnings_call-669452.html
- T4https://www.theglobeandmail.com/investing/markets/stocks/FIG/pressreleases/3818169/figma-fig-q2-2026-earnings-…
- T4https://finance.yahoo.com/markets/stocks/articles/figma-q2-2026-earnings-beat-140019235.html
- T2https://www.reuters.com/technology/figma-lifts-annual-revenue-forecast-ai-efforts-drive-solid-demand-2026-08-0…
- T1https://investor.figma.com/financials/quarterly-results/default.aspx?ref=designews_com
- T4https://finance.yahoo.com/quote/FIG/analyst-insights/
- T4https://public.com/stocks/fig/forecast-price-target
- T4https://www.investing.com/equities/figma-inc-consensus-estimates
- T3https://www.marketwatch.com/investing/stock/fig/analystestimates
- T4https://www.marketbeat.com/stocks/NYSE/FIG/forecast/
- T4https://stockanalysis.com/stocks/fig/
- T4https://www.zacks.com/stock/research/FIG/price-target-stock-forecast
- T4https://finance.yahoo.com/research/stock-forecast/FIG?symbols=FIG
Earlier and later calls on FIG
- Sep 15, 2026Yes — but only in small size.Lean bullish
- Sep 8, 2026Yes — massively, but not cheaply.No clear edgeview changed
- Aug 23, 2026No clear edge at $27.No clear edgeview changed
- Aug 14, 2026Multiple compression, not deterioration.Lean bullish
Want a fresh look at FIG, or another name?
Queue a new deep-research run. Published to the feed when done.
Automated research opinion, published as-is on Sep 25, 2026. Not personalised advice. Figures use end-of-day closes.