Oversold reset — cautiously attractive.
Thesis
Bull case
The selloff is a sentiment-driven multiple reset on a business still growing EPS ~8%/yr with 46% operating margins, 220M active loyalty users, and international strength. At 17.5x forward with a 3.3% yield — a valuation last seen years ago — any evidence at the Oct 22 print that US traffic is stabilizing (beverage initiatives early strength, corrective marketing) triggers re-rating toward the $297-309 analyst target cluster, 25-32% upside. The $8.5B program, spread over a decade (~$5B by 2030, so likely only ~$1-2B/yr near-term against ~$12B+ operating income), is more manageable than the headline number suggests and could drive the 250bps efficiency gains that support the raised 2030 margin target.
Bear case
The September 23 update is an implicit admission the US model is broken: a decade-long franchisee bailout, flat-traffic guidance, and traffic declines every month since March while management's $4 breakfasts and sub-$3 items failed to convert. Loyal-customer frequency erosion plus GLP-1 adoption (4-5% lower fast-food spend per user, growing) suggests a structural, not cyclical, demand problem. Estimates are stale — FY27 at $13.94 hasn't absorbed the update — and Oct 22 could start a cut cycle; with Wendy's at -12.5% traffic showing where the low-end consumer is, MCD's 'execution' excuse may just be a lag. Melius cutting to $230 (≈ current price) is the leading edge.
What would change our mind
- Q3 shows US comps negative and/or management guides FY27 below ~$13.50 EPS — confirms the cut-cycle bear case
- Company discloses the franchisee support will consume materially more than ~$1.5-2B/yr of FCF in 2026-2028 or buybacks are curtailed
- US traffic declines accelerate (e.g., worsening from the every-month-since-March streak) despite corrective actions and beverage initiatives
- Evidence that loyal/loyalty-member frequency — not just casual traffic — continues eroding through year-end
- Operating margin guidance for 2027 walks back from the trajectory toward low-to-mid 50s% by 2030
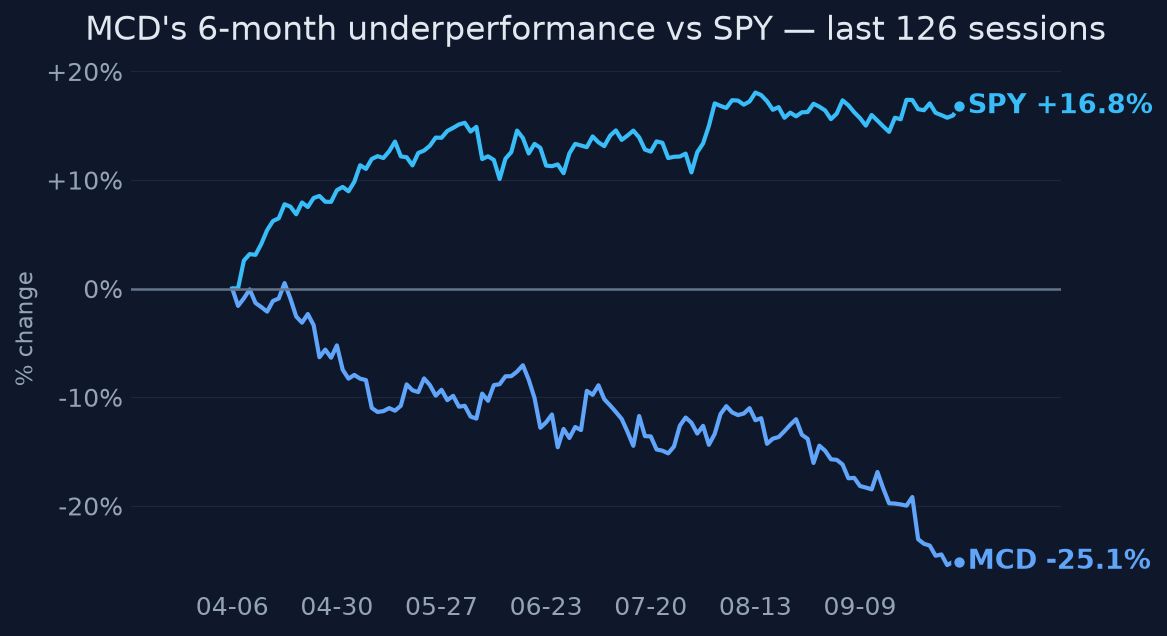
Since publication vs SPY · closed horizons are frozen
The full research everything the view rests on
Direct answer to the question asked
Where the edge would come from
What the price assumes
At ~$233 (17.5x FY26 EPS of $12.89, near the 52-week low, RSI 16.7), the market is pricing meaningful probability of FY26/FY27 estimate cuts, sustained flat-to-negative US traffic, and multi-year FCF erosion from franchisee support — roughly a 'business in secular slowdown' multiple rather than the 'durable compounder' multiple MCD has historically carried (low-to-mid 20s P/E).
Why the market may be wrong
Consensus FY26 EPS ($12.89) and FY27 EPS ($13.94) have drifted down only ~1-2% over 3 months even after the September 23 shock, meaning the selloff is almost entirely multiple compression. If the business delivers anything close to consensus — Q2 already beat EPS and grew global comps +1.3% with international strength offsetting the US — the de-rating is overdone. Additionally, the market reads the $8.5B program as pure FCF destruction, but management framed it as buying ~250bps of restaurant-level efficiency and ~$100K/yr per-restaurant cash flow with a ~4-year franchisee payback; if even partially credible, the long-term margin target (low-to-mid 50s% by 2030) is more achievable than the stock price implies.
The one thing to watch
The detail that changes what to watch: management said loyal customers drove roughly two-thirds of the US traffic shortfall. That means the problem is not value-war customer defection to Wendy's/BK (which discounts can fix) but frequency erosion among MCD's best customers — consistent with low-income strain and early GLP-1 adoption — which promotions cannot quickly reverse. The variable to watch in upcoming prints is US traffic frequency among loyalty members, not headline comps; headline comps can look fine on price/mix while the core customer base keeps quietly shrinking.
Key evidence (10)
- Price action: -32% from 52w high, -17% in 3m, RSI 14 of 16.7, 1-month return z-score -1.95, while SPY +17% over 6m — idiosyncratic, not market-driven (market data, 2026-10-05)
- Q2 2026 (Aug 4): adj EPS $3.38 vs $3.34 est (beat); revenue ~$7.1B vs $7.14B (slight miss); global comps +1.3% but US comps only +0.8%; management cited 'urgent action' needed in the US (earnings release; Reuters)
- Management disclosed loyal customers accounted for ~2/3 of the US traffic shortfall and blamed execution, not strategy (Q2 call via Reuters, Aug 2026)
- Sept 23, 2026 investor update [T1 SEC 8-K]: $8.5B franchisee 'NEXT' support through 2036 (~$5B by 2030) via rent relief/capital support; +$1.5-2B incremental capex 2027-30; 2030 operating margin target raised to low-to-mid 50s%; ~250bps efficiency target; stock fell up to 6.5% (SEC; Reuters; CNBC)
- Management warned traffic in key markets likely flat while inflation stays high; US foot traffic declined YoY every month since March 2026 (Reuters)
- Valuation: forward P/E ~17.5-17.7x vs historical low-to-mid 20s; dividend yield ~3.2-3.3%; total shareholder yield ~4.6% (market data; [T4] sources, approximate)
- Consensus: FY26 EPS $12.89 (was $12.99 three months ago); FY27 $13.94 (was $14.19); next print ~Oct 22, 2026 at $7.33B/$3.40 (MarketWatch/analyst feeds, [T3/T4])
- Industry context: Wendy's Q2 US same-restaurant sales -7%, traffic -12.5%, withdrew 2026 guidance; US restaurant traffic down two straight years (Technomic/S&P); Reuters: 'cheap deals no longer do the trick' — weakness is industry-wide but MCD underperforming within it
- GLP-1: PwC data via Reuters — users consume ~40% fewer calories and spend 4-5% less on fast food; MCD adapting menus (smaller portions, more protein); structural drag, not the primary selloff driver
- Fundamentals decelerating, not collapsing: revenue $25.5B (2023) → $26.9B (2025); operating margin improved to 46.1% in 2025 [T1 SEC XBRL]
Catalysts and risks
Catalysts
- Q3 2026 earnings ~Oct 22, 2026 (consensus $7.33B rev / $3.40 EPS) — the binary fork for the thesis
- Monthly US traffic data and any management commentary on frequency/loyalty trends
- Post-earnings analyst estimate revisions to FY27 ($13.94) — direction matters more than the print itself
- Publication of any 2026-2028 FCF bridge quantifying the franchisee support drag
- GLP-1 adoption data and MCD menu adaptation (portion/protein) rollout
- Beef cost trajectory into 2027 menu pricing decisions
Risks
- Estimate cuts: consensus still models 8% growth that flat traffic may not deliver; a FY27 cut cycle invalidates the 'cheap on consensus' framing
- FCF opacity: no published bridge for how much of ~$5B near-term support hits 2026-2028 free cash flow — buyback capacity could shrink
- Structural demand erosion: GLP-1 adoption compounding against the core loyal-customer base
- Industry-wide low-income consumer weakness persisting into 2027; restaurant inflation outpacing grocery widens the eat-at-home gap
- Execution credibility: management simultaneously raising margin targets while committing $8.5B invites skepticism that the 250bps efficiency math works
- Beef/input cost inflation pressuring franchisee margins and forcing value-destructive price increases (flagged but unconfirmed with late-2026 data)
What to watch
- US traffic frequency among loyalty members (the differentiated variable) vs headline comps, which can be propped by price/mix
- FY27 consensus EPS post-Oct 22: if $13.94 holds while the stock is 15%+ below pre-September levels, the de-rating is multiple compression and likely overdone
- Beverage initiative contribution to US comps — the one early-strength data point management cited
- Franchisee health indicators: any disclosure on per-restaurant cash flow vs the promised ~$100K/yr benefit
- Analyst PT moves post-earnings: does the $297-309 cluster compress toward the Melius $230 bear marker or hold
- Monthly US foot-traffic data for the first positive YoY month since March
Market snapshot when the call was made 2026-10-05
Price
| Return 1w | -1.9% |
| Return 1m | -11.1% |
| Return 3m | -17.0% |
| Return 6m | -24.5% |
| Return 1y | -22.8% |
| From 52-week high | -32.0% |
| Realized vol, 20d | 21.8% |
| SPY 3m / 1y | +2.4% / +15.1% |
| QQQ 3m / 1y | +6.6% / +24.8% |
Technicals
MCD technicals as of 2026-10-05: last close $233.04; 20d SMA 243.79 (bearish); 50d SMA 258.61; 12d EMA 237.61; 26d EMA 245.72; RSI 14 16.7 (oversold); 20d vol 21.4%; volume x0.9 vs 20d avg
Verifier notes PASS
Unsupported claims
- Minor arithmetic inconsistency: the opinion states 'At ~$233 (17.5x FY26 EPS of $12.89)' — but $233 / $12.89 = ~18.1x, not 17.5x. The ~17.5-17.7x forward P/E figure does appear verbatim in the evidence (quote/valuation feeds), so both numbers are individually sourced, but they are mutually inconsistent at the stated price. This is a ~3% discrepancy that does not change the thesis (the de-rating vs. low-20s historical multiple holds at either 17.5x or 18.1x), so it is not decision-material.
Corrections applied
- Either state the multiple as '~18x FY26 consensus EPS' (consistent arithmetic on $233 / $12.89) or quote the feed-sourced '~17.5-17.7x forward P/E' without pairing it with the $12.89 EPS at the $233 price, and note the small discrepancy comes from differing EPS bases across data feeds.
Sources (38 · T1 = primary filings)
- T2https://www.reuters.com/business/mcdonalds-outlines-85-billion-plan-support-franchisees-2026-09-23/
- T4https://nypost.com/2026/09/23/business/mcdonalds-shares-drop-after-ceo-reveals-lackluster-growth-forecast-as-i…
- T4https://corporate.mcdonalds.com/content/dam/sites/corp/nfl/pdf/MCD%20Q226%20Earnings%20Release%20-%20Exhibit%2…
- T4https://www.perplexity.ai/finance/MCD?comparing=MCD,DRI,JACK,WEN,DPZ,CAVA
- T2https://www.reuters.com/company/mcdonald-s-corp/
- T4https://quartr.com/companies/mcdonald-s-corporation_5595
- T4https://stockanalysis.com/stocks/mcd/transcripts/662377-q2-2026/
- T4https://www.theglobeandmail.com/investing/markets/stocks/MCD/pressreleases/3785465/mcdonalds-mcd-q2-2026-earni…
- T2https://www.reuters.com/business/mcdonalds-rivals-cheap-deals-no-longer-do-trick-2026-08-11/
- T4https://finance.yahoo.com/quote/1WEN.MI/earnings/1WEN.MI-Q2-2026-earnings_call-663910.html/
- T4https://www.investing.com/news/transcripts/earnings-call-transcript-restaurant-brands-tops-q2-2026-eps-forecas…
- T4https://www.alphaspread.com/security/nasdaq/wen/investor-relations/earnings-call/q2-2026
- T4https://www.investing.com/news/transcripts/earnings-call-transcript-wendys-posts-q2-2026-beat-as-traffic-slump…
- T4https://quartr.com/companies/the-wendy-s-company_6148
- T1https://www.sec.gov/Archives/edgar/data/1618756/000161875626000025/qsr_2026331xpressrelease.htm
- T4https://ca.investing.com/news/transcripts/earnings-call-transcript-wendys-posts-q2-2026-beat-as-traffic-slump-…
- T2https://www.reuters.com/legal/litigation/big-food-pours-millions-into-rebrands-obesity-drugs-reshape-us-demand…
- T2https://www.reuters.com/business/finance/ice-cream-makers-bet-consumers-still-want-treats-just-healthier-ones-…
- T2https://www.reuters.com/business/healthcare-pharmaceuticals/many-this-years-super-bowl-features-salad-food-com…
- T4https://abcnews.com/US/weight-loss-drug-usage-grows-restaurants-offer-glp/story?id=135711648
- T4https://money.usnews.com/investing/news/articles/2026-02-18/analysis-big-food-pours-millions-into-rebrands-as-…
- T2https://www.reuters.com/business/healthcare-pharmaceuticals/sauce-spice-makers-attract-deal-interest-glp-1s-se…
- T4https://www.tradingview.com/news/invezz:62e76d819094b:0-glp-1-weight-loss-pills-set-to-reshape-us-food-demand-…
- T2https://www.reuters.com/business/us-retail-sales-increase-again-april-partly-lifted-by-higher-prices-2026-05-1…
- T1https://www.sec.gov/Archives/edgar/data/63908/000006390826000076/mcd-20260923.htm
- T1https://www.sec.gov/Archives/edgar/data/0000063908/000006390826000076/exhibit991-investorupdate2.htm
- T1https://www.sec.gov/Archives/edgar/data/0000063908/000006390826000076/mcd-20260923.htm
- T1https://www.sec.gov/Archives/edgar/data/63908/000006390826000076/exhibit991-investorupdate2.htm
- T3https://www.cnbc.com/2026/09/23/mcdonalds-investor-day-remodels-training-chicken-growth-plans.html
- T4https://finance.yahoo.com/markets/stocks/articles/mcdonalds-commits-8-5-billion-161129453.html
- T4https://www.stocktitan.net/sec-filings/MCD/8-k.html
- T4https://www.marketbeat.com/stocks/NYSE/MCD/forecast/
- T4https://www.investing.com/equities/mcdonalds-news
- T4https://www.cnn.com/markets/stocks/MCD
- T4https://stockanalysis.com/stocks/mcd/
- T4https://www.benzinga.com/quote/MCD/price-targets
- T4https://markets.businessinsider.com/news/stocks/mcdonald-s-price-target-lowered-to-230-from-250-at-melius-rese…
- T4https://www.marketbeat.com/stocks/NYSE/MCD/dividend/
Earlier and later calls on MCD
- Oct 20, 2026Momentum trap — timing trap, not value trap.Lean bearishview changed
- Oct 9, 2026Cheap, but not yet cleared.Lean bullish
- Oct 6, 2026Oversold derating — lean bullish into Q3.Lean bullish
- Sep 23, 2026Dipped, yes. Undervalued, probably.Lean bullish
- Sep 23, 2026Washed out, not broken — lean bullish.Lean bullish
- Sep 6, 2026Yes, cautiously — it's a show-me buy.Lean bullish
Want a fresh look at MCD, or another name?
Queue a new deep-research run. Published to the feed when done.
Automated research opinion, published as-is on Oct 6, 2026. Not personalised advice. Figures use end-of-day closes.