Dipped, yes. Undervalued, probably.
Thesis
Bull case
The drawdown is ~90% multiple compression with only ~1-2% estimate cuts — the market de-rated the stock far faster than fundamentals deteriorated. At ~19x forward earnings versus a ~24x 5-year average, with EPS up over the 2021-2025 period despite interim setbacks, margins back at ~46% since 2023, a ~3% dividend yield (unverified this session), and even freshly-cut analyst targets 18-36% above the price, the setup is favorable if US traffic merely stabilizes. The RSI-20, 2.9x-volume capitulation into Investor Day looks like a sentiment washout; the $8.5B plan spread over a decade is affordable for a company with $12.4B operating income and could fix franchisee economics, unlocking the low-to-mid-50s% 2030 margin target. Any Q3 evidence of US comp stabilization or inflation relief for low-income consumers could trigger a sharp re-rating given how one-sided positioning appears.
Bear case
The dip is partly justified by management's own words: traffic could stay flat if inflation stays elevated, and the company felt compelled to commit $8.5B to prop up franchisee economics — an implicit admission that the core US value proposition is broken at current price points. Record beef costs (+25% y/y ground chuck) squeeze both franchisee margins and menu-value flexibility; the low-income consumer pullback may be structural (trade-down fatigue, GLP-1 adoption as a slow demand headwind) rather than cyclical. The QSR sector is broadly derating on rates and maturity, so ~24x may be the wrong anchor — if the 'right' multiple is 16-17x, the stock is fairly valued, not cheap. The 2030 margin target contradicts the simultaneous franchisee rescue, and the market is rationally skeptical both can hold.
What would change our mind
- Q3 2026 US comps negative AND management guides FY27 EPS below ~$13.50 — evidence the earnings base, not just the multiple, is impaired
- FY27 consensus EPS revisions accelerate downward beyond ~3-4% cumulative, breaking the 'modest revisions' premise
- Franchisee support plan expanded or described as ongoing/open-ended rather than bounded through 2036
- Operating margin guidance for 2027 cut below ~45%, contradicting the 2030 low-to-mid-50s% trajectory
- Stock fails to hold the 52-week low on heavy volume post-Q3, indicating institutional distribution rather than capitulation
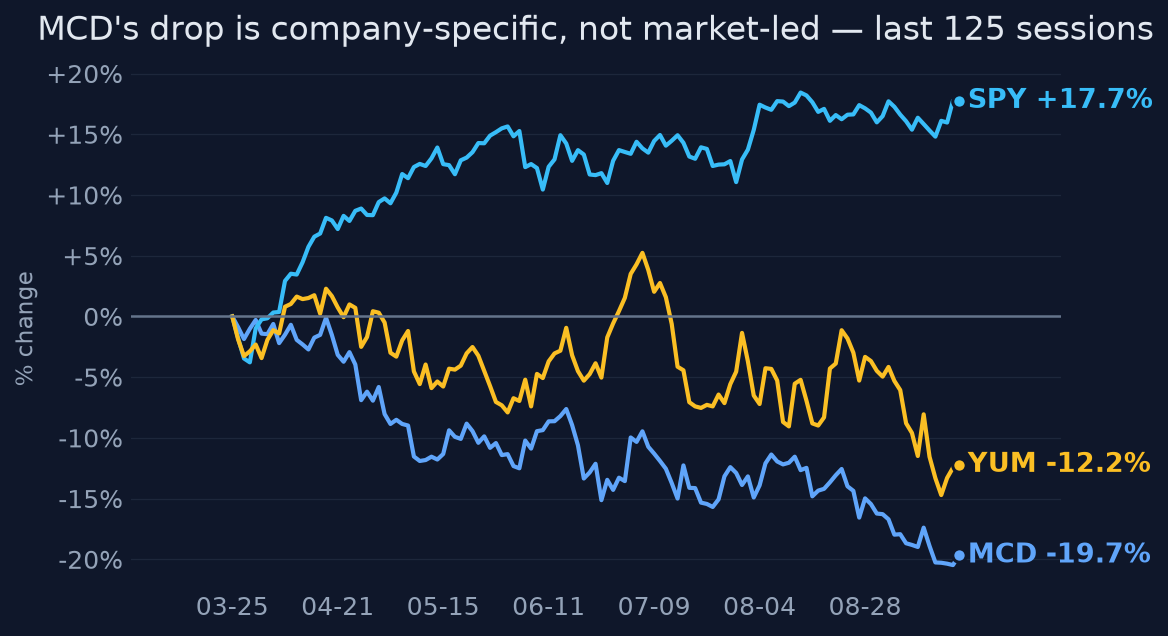
Since publication vs SPY · closed horizons are frozen
The full research everything the view rests on
Direct answer to the question asked
Where the edge would come from
What the price assumes
At ~19x forward earnings — a ~15-20% discount to its own 5-year average and roughly in line with or cheaper than YUM — the market is pricing that the US traffic/value problem is at least semi-permanent: that low-income consumer weakness persists, that the $8.5B franchisee support plan signals structurally impaired franchisee economics, and that the old ~24x premium multiple is gone for good. The September selloff around Investor Day specifically priced management's 'flat traffic if inflation stays elevated' caveat as the base case rather than the downside case.
Why the market may be wrong
The market may be conflating a conditional warning with a forecast. Management said traffic COULD stay flat IF inflation remains elevated — yet the stock sold off as if flat traffic were guidance. Meanwhile, EPS revisions of only 1-2% imply the analyst community does not believe earnings power is impaired, and the $8.5B support plan is spread through 2036 (~$5B by 2030) against a company generating ~$12.4B of operating income annually — meaningful but not margin-breaking. The technical picture (RSI 20, volume 2.9x average, capitulation-like trading into Investor Day) is consistent with a sentiment washout overshooting the fundamental deterioration.
The one thing to watch
The variable to watch is not comps or EPS — it is whether the $8.5B franchisee support plan is a one-time recapitalization of the franchise system or the first tranche of a permanent subsidy. MCD's entire ~46% operating margin model rests on franchisees self-funding; the 2030 target of low-to-mid-50s% operating margins is only credible if the support plan ENDS the franchisee economics problem rather than institutionalizing it. The market is pricing the latter; if Q3/Q4 commentary frames the plan as bounded and self-liquidating, the multiple re-rates without any traffic recovery at all.
Key evidence (10)
- Price: $238.32, -26.6% below 52-week high, +1% above 52-week low, max 1-yr drawdown -27.3%; 6m return -18.8% vs SPY +18.0% (computed from price history, 2026-09-23)
- Technicals: RSI(14) = 20 (oversold), below 20d/50d SMAs, volume 2.9x 20-day average around Sept 22-23 Investor Day (market data, 2026-09-23)
- Idiosyncrasy: 60-day beta to SPY -0.18, correlation ~-0.1, idiosyncratic share 99% — company/sector-specific repricing (quant analysis)
- Q2 2026 (Aug 4): adjusted EPS $3.38 beat vs $3.32 est.; revenue $7.10B missed ~$7.14B; US comps +0.8% disappointed; global comps +1.3%; management cited US execution lapses [Reuters, T2, 2026-08-04]
- Investor Day (Sept 22-23, 2026): warning that traffic in key markets could stay flat if inflation remains elevated; $8.5B franchisee support plan through 2036 (~$5B by 2030) via rent relief and capital support; targets ~250bps restaurant efficiency and low-to-mid-50s% operating margins by 2030 [Reuters T2; CNBC T3, 2026-09-23]
- Estimate revisions modestly negative: FY26 EPS $12.99→$12.92, FY27 $14.19→$13.94 over 3 months [MarketWatch/WSJ-sourced, T2/T3]
- Valuation: forward P/E ~18.7-19.4x vs ~23.5x FY24/FY25 and ~24x 5-yr average; EV/EBITDA ~15.5x vs ~19.4x 5-yr avg; roughly in line to slightly cheaper than YUM (~20-21.8x fwd) [T3/T4]
- Fundamentals resilient but not linear: revenue $23.2B→$26.9B over 2021-2025 with 2022 roughly flat ($23.18B); EPS $10.04→$11.95 over the period but declined in 2022 ($8.33, -17%) and 2024 ($11.39); operating margin dipped to 40.4% in 2022 and has run at ~45-46% since 2023 (SEC XBRL companyfacts)
- Analyst target cuts mid-Sept: Jefferies $350→$325 (Buy), TD Cowen $300→$282, Morgan Stanley $319→$308 (Equal Weight) — all still 18-36% above current price [T4-aggregated, consistent across reports]
- Bear evidence: low-income diners still pulling back [Reuters T2]; record beef prices (ground chuck +25% y/y July, WaPo T4); industry traffic down ~1.4-3.4%; GLP-1s not yet a measurable traffic hit (BJ's commentary, T4)
Catalysts and risks
Catalysts
- Q3 2026 earnings (expected late Oct/early Nov 2026) — first read on US traffic and comps post-Investor Day; the single most important near-term test
- Monthly US traffic/industry data and any update on low-income consumer trends
- Inflation prints (CPI) — management explicitly tied the traffic warning to inflation staying elevated; disinflation would defuse the overhang
- Follow-through details on the $8.5B franchisee plan deployment and franchisee health commentary
- Dividend announcement (MCD typically raises in Sept/Oct — a Dividend Aristocrat streak signal)
- Beef/commodity cost trajectory into 2027
Risks
- US traffic stays negative through Q3/Q4, converting the conditional warning into realized guidance cuts
- FY27 consensus $13.94 may not yet fully reflect franchisee support drag — further revisions would undermine the 'multiple compression only' thesis
- Franchisee support expands beyond $8.5B, signaling structural rather than one-time economics repair
- Sector-wide derating continues; ~24x historical multiple proves to be the wrong anchor in a higher-rate, mature-growth regime
- Low-income consumer weakness deepens (employment softness, resumption of trade-down acceleration)
- Beef inflation persists, forcing price increases that further damage value perception — a negative feedback loop
- Key facts on analyst targets and Investor Day specifics rest partly on T4 aggregators, though load-bearing items are Reuters/CNBC-confirmed
What to watch
- Q3 2026 US same-store sales and traffic split (traffic vs check) — stabilization of traffic is the re-rating trigger
- Management framing of the $8.5B plan: bounded/self-liquidating vs recurring subsidy
- FY27 EPS revision trend — whether $13.94 holds through Q3 reporting
- CPI/inflation trajectory given management's explicit conditional traffic warning
- Beef prices and franchisee margin commentary
- Dividend increase announcement (Sept/Oct board cycle) as a management-confidence signal
- Whether the stock reclaims the 20d/50d SMAs (~$255/$264) — first technical confirmation the selloff has exhausted
Market snapshot when the call was made 2026-09-23
Price
| Return 1w | -1.0% |
| Return 1m | -7.6% |
| Return 3m | -7.8% |
| Return 6m | -18.8% |
| Return 1y | -17.2% |
| From 52-week high | -26.6% |
| Realized vol, 20d | 18.3% |
| SPY 3m / 1y | +5.4% / +16.5% |
| QQQ 3m / 1y | +4.3% / +23.1% |
Technicals
MCD technicals as of 2026-09-23: last close $238.32; 20d SMA 254.99 (bearish); 50d SMA 263.81; 12d EMA 250.37; 26d EMA 256.24; RSI 14 20.0 (oversold); 20d vol 23.7%; volume x2.9 vs 20d avg
Verifier notes REVISE · opinion revised once
Unsupported claims
- Thesis and key_evidence claim 'revenue and EPS grew every year 2021-2025' and 'operating margin steady at ~45-46% throughout' — contradicted by the SEC XBRL series in the evidence bundle: revenue dipped slightly in 2022 ($23.22B→$23.18B), EPS fell in 2022 ($10.04→$8.33, -17%) and again in 2024 ($11.56→$11.39), and operating margin dropped to 40.4% in 2022 before recovering to ~45-46%. The 'grew every year / steady margins' framing overstates fundamental consistency and is load-bearing for the 'fundamentals remain intact' leg of the thesis.
Corrections applied
- Replace 'revenue and EPS grew every year 2021-2025, operating margin steady at ~45-46%' with an accurate version, e.g.: 'revenue grew in 4 of 5 years (roughly flat in 2022) from $23.2B to $26.9B; EPS rose from $10.04 to $11.95 over the period but declined in 2022 ($8.33) and 2024 ($11.39); operating margin dipped to 40.4% in 2022 and has run at ~45-46% since 2023.' The directional point (no earnings collapse matching the -27% drawdown) survives, but the 'every year / steady throughout' wording must go.
Sources (31 · T1 = primary filings)
- T4https://www.investing.com/equities/mcdonalds-news
- T4https://www.marketbeat.com/instant-alerts/price-mcdonalds-nyse-mcd-reaches-new-52-week-low-heres-why-2026-09-2…
- T4https://www.marketbeat.com/stocks/NYSE/MCD/
- T3https://www.cnbc.com/2026/09/22/mcdonalds-mcd-hosts-investor-day.html
- T4https://www.marketbeat.com/instant-alerts/price-mcdonalds-nyse-mcd-stock-price-down-17-should-you-sell-2026-09…
- T4https://stockanalysis.com/stocks/mcd/
- T2https://www.reuters.com/business/mcdonalds-outlines-85-billion-plan-support-franchisees-2026-09-23/
- T4https://tickeron.com/ticker/MCD/
- T4https://www.investing.com/news/stock-market-news/mcdonalds-outlook-valuation-estimates-and-the-investor-day-te…
- T4https://finance.yahoo.com/quote/YUM/key-statistics/
- T4https://koalagains.com/stocks/NYSE/MCD
- T4https://finviz.com/stock?t=MCD
- T4https://finance.yahoo.com/quote/MCD/key-statistics/
- T4https://stockanalysis.com/stocks/mcd/statistics/
- T4https://stockanalysis.com/stocks/yum/statistics/
- T4https://www.tradingpedia.com/2026/09/23/mcd-unveils-8-5b-franchise-plan-to-drive-2030-goals/
- T4https://journalrecord.com/2026/09/23/mcdonalds-85-billion-franchisee-plan-flat-traffic/
- T4https://www.rte.ie/news/business/2026/0923/1592685-mcdonalds-85-billion-franchisee-support-plan/
- T4https://www.foxbusiness.com/markets/mcdonalds-spend-8-5b-revamping-restaurants-tech-franchise-support.amp
- T2http://rmb.reuters.com/rmd/rss/item/tag:reuters.com,2026:newsml_KBN3V918M?channel=frL012
- T3https://www.cnbc.com/2026/09/23/mcdonalds-investor-day-remodels-training-chicken-growth-plans.html
- T4https://economictimes.indiatimes.com/markets/us-stocks/news/mcdonalds-lays-out-8-5-billion-franchisee-support-…
- T4https://www.boursorama.com/bourse/actualites-amp/mcdonald-s-devoile-un-plan-de-8-5-milliards-de-dollars-pour-s…
- T4https://www.tbsnews.net/world/us-shoppers-tighten-budgets-still-find-room-treats-and-splurges-1521736
- T4https://qsrresearchhub.com/article/qsr-cost-traffic-margin-pressure-2026/
- T2https://www.reuters.com/company/wendys-co/
- T4https://www.washingtonpost.com/food/2026/09/16/soaring-beef-prices-have-put-burgers-out-reach-some-americans/
- T4https://www.trefis.com/stock/mcd/articles/615678/why-has-mcdonalds-gone-quiet-on-its-low-income-customer/2026-…
- T4https://www.mcfadden-finch-group.com/record-beef-prices-are-reshaping-restaurant-menus-a-2026-prime-cost-playb…
- T4https://www.investing.com/news/transcripts/bjs-restaurants-at-barclays-conference-reset-gains-traction-93CH-48…
- T4https://www.theglobeandmail.com/investing/markets/markets-news/motley/2388928/cracker-barrel-cbrl-q3-2026-earn…
Earlier and later calls on MCD
- Oct 20, 2026Momentum trap — timing trap, not value trap.Lean bearishview changed
- Oct 9, 2026Cheap, but not yet cleared.Lean bullish
- Oct 6, 2026Oversold reset — cautiously attractive.Lean bullish
- Oct 6, 2026Oversold derating — lean bullish into Q3.Lean bullish
- Sep 23, 2026Washed out, not broken — lean bullish.Lean bullish
- Sep 6, 2026Yes, cautiously — it's a show-me buy.Lean bullish
Want a fresh look at MCD, or another name?
Queue a new deep-research run. Published to the feed when done.
Automated research opinion, published as-is on Sep 23, 2026. Not personalised advice. Figures use end-of-day closes.